

Hess Midstream LP HESM beat second-quarter 2026 earnings expectations even as lower throughput weighed on revenues. Higher tariff rates, third-party services and lower operating costs helped offset weaker oil, gas and water volumes.
Adjusted free cash flow also improved as capital spending fell sharply. The next test is whether those supports can hold as deferred maintenance and higher capital expenditures move into the second half.
HESM's Q2 Beat Came Despite Lower Throughput
HESM reported earnings of 75 cents per Class A share, up 1.4% year over year and 8.7% above the Zacks Consensus Estimate. Revenues and other income declined 3.7% to $399 million but topped the consensus mark by 1%.
Lower throughput was the main drag on revenues, partly offset by higher tariff rates and third-party services. Third-party services more than doubled to $17.9 million from $8.2 million, helping cushion softer affiliate activity.
Lower Costs Lift HESM's Second-Quarter Margin
Operating and maintenance expenses fell to $85.9 million from $94.1 million a year earlier, mainly due to lower employee and maintenance costs. Gross Adjusted EBITDA margin improved to 85% from 82%, with lower general and administrative allocations also supporting quarterly costs.
Adjusted EBITDA still slipped 0.7% to $313.7 million from $316 million, showing that lower costs did not fully offset weaker operating activity. Enterprise Products Partners L.P. EPD, another midstream operator, reported record second-quarter Adjusted EBITDA of $2.8 billion, up 17% year over year, providing a broader industry reference point.
HESM Expects Volumes to Improve in the Second Half
Management expects second-half volumes to exceed first-half levels. Full-year guidance remains 450-460 MMcf/d for gas gathering, 435-445 MMcf/d for gas processing and 125-135 MBbl/d for both crude terminaling and water gathering.
The expected improvement reflects normal timing as Chevron wells come online and efficiency gains from longer laterals. Management said those productivity gains can help maintain production with fewer wells, although HESM is not assuming meaningful production growth.
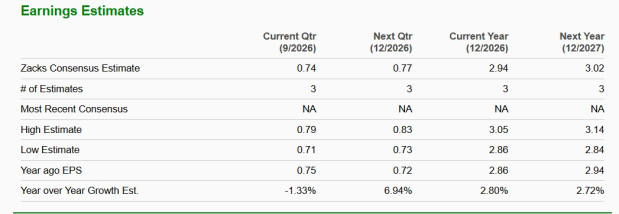
The Zacks Consensus Estimate for HESM’s 2026 earnings is pegged at $2.94 per share, indicating a 2.8% year-over-year increase.
Image Source: Zacks Investment Research
Deferred Maintenance Could Pressure HESM's Q3 Cash Flow
Some maintenance work originally planned for the second quarter shifted into the second half, temporarily benefiting costs and margins. HESM expects third-quarter Adjusted EBITDA of $310-$320 million as higher revenues and volumes are offset by higher operating expenses.
Adjusted free cash flow is expected to decline sequentially because capital spending is projected to rise from second-quarter levels. Western Midstream Partners, LP WES raised its 2026 free cash flow guidance to $1.1-$1.3 billion after record second-quarter Adjusted EBITDA, illustrating how throughput and capital spending can produce different cash-flow paths across midstream peers.
HESM's Short-Term Signal Meets Weak Momentum
The second-quarter beat was supported by tariffs, cost control and lower capital spending, but second-half execution will determine whether higher volumes can absorb normalized maintenance and investment. Full-year Adjusted EBITDA guidance of $1.225-$1.275 billion is roughly flat at the midpoint versus 2025.
HESM currently carries a Zacks Rank #2 (Buy), which signals a favorable short-term earnings estimate-revision setup. Its Momentum Score of F and Value Score of D are weak, while the Growth Score of C sits in the middle of the range. The VGM Score of D shows that the combined value, growth and momentum profile remains less supportive.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Hess Midstream Partners LP (HESM): Free Stock Analysis Report
Enterprise Products Partners L.P. (EPD): Free Stock Analysis Report
Western Midstream Partners, LP (WES): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).