

Chewy, Inc. CHWY is combining recurring Autoship demand, customer growth and expanding health offerings with improving profitability. The stock was priced at $18.55 as of Sept. 23, 2026, while the Zacks Equity Research price target is $20.
The investment case depends on whether those operating gains can offset softer discretionary spending, cost pressures and competition. Chewy's current valuation of 12.9X forward earnings and 0.4X forward PEG provides context for that trade-off.
AAA
Autoship Gives Chewy a Recurring Revenue Base
Autoship customer sales increased 9.3% year over year in the second quarter of fiscal 2026 and accounted for 84.6% of net sales. Active customers reached 21.7 million, up 3.8% year over year, while net sales per active customer rose to $602.
Chewy said that its customer funnel continued to benefit from customer additions, improved retention and reactivation of lapsed customers. The combination supports recurring demand and gives the company a larger base from which to expand engagement. Petco Health and Wellness Company, Inc. WOOF is another pet-focused retailer included among Chewy's industry peers, providing a useful reference point for the competitive environment.
Chewy Health Expands the Growth Opportunity
Chewy Vet Care delivered triple-digit revenue growth in the second quarter, while Modern Animal and SmartPak performed ahead of expectations. Management said Modern Animal and Chewy Vet Care provide complementary capabilities, greater scale and telehealth offerings that can broaden the veterinary platform.
The health ecosystem also gives Chewy additional ways to engage existing customers beyond merchandise. Freshpet, Inc. FRPT, another company included among Chewy's industry peers, operates in pet food rather than veterinary services, illustrating the breadth of businesses competing for pet owners' spending across the category.
Profitability Shows Structural Improvement
Adjusted EBITDA rose 23.7% year over year to $226.7 million in the second quarter, while the adjusted EBITDA margin expanded 90 basis points to 6.8%. Sponsored ads, a shift toward higher-margin health products, automation and AI-enabled productivity are supporting the underlying margin profile.
The quarter also included more than $15 million of discrete benefits and about $10 million of timing-related benefits, including tariff refunds and rebate benefits. Management indicated that these items accounted for essentially all of the adjusted EBITDA outperformance versus expectations, making the quality of the quarterly margin gain an important consideration.
Latest EPS Performance Adds Context
Chewy's latest EPS performance was broadly in line with expectations. For the second quarter of fiscal 2026, adjusted earnings were 36 cents per share, up 3 cents year over year.
Chewy Price, Consensus and EPS Surprise
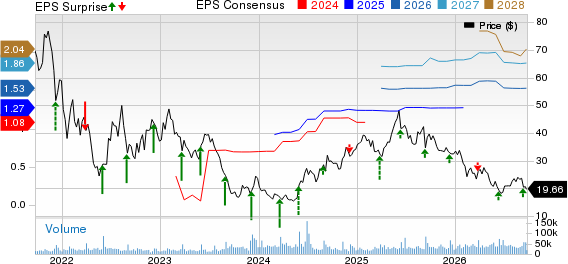
Chewy price-consensus-eps-surprise-chart | Chewy Quote
Valuation Meets Consumer Spending Risks
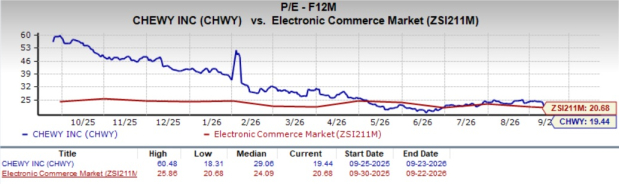
Chewy trades at 19.44X forward earnings. The metric provides one lens on the shares, but earnings conversion remains exposed to operating risks.
Image Source: Zacks Investment Research
Consumer spending on discretionary pet products remained soft, with treats showing sharper moderation than core food. Share-based compensation and related taxes totaled $159.3 million in the first half of fiscal 2026, while transaction costs and interest expense also weigh on reported earnings. Competition and premiumization add further pressure.
Valuation Signals Meet the Zacks Rank
Chewy currently carries a Zacks Rank #4 (Sell). Its Zacks Style Scores include a VGM Score of A, a Value Score of B, a Growth Score of A and a Momentum Score of D. The Style Scores are complementary indicators that assess value, growth and momentum characteristics, while the Zacks Rank focuses on trends in earnings estimate revisions.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The combination shows why the operating picture and the quantitative signals can point in different directions. Chewy has recurring revenue, expanding health services and improving efficiency, but the current Zacks Rank reflects the importance of earnings estimate trends in the short-term stock outlook. Investors weighing the shares must consider those signals alongside valuation, consumer demand and the sustainability of margin gains.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Chewy (CHWY): Free Stock Analysis Report
Freshpet, Inc. (FRPT): Free Stock Analysis Report
Petco Health and Wellness Company, Inc. (WOOF): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).