

Voya Financial, Inc.’s VOYA Employee Benefits segment is emerging as an increasingly important contributor to earnings growth, with profitability showing a substantial improvement. In the second quarter of 2026, the segment’s trailing-12-month net revenues increased 13% year over year, while the aggregate loss ratio improved to 74%. This drove the trailing-12-month adjusted operating margin to 11% from 3.7%, highlighting the benefits of stronger underwriting discipline, pricing actions and expense management.
The profitability improvement has a strong underlying foundation, as Voya continues to emphasize disciplined risk selection and pricing adequacy rather than chasing premium growth. Annualized in-force premiums and fees were approximately $3.6 billion, unchanged year over year, allowing management to focus on improving the profitability of its business. Ongoing pricing actions should help counter higher claims costs, while expense discipline provides an additional lever for margin expansion. The improvement in the aggregate loss ratio suggests that better underwriting performance is becoming an important driver of earnings.
Although quarterly earnings can fluctuate because of claims experience, the broader TTM trend remains favorable. Employee Benefits generated $22 million of pre-tax adjusted operating earnings in the second quarter of 2026 compared with $69 million in the prior-year quarter, with the year-ago period benefiting from unusually favorable Stop Loss claims development.
As claims experience normalizes, continued improvements in Group Life, Voluntary Benefits and Stop Loss, coupled with pricing discipline and expense management, could support further earnings growth. With the TTM adjusted operating margin reaching 11%, the segment’s improving underwriting profile provides Voya with a stronger foundation for sustainable profitability.
What About Its Peers?
MetLife, Inc.’s MET Group Benefits business is showing strong momentum. In the second quarter of 2026, the improvement in adjusted earnings was driven by favorable underwriting and volume growth, highlighting the benefits of disciplined risk selection and expanding business volumes. MetLife’s performance suggests that favorable underwriting trends and demand for workplace benefits can support earnings growth even as insurers remain focused on maintaining pricing adequacy and controlling claims. MetLife’s strong Group Benefits performance provides a constructive industry backdrop, although continued improvement in loss ratios, claims experience and underwriting margins will remain important for sustaining profitability gains.
The Hartford Insurance Group, Inc.’s HIG Employee Benefits business is supported by higher new business sales, increased exposure on existing accounts and persistency above 90%. Fully insured ongoing sales are driven by stronger group disability and group life sales, highlighting continued demand for workplace benefits. HIG’s results underscore the opportunity for premium and sales growth in Employee Benefits while also highlighting the importance of pricing discipline, claims management and expense control in sustaining underwriting profitability.
VOYA’s Price Performance
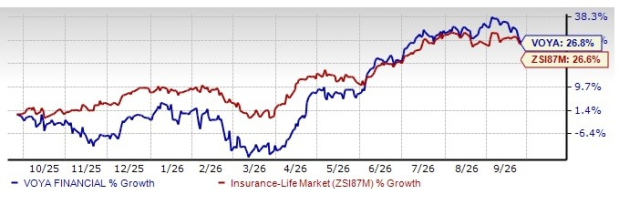
Shares of VOYA have gained 26.8% in the past year, outperforming the industry.
Image Source: Zacks Investment Research
VOYA’s Undervaluation
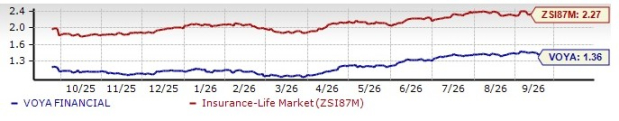
The stock is undervalued compared with its industry. Its forward price-to-book value of 1.36X is lower than the industry average of 2.27X.
Image Source: Zacks Investment Research
Estimate Movement for VOYA
The Zacks Consensus Estimate for VOYA’s third-quarter and fourth-quarter 2026 EPS has moved up 6.4% and 5%, respectively, in the past 60 days. The same for full-year 2026 EPS has moved down 1.2%, while 2027 EPS has moved up 1.15% in the past 60 days.
Image Source: Zacks Investment Research
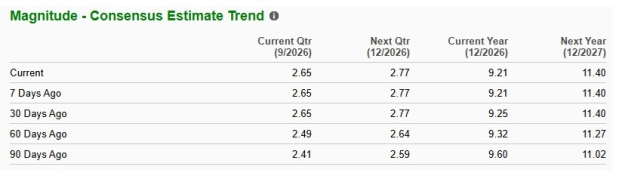
The consensus estimate for VOYA’s 2026 EPS indicates a year-over-year increase, while that of 2027 EPS and revenues indicates a year-over-year rise.
VOYA stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Voya Financial, Inc. (VOYA): Free Stock Analysis Report
The Hartford Insurance Group, Inc. (HIG): Free Stock Analysis Report
MetLife, Inc. (MET): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).