

Ulta Beauty, Inc. ULTA shares have gained 20.7% in the past three months as the beauty retailer’s operating picture has improved. Second-quarter fiscal 2026 sales and earnings rose, and management raised its full-year outlook after the stronger first half.
The advance now puts more weight on execution. Better results, digital growth and new business initiatives support the setup, but traffic, promotions, margins and valuation leave less room for a stumble.
Ulta Beauty’s 20.7% Gain Reflects a Stronger Setup
ULTA’s three-month gain has coincided with better operating momentum. Second-quarter net sales increased 8.9% to $3.04 billion, while earnings rose 13.3% to $6.55 per share.
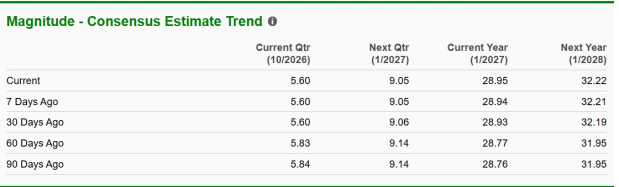
Management also raised fiscal 2026 guidance. It now expects net sales growth of 6.7%-7.2%, comparable sales growth of 3.2%-3.7% and earnings of $28.70-$29.00 per share.
Image Source: Zacks Investment Research
ULTA’s Q2 Beat Adds Fundamental Support
Second-quarter earnings of $6.55 per share topped the Zacks Consensus Estimate of $6.21. Sales of $3.04 billion also came in above the $2.97 billion consensus mark.
Comparable sales rose 3.8%. Average ticket increased 3.9%, while transactions were roughly flat, showing that spending per visit rather than traffic did most of the work.
Ulta Beauty’s Growth Engines Back the Momentum
E-commerce sales grew at a high-teens rate, extending the company’s run of double-digit digital growth. Ulta Beauty also has about 47 million active loyalty members, while Marketplace now includes more than 450 brands and UB Media delivered double-digit growth.
The store base remains another growth lever. Management sees room for more than 1,800 freestanding U.S. locations versus 1,534 at the end of the second quarter. e.l.f. Beauty ELF, which reported 36% sales growth in its latest quarter, also shows that beauty demand remains active across retailer and e-commerce channels.
ULTA’s Valuation Raises the Bar for More Upside
ULTA trades at 17.6X forward 12-month earnings. That is above the 14.3X Zacks sub-industry multiple but below the stock’s five-year median of 18.5X.
Image Source: Zacks Investment Research
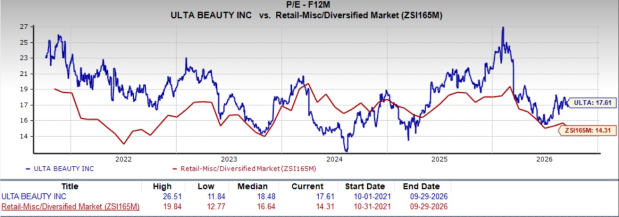
The valuation is not extreme relative to Ulta Beauty’s own history, but the recent rally leaves less tolerance for weaker execution. Stronger earnings and sales trends can help support the multiple, while a slowdown could make the premium to the sub-industry harder to defend.
Ulta Beauty Still Faces Traffic and Margin Risks
Traffic remains the clearest near-term constraint. Transactions were roughly flat in the second quarter, promotional activity increased and category trends were uneven, with fragrance strong while makeup was approximately flat.
Management expects gross margin to remain roughly flat for fiscal 2026 and operating margin to improve by no more than 20 basis points. Sally Beauty Holdings, Inc. SBH sells and distributes professional beauty supplies through Sally Beauty and Beauty Systems Group, keeping competition broad across hair color and hair care.
ULTA’s Mixed Signals Temper the Rally Case
Ulta Beauty’s improved results and higher guidance support the recent advance, but continued gains likely require better traffic and steady execution as comparisons become tougher. Ticket growth alone may not be enough if promotions rise or category strength narrows.
The stock currently carries a Zacks Rank #3 (Hold), with a Growth Score of B, Value Score of C, Momentum Score of D and VGM Score of C. The Growth Score fits a firmer earnings backdrop, including a 0.1% increase in the current-year EPS estimate over the past four weeks. The weaker Momentum Score and middling Value and VGM Scores leave a more balanced signal after the three-month run. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Ulta Beauty Inc. (ULTA): Free Stock Analysis Report
Sally Beauty Holdings, Inc. (SBH): Free Stock Analysis Report
e.l.f. Beauty (ELF): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).