

American Financial Group, Inc. AFG has a reasonable chance of keeping premium growth above the broader P&C market in the near term, but the source of that outperformance is likely to shift from pricing toward new business, exposure growth and market-share gains.
AFG’s performance in the second quarter of 2026 results support this view. Specialty P&C net written premiums increased 6% year over year, versus a broader U.S. P&C market where premium growth has flattened. AFG achieved growth across each of its three Specialty P&C groups, helped by new business opportunities, increased exposures and favorable renewal pricing. Its 36-business diversification is particularly useful as individual markets soften.
The mix of AFG's businesses is the key advantage. Property & Transportation NWP rose 5%, Specialty Casualty increased 6%, and Specialty Financial grew 10% in the second quarter. The financial group generated 10% premium growth even though renewal pricing declined by less than 1%, demonstrating that AFG can grow without relying entirely on rate increases.
However, maintaining a growth rate of more than 6% becomes harder as the market moves further into a softer phase. According to Marsh, U.S. commercial insurance rates declined 2% in second-quarter 2026. Swiss Re expects U.S. P&C premium growth to slow to around 3% in 2026, reinforcing the potential for AFG to outperform the industry if it continues to capture business selectively.
AFG's premium growth can remain above the broader market because its specialty-focused portfolio gives it access to niches that are still experiencing stronger demand and pricing. If AFG can maintain roughly 5-6% NWP growth while preserving its underwriting discipline, that would demonstrate that its growth is becoming less dependent on the insurance pricing cycle.
What About Other Insurers?
W.R. Berkley Corporation WRB offers a useful example of how a specialty insurer can maintain premium growth even as pricing moderates. In the second quarter of 2026, WRB’s Insurance segment gross written premiums grew across several specialty businesses. Importantly, renewal rate increases were more moderate, indicating that premium growth is increasingly being driven by exposure growth, new business and favorable business mix, rather than rate increases alone. WRB’s diversified specialty platform lets it deploy capacity selectively to markets offering attractive risk-adjusted returns while reducing exposure where pricing becomes inadequate. This suggests that insurers with strong specialty franchises and disciplined underwriting can potentially sustain above-market premium growth even as the broader P&C pricing cycle softens.
Chubb Limited CB provides another example of an insurer that can potentially maintain above-market premium growth as pricing moderates, supported by its diversified geographic and product mix. The company’s broad specialty, commercial, personal and international platforms allow it to capture exposure growth and new-business opportunities even as renewal pricing becomes less favorable. Chubb’s ability to shift capacity toward markets with stronger demand and attractive returns also reduces its dependence on broad-based rate increases. Consequently, investors will likely focus on whether exposure growth, new business, international expansion and favorable mix can increasingly offset moderating renewal pricing and help Chubb sustain premium growth above the broader P&C market.
AFG’s Price Performance
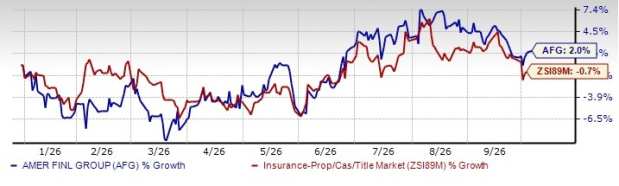
Shares of AFG have gained 2% in the year-to-date period, outperforming the industry.
Image Source: Zacks Investment Research
AFG’s Overvaluation
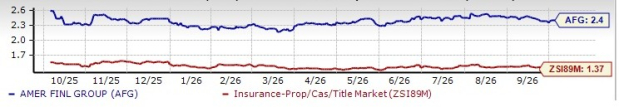
The stock is overvalued compared with its industry. It is currently trading at a price-to-book value multiple of 2.4, higher than the industry average of 1.37. It carries a Value Score of B.
Image Source: Zacks Investment Research
Estimate Movement for AFG
The Zacks Consensus Estimate for AFG’s third-quarter 2026 has moved up 19.4%, and the fourth-quarter 2026 EPS has moved down 0.3% in the past 60 days. The same for full-year 2026 and 2027 EPS has moved up 8.1% and 0.2%, respectively, in the past 60 days.
Image Source: Zacks Investment Research
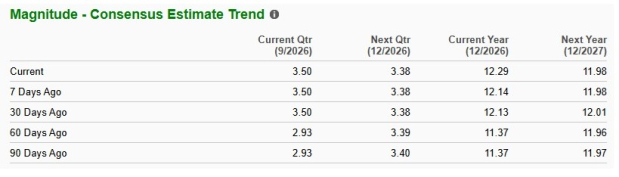
The consensus estimate for AFG’s 2026 EPS and revenues and 2027 revenues indicates a year-over-year increase.
AFG stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
American Financial Group, Inc. (AFG): Free Stock Analysis Report
Chubb Limited (CB): Free Stock Analysis Report
W.R. Berkley Corporation (WRB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).