

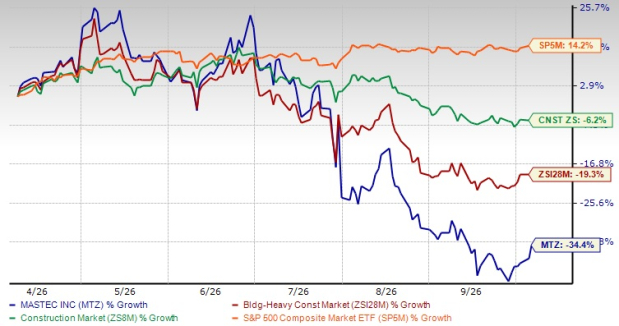
Shares of MasTec, Inc. MTZ have lost 34.3% over the past six months compared with the Zacks Building Products - Heavy Construction industry's decline of 19.3%. The stock has also lagged the Zacks Construction sector and the S&P 500 Index, as evidenced by the chart below.
MTZ’s 6-Month Price Performance
Image Source: Zacks Investment Research
This Florida-based infrastructure construction company continues to benefit from strong demand across power infrastructure, pipeline, clean energy and mission-critical projects. Record backlog and solid activity across several businesses support its growth prospects. However, near-term challenges in Communications, project timing and cash generation are weighing on the investment case.
Despite the company’s strong backlog and raised full-year outlook, several near-term factors remain concerns for investors. Lower Communications expectations, delayed project starts, higher project-related costs and weak free cash flow may limit the pace at which earnings growth translates into cash generation. In addition, much of the recent backlog growth is expected to benefit 2027 rather than 2026, while the integration of Superior adds another layer of execution and balance-sheet considerations.
Let us examine the key factors that may weigh on MTZ’s prospects.
Communications Pressure Weighs on Near-Term Results
MasTec’s Communications business remains the main source of near-term pressure as project timing and higher operating costs weigh on results. In the second quarter of 2026, segment revenues increased 6.2% year over year to $888.9 million. EBITDA declined 11.6% to $73.1 million, while the EBITDA margin contracted 170 basis points (bps) to 8.2%. Execution challenges on certain projects, along with higher indirect fuel and equipment costs, also reduced profit flow-through.
The pressure is expected to persist through the remainder of 2026, with the company lowering its full-year segment revenue outlook to approximately $3.25 billion from approximately $3.65 billion previously. The company also expects the segment EBITDA margin to remain under pressure, with the margin projected in the high single digits, but about 100 bps lower than the prior year. Wireless revenues are expected to decline in the second half as customers wait for new spectrum equipment, while some wireline projects have been delayed. Although the longer-term outlook remains intact, weaker segment results could limit consolidated growth in the near term.
MTZ’s Cash Generation Remains Under Pressure
Cash generation remains a weak spot despite the company’s earnings growth. MasTec reported negative free cash flow of $59 million in the second quarter of 2026, compared with negative $45 million a year ago. For the first six months, free cash flow was negative $47.6 million, while it was roughly break-even in the prior-year period.
The gap between cash generation and investment also remains notable. Operating cash flow was $120.3 million in the first half, while capital expenditures reached $188.3 million. The company expects operating cash flow to exceed $1 billion for 2026, with most of the inflow expected in the fourth quarter. The ability to convert earnings into cash will therefore remain important as MasTec funds its ongoing investments and manages the balance sheet.
MasTec Remains Exposed to Project Timing and Cost Risks
MasTec’s results remain sensitive to project timing, customer spending decisions and execution across its infrastructure markets. The Communications business is already seeing wireline project starts pushed back by several months, while the company also expects some moderation in Pipeline project timing and mix during the third quarter of 2026. Higher fuel and equipment costs have added further pressure in Communications.
These timing issues are important because MasTec is pursuing increasingly large and complex projects, many of which take time to move from pursuit to backlog and revenues. The company has seen a meaningful increase in large project pursuits, but some of the opportunities are not expected to contribute materially until 2027 or later. This could create uneven revenue conversion even as long-term demand remains strong.
MTZ’s Earnings Estimates Show Mixed Revisions
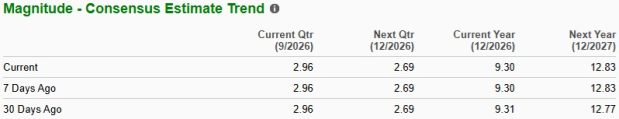
MasTec’s earnings estimates for 2026 and 2027 stand at $9.30 and $12.83 per share, respectively. While the 2027 estimate has moved higher over the past 30 days, the 2026 estimate has declined, signaling some near-term pressure on earnings expectations. Even so, the estimates imply strong year-over-year earnings growth of 42% for 2026 and 37.9% for 2027.
MTZ EPS Estimate Revision Trend
Image Source: Zacks Investment Research
MTZ Stock Trades at a Premium
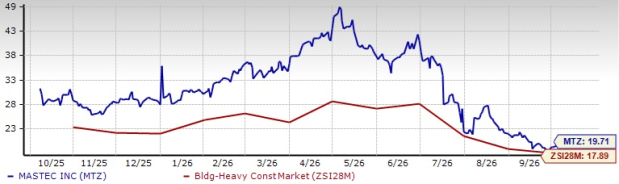
MasTec stock is currently trading at a premium compared with its industry peers, with a forward 12-month price-to-earnings (P/E) ratio of 19.71, as shown in the chart below.
MTZ Valuation (P/E F12M)
Image Source: Zacks Investment Research
MasTec & Its Key Infrastructure Peers
MasTec competes closely with Quanta Services, Inc. PWR, EMCOR Group, Inc. EME and Dycom Industries, Inc. DY in the infrastructure and engineering construction market.
Quanta operates across utility, technology and load center markets, providing electrical, mechanical, civil and fabrication services. Its broad capabilities and long-standing customer relationships support large and complex infrastructure projects. Quanta also has exposure to technology, power generation and utility markets. However, utility capital spending and the timing of large project awards can affect growth.
Meanwhile, EMCOR has a diversified construction and services platform spanning electrical, mechanical, building and industrial markets. Strong demand from data centers, network and communications, manufacturing and institutional markets supports growth. EMCOR also benefits from its ability to execute complex projects across multiple trades and geographies. However, project mix and timing can affect margins and revenue growth.
Dycom has a more specialized position in digital and critical infrastructure, with exposure to fiber-to-the-home, long-haul fiber, data center interconnects and data center electrical and structured cabling systems. Strong demand across these markets supports growth opportunities, while its record backlog provides visibility into future activity. However, investments to scale its operations and the timing of wireless projects can affect near-term revenues and margins.
How to Play MTZ Stock?
Despite MasTec’s strong backlog, solid demand across power infrastructure, clean energy and other key markets, its near-term outlook remains challenging. The raised 2026 guidance and strong earnings growth provide support, but pressure in Communications, delayed project starts, weak free cash flow and uneven revenue conversion remain concerns. The stock’s premium valuation also leaves less room for execution setbacks, while the lower 2026 earnings estimate points to some pressure on near-term expectations.
Thus, MTZ stock’s current risk-reward profile remains challenging, supporting its Zacks Rank #4 (Sell). Investors are currently advised to steer clear of MasTec until the trends move more in favor of the stock.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
MasTec, Inc. (MTZ): Free Stock Analysis Report
Quanta Services, Inc. (PWR): Free Stock Analysis Report
EMCOR Group, Inc. (EME): Free Stock Analysis Report
Dycom Industries, Inc. (DY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).