

Levi Strauss & Co. LEVI reported mixed third-quarter fiscal 2026 results, with earnings surpassing the Zacks Consensus Estimate but revenues falling short. The denim apparel maker benefited from tariff refunds, international expansion, wholesale strength and improved profitability. The company also raised its fiscal 2026 profit outlook. However, softer direct-to-consumer (DTC) traffic in the United States and Europe weighed on performance.
Adjusted earnings of 48 cents per share topped the Zacks Consensus Estimate of 36 cents and increased 41.2% year over year. Revenues rose 4.3% to $1,610 million but missed the consensus estimate of $1,615 million. Organic revenues grew 5%, while DTC comparable sales increased just 0.4%.
Levi Strauss & Co. Price, Consensus and EPS Surprise
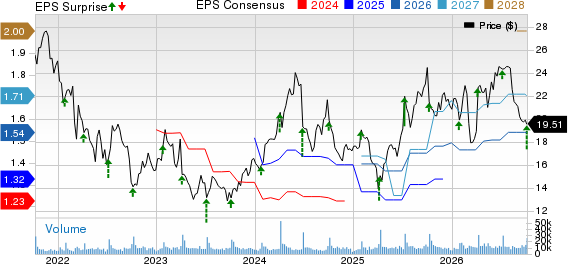
Levi Strauss & Co. price-consensus-eps-surprise-chart | Levi Strauss & Co. Quote
LEVI's DTC Growth Slows Amid Traffic Challenges
Levi Strauss' DTC revenues increased 2% on both reported and organic bases, reflecting softer traffic across the United States and Europe. The channel contributed 45% of total revenues during the quarter. E-commerce revenues advanced 10%, reflecting continued digital momentum.
U.S. DTC revenues declined 1%, while Europe's fell 2% on a reported basis. Management attributed the weakness to an underperforming back-to-school campaign in the United States and unusually warm weather across European markets. Meanwhile, global wholesale revenues increased 6%, supported by broad-based demand across regions and product categories.
Levi Strauss' Regional Performance Remains Mixed
The Americas generated $839 million of revenues, up 4% on a reported basis and 2% organically. U.S. revenues declined 1%, while Latin America delivered 10% organic growth, supported by strength across channels and markets.
Europe reported revenues of $442 million, up 4% on a reported basis and 5% organically. Double-digit wholesale growth supported regional performance despite weaker DTC traffic. Asia generated $293 million, increasing 5% on a reported basis and 10% organically. Momentum across Japan, India, Australia and China supported the region's growth.
LEVI's Brand & Category Momentum Continues
The Levi's brand registered 4% organic growth, supported by mid-single-digit gains across men's and women's businesses. Categories beyond denim bottoms contributed approximately half of quarterly organic revenue growth, highlighting the company's expanding lifestyle portfolio.
Tops revenues increased 7%, with women's tops advancing 10%. The premium Blue Tab collection delivered strong double-digit growth, while Levi Strauss Signature grew 13%, aided by core denim and expanding lifestyle offerings. Beyond Yoga revenues increased 9% to $36 million, supported by growth across both distribution channels.
Levi Strauss' Margins Benefit From Tariff Refunds
Gross profit increased to $1.07 billion from $951.6 million in the year-ago quarter. Gross margin expanded 450 basis points to 66.2%, including a 370-basis-point net benefit from tariff refunds. Excluding this benefit, underlying gross margin expanded 80 basis points, supported by lower product costs and partly offset by foreign exchange pressures.
Selling, general and administrative (S&G) expenses increased to $835.9 million from $775.6 million. Adjusted SG&A rose 6.2% to $817 million, primarily reflecting higher selling and distribution expenses. Adjusted EBIT increased 36% to $249 million, while adjusted EBIT margin expanded 370 basis points to 15.5%, including a 330-basis-point net tariff refund benefit.
Notably, tariff refunds contributed 11 cents to adjusted earnings after reinvestment. Excluding this benefit, adjusted earnings increased approximately 9% year over year, supported by underlying margin expansion and share repurchases.
LEVI's Financial Position & Shareholder Returns
Levi Strauss ended the quarter with cash and cash equivalents of $641 million and total liquidity of approximately $1.5 billion. Inventories declined 3% year over year, reflecting continued inventory management discipline.
The company returned $61.6 million to shareholders through dividends, representing an 11% year-over-year increase. It also announced plans for an additional $100 million accelerated share repurchase program. The company declared a quarterly dividend of 16 cents per share, reflecting a 14% increase from the year-ago level.
Levi Strauss Raises Its Fiscal 2026 Profit Outlook
Management raised its fiscal 2026 adjusted earnings guidance to $1.54-$1.56 per share from $1.46-$1.52. The revised outlook includes an approximately 4-cent net tariff refund benefit. Adjusted EBIT margin is expected to reach about 12.1% compared with the previous 12% outlook. Gross margin is projected to expand 130 basis points year over year.
Reported revenue growth is expected at approximately 7% compared with the earlier 7-7.5% range, reflecting foreign exchange headwinds. Organic revenue growth is projected at approximately 6%, the upper end of the previous guidance.
For the fourth quarter, management anticipates reported and organic revenue growth of approximately 3% and 4%, respectively. Adjusted EBIT margin is expected to be between 11.4% and 11.6%, with adjusted earnings projected at 36-38 cents per share. Management expects DTC growth to recover to mid-single digits, supported by targeted marketing, stronger product assortments and improving traffic trends.
LEVI Stock Past Three-Month Performance
Image Source: Zacks Investment Research
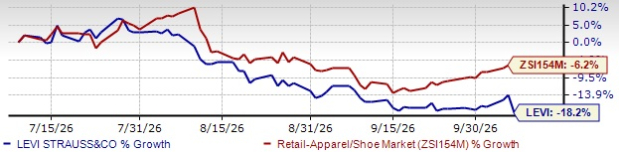
Shares of this Zacks Rank #3 (Hold) company have lost 18.2% over the past three months as compared with the industry’s 6.2% decline.
Solid Picks in Retail
Genesco Inc. GCO is a Nashville-based specialty retailer and branded company. It sells footwear and accessories through retail stores. The company sports a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Genesco’s current fiscal-year earnings indicates 62.1% growth from the year-ago actual. GCO delivered a trailing four-quarter average earnings surprise of 11.2%.
Designer Brands Inc. DBI designs, produces and retails footwear and accessories. It offers shoes, boots, sandals, sneakers, socks, handbags and accessories. It currently carries a Zacks Rank #2 (Buy).
The Zacks Consensus Estimate for Designer Brands’ current fiscal-year earnings and sales suggests growth of 225% and 0.6%, respectively, from the year-ago actuals. DBI delivered a trailing four-quarter average earnings surprise of 108.1%.
Urban Outfitters, Inc. URBN is a lifestyle products and services company that sells fashion apparel, accessories, footwear, home goods and related offerings through a portfolio of global consumer brands. The company also holds a Zacks Rank of 2 at present.
The Zacks Consensus Estimate for Urban Outfitters’ current fiscal-year earnings and sales suggests growth of 14% and 9.5%, respectively, from the year-ago actuals. URBN delivered a trailing four-quarter average earnings surprise of 9.7%.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Levi Strauss & Co. (LEVI): Free Stock Analysis Report
Urban Outfitters, Inc. (URBN): Free Stock Analysis Report
Genesco Inc. (GCO): Free Stock Analysis Report
Designer Brands Inc. (DBI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).