

Jabil Inc. JBL enters fiscal 2027 with faster AI infrastructure growth, improving profitability and a strong earnings outlook. Management expects revenues of $44.5 billion and core earnings of $17.55 per share, representing year-over-year growth of 24% and 34%, respectively.
The valuation is less straightforward. JBL trades below key market comparisons, but its forward earnings multiple remains above its own five-year median. Investors must weigh that premium against a materially stronger growth and margin profile.
Jabil’s AI Growth Strengthens the Bull Case
AI-related revenues reached about $14.4 billion in fiscal 2026, increasing more than 50% year over year. Management expects AI-related revenues to rise 54% to roughly $22.1 billion in fiscal 2027 as demand expands across compute, networking, power and cooling infrastructure.
Intelligent Infrastructure revenues are projected to climb 43% to $25.6 billion. Cloud and data center infrastructure is expected to lead the increase, with revenues projected to advance 52% to $17.5 billion. Capital equipment revenues are forecast to rise 40%, while networking revenues are expected to grow 15%.
JBL Trades Below Peers but Above Its Own Median
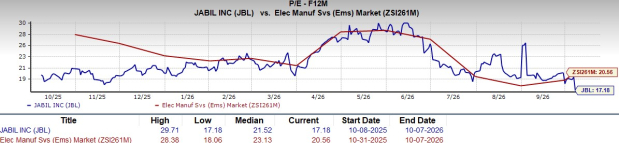
JBL trades at 17.2X forward 12-month earnings, below 20.6X for the Zacks sub-industry, 21.3X for the Zacks Computer and Technology sector and 20.0X for the S&P 500. That relative discount supports the valuation case, but Jabil’s multiple remains above its five-year median of 13.8X.
Image Source: Zacks Investment Research
Celestica Inc. CLS, a provider of design, manufacturing, hardware platform and supply chain solutions, is a relevant peer for Jabil’s broader manufacturing and infrastructure exposure. Plexus Corp. PLXS, which designs, manufactures and services complex products across industrial, healthcare and aerospace markets, provides another comparison within the electronic manufacturing services landscape.
Jabil’s Margin and Cash Flow Outlook Adds Support
Core operating margin increased 40 basis points to 5.8% in fiscal 2026. Management expects another 30-basis-point improvement to 6.1% in fiscal 2027 as a richer business mix and operating leverage support profitability.
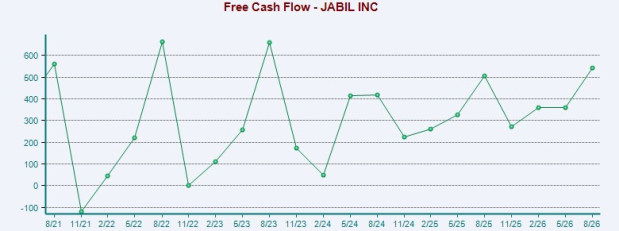
Adjusted free cash flow reached $1.53 billion in fiscal 2026, up from $1.32 billion in fiscal 2025. Jabil expects approximately $1.6 billion in fiscal 2027, giving the company flexibility to invest in capacity while continuing shareholder returns.
Image Source: Zacks Investment Research
JBL Still Faces Customer and Demand Risks
Jabil’s AI growth is becoming more concentrated in large programs. Management expects six Intelligent Infrastructure customers to generate more than $1 billion in revenues each during fiscal 2027, increasing the importance of customer retention, capacity utilization and program execution.
Demand is also uneven outside infrastructure. Connected Living revenues are expected to decline 15% in fiscal 2027, while Intelligent Devices and Robotics revenues are projected to fall 2% to $5.3 billion. Geopolitical uncertainty, component availability, competitive pricing and changing customer sourcing decisions remain additional risks.
Jabil’s Strong Signals Reinforce the Setup
JBL’s growth outlook and improving profitability support the case for accepting a valuation above its historical median, although the premium leaves less room for execution setbacks. The current setup favors investors who are comfortable paying more than Jabil’s typical multiple for a faster earnings-growth profile.
The stock currently carries a Zacks Rank #1 (Strong Buy) and a VGM Score of A. Its Momentum Score of A is complemented by a Value Score of B and a Growth Score of B. The Zacks Consensus Estimate for fiscal 2027 earnings has risen 6.1% over the past four weeks to $17.61 per share.
The Zacks Rank and favorable Style Scores point to a constructive near-term profile, with estimate revisions, momentum, growth and value characteristics working in Jabil’s favor. Still, the premium to its five-year median valuation keeps the investment decision balanced rather than automatic. You can see the complete list of today’s Zacks #1 Rank stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Jabil, Inc. (JBL): Free Stock Analysis Report
Plexus Corp. (PLXS): Free Stock Analysis Report
Celestica, Inc. (CLS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).