

QXO, Inc. QXO is advancing its ambitious growth strategy following the completion of its approximately $15 billion acquisition of TopBuild Corp. on July 1, 2026. The transaction significantly expands its building products distribution and installation capabilities, positioning it as North America's second-largest publicly traded building products distributor. Management aims to more than double EBITDA by 2030, supported by greater scale, operational efficiencies and technology investments.
TopBuild's extensive insulation distribution and installation operations strengthen QXO's presence across residential, commercial and industrial construction markets. Its capabilities complement QXO's existing roofing, waterproofing and building materials businesses, creating opportunities for cross-selling, stronger customer relationships and improved operating efficiencies. The broader footprint could also enhance purchasing power and streamline distribution, supporting long-term earnings growth.
Importantly, QXO's technology-driven transformation provides another avenue for EBITDA expansion. Management has begun upgrading systems across the company, with investments in artificial intelligence, IT infrastructure and operational modernization. These initiatives could improve productivity, reduce operating costs and strengthen margins as the combined businesses scale.
However, achieving the 2030 target will require disciplined integration and stronger profitability. Second-quarter adjusted EBITDA reached $272 million, but adjusted EBITDA margin declined to 8.4% from 10.7% a year earlier. These results preceded TopBuild's consolidation. Elevated debt obligations, integration complexity and uneven construction demand could also constrain near-term progress.
Nonetheless, TopBuild's expanded scale, diversification benefits and potential operational synergies provide QXO with a stronger foundation to pursue its ambitious 2030 EBITDA objective.
Industry Peers Target Long-Term Margin Expansion
QXO's $15 billion TopBuild acquisition strengthens its scale and operational capabilities as it targets more than doubling EBITDA by 2030. Distribution peers Fastenal Company FAST and SiteOne Landscape Supply, Inc. SITE are similarly emphasizing technology, operating efficiencies and strategic expansion to drive profitability.
Fastenal is leveraging digital investments, key account growth and operational efficiencies to strengthen profitability and support long-term EBITDA growth. In the second quarter of 2026, daily sales increased 14.7%, supported by customer wins and market-share gains. Its digital footprint accounted for 61.6% of sales, while Fastenal Managed Inventory represented 44.6%. Strong sales growth, SG&A leverage and cost discipline helped improve operating margin despite inflationary pressures. These efficiencies could support further EBITDA expansion as the company scales its operations.
SiteOne is pursuing EBITDA expansion through acquisitions, digital initiatives and productivity improvements. Second-quarter adjusted EBITDA increased 5% to $237.2 million, with margins holding steady at 15.5%. The company has completed 108 acquisitions since 2014 and expects additional deals in 2026. Digital sales growth exceeding 50% year to date and distribution efficiencies further support its long-term margin expansion strategy.
Both companies highlight how scale, technology and disciplined execution can strengthen profitability, reinforcing QXO's strategy for achieving its 2030 EBITDA target.
QXO’s Price Performance, Valuation & Estimates
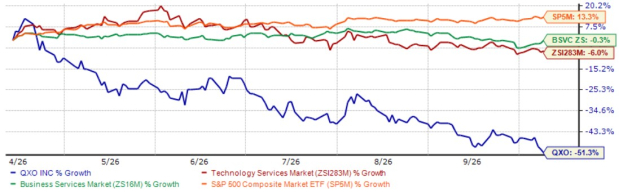
Shares of QXO have declined 51.3% in the past six months, underperforming the Zacks Technology Services industry, the broader Business Services sector and the S&P 500 Index.
QXO Stock’s Six-Month Price Performance
Image Source: Zacks Investment Research
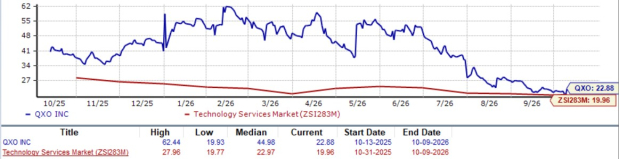
QXO stock is currently trading at a premium compared with its industry peers, with a forward 12-month price-to-earnings (P/E) ratio of 22.88, as shown in the chart below.
QXO’s P/E Ratio (Forward 12-Month) vs. Industry
Image Source: Zacks Investment Research
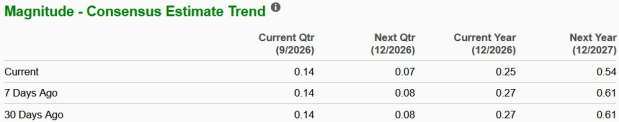
QXO’s earnings estimates for 2026 and 2027 have been revised downward over the past seven days to 25 cents and 54 cents per share, respectively. The revised estimates indicate a year-over-year earnings decline of 26.5% in 2026, followed by a sharp rebound of 116% in 2027.
EPS Trend of QXO Stock
Image Source: Zacks Investment Research
QXO stock currently carries a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
QXO, Inc. (QXO): Free Stock Analysis Report
Fastenal Company (FAST): Free Stock Analysis Report
SiteOne Landscape Supply, Inc. (SITE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).