

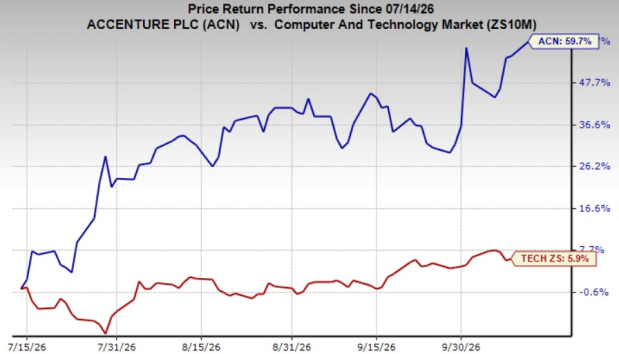
Accenture ACN shares have surged 60% over the past three months, significantly outperforming the industry's 6% growth. The impressive rally reflects optimism surrounding the company's expanding artificial intelligence (AI) capabilities, strong enterprise relationships and digital transformation opportunities. However, following such substantial appreciation, investors must evaluate whether its earnings outlook and business fundamentals justify further upside.
Accenture's diversified service portfolio, strategic acquisitions and consistent cash generation support its long-term prospects. Nevertheless, restrained discretionary spending, pricing competition and modest organic revenue growth expectations suggest that investors should approach the stock cautiously.
ACN's Earnings Outlook Signals Gradual Improvement
The Zacks Consensus Estimate for Accenture's first-quarter fiscal 2027 earnings stands at $3.89 per share, indicating a 1.3% year-over-year decline. Revenues are projected at $19.35 billion, indicating 3.2% growth.
For fiscal 2027, the consensus earnings estimate of $14.68 per share suggests 5.1% year-over-year growth. Revenues are expected to increase 4.2% to $77.33 billion.
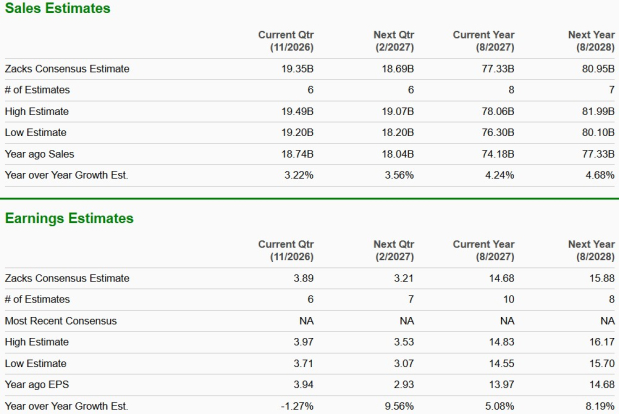
The outlook strengthens for fiscal 2028, with earnings projected to rise 8.2% to $15.88 per share and revenues anticipated to grow 4.7% to $80.95 billion. These estimates indicate steady business expansion, although the earnings trajectory may not fully support expectations of rapid growth following the stock's sharp rally.
Enterprise AI Adoption Expands ACN's Opportunities
Growing enterprise investment in AI, cloud modernization and data infrastructure continues to create opportunities for Accenture. Businesses increasingly require technology integration, process redesign and specialized expertise to deploy AI applications across operations.
In fiscal 2026, more than 400 clients initiated advanced AI engagements with Accenture. Revenues from its eight emerging AI and data partners more than doubled, while bookings more than tripled year over year.
The company's workforce of nearly 110,000 AI and data professionals strengthens its ability to execute complex transformation programs. Its extensive technology partnerships also support broader adoption of AI-driven solutions.
As organizations move toward enterprise-wide AI implementation, demand for consulting, integration and managed services could sustain long-term revenue opportunities.
Acquisitions and Strong Bookings Reinforce Growth Prospects
Accenture continues to expand its capabilities through acquisitions targeting attractive technology markets. During fiscal 2026, the company invested $4.9 billion across 17 acquisitions.
The acquisitions of Ookla and Whalar strengthened its network intelligence and digital marketing offerings, respectively. Additional cybersecurity investments broadened its presence in industrial and operational technology security.
Meanwhile, fiscal 2026 bookings reached $84.5 billion, including 141 quarterly client bookings exceeding $100 million. These contracts provide opportunities for future revenue generation as large transformation engagements progress.
Management expects fiscal 2027 revenue growth of 3-6% in local currency, including a 2-2.5% contribution from acquisitions. However, this guidance also highlights the importance of improving organic demand to sustain growth beyond acquisition-driven expansion.
Cash Flow Supports Shareholder Returns
Accenture's strong financial position provides flexibility to pursue investments while rewarding shareholders. Fiscal 2026 free cash flow totaled $11.6 billion, increasing 7% year over year.
Adjusted operating margin expanded 20 basis points to 15.8%, reflecting operational discipline despite substantial technology and workforce investments.
For fiscal 2027, management expects free cash flow of $11-$11.8 billion and operating margin of 15.9-16.1%. Continued dividends and share repurchases should support shareholder returns.
However, elevated acquisition spending and integration requirements could moderate near-term cash flow growth.
Spending Caution and Pricing Pressures Cloud the Outlook
Despite its favorable positioning, Accenture faces persistent challenges. Discretionary technology spending remains subdued as enterprises prioritize essential modernization projects over optional initiatives.
Intense competition is also creating pricing pressure across several service categories. Meanwhile, AI-driven productivity improvements could reduce traditional labor requirements and influence contract economics.
These factors may constrain organic revenue acceleration and limit margin expansion. Following the stock's substantial appreciation, slower-than-expected earnings growth could increase vulnerability to a valuation correction.
How Do ACN's Industry Peers Compare?
International Business Machines IBM competes in enterprise consulting, hybrid cloud and AI implementation. IBM integrated technology portfolio helps organizations modernize infrastructure, automate workflows and improve operational efficiency.
IBM benefits from combining consulting services with proprietary software capabilities, supporting enterprise transformation opportunities. However, cautious technology budgets and competitive pressures could affect consulting growth.
Cognizant Technology Solutions CTSH offers digital engineering, cloud transformation, consulting and AI-enabled business services. CTSH’s enterprise technology capabilities position it to capture demand for application modernization and intelligent automation.
CTSH continues to expand its AI-focused offerings to improve service delivery and client productivity. Nevertheless, discretionary spending constraints and pricing competition remain important risks to its growth outlook.
Verdict: Hold ACN Stock After the Rally
Accenture remains well positioned to benefit from enterprise AI adoption, technology modernization and growing demand for integrated digital services. Its diversified client base, expanding capabilities and consistent cash generation strengthen its long-term investment appeal. However, the recent share-price rally has raised expectations at a time when organic growth remains moderate and discretionary spending continues to face uncertainty. Competitive pricing and acquisition-related execution risks could further restrict near-term returns. While existing investors have reasons to maintain exposure to the company's growth opportunities, fresh investments appear less compelling following the sharp appreciation. Therefore, holding Accenture stock is the more prudent strategy.
Accenture carries a Zacks Rank #3 (Hold) at present. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Accenture PLC (ACN): Free Stock Analysis Report
International Business Machines Corporation (IBM): Free Stock Analysis Report
Cognizant Technology Solutions Corporation (CTSH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).