

Vertiv VRT and Amphenol APH are major players in the AI and data center infrastructure market, supplying critical power, cooling and connectivity solutions used in hyperscale and enterprise data centers. While Vertiv delivers critical power and cooling solutions for data centers fueling the AI boom, Amphenol provides the high-performance connectors and interconnect systems critical to data center operations.
So, VRT or APH — Which of these AI Infrastructure stocks has the greater upside potential? Let’s find out.
The Case for VRT
Vertiv is benefiting from strong demand for AI infrastructure as hyperscalers, colocation providers, neocloud operators and enterprises continue to expand data-center capacity. The company’s global pipeline remains robust across its core markets, particularly in the Americas and APAC regions. In the second quarter of 2026, net sales increased 24% year over year, with the Americas and APAC both growing 29%. EMEA also returned to positive net sales growth.
Acquisitions have further strengthened Vertiv’s data center portfolio. The recent acquisitions of ThermoKey and Strategic Thermal Labs have expanded Vertiv’s capabilities in heat rejection and high-density thermal management, respectively. These moves enhance Vertiv’s ability to offer comprehensive solutions across the thermal spectrum from heat rejection to direct-to-chip cooling. In the second quarter of 2026, acquisitions contributed 5% to revenues.
Vertiv is benefiting from significant margin gains. In the second quarter of 2026, the company reported an adjusted operating margin of 22.6%, up 410 basis points year over year and well above its previous guidance. This margin expansion was driven by disciplined operational execution, productivity improvements and favorable price-cost dynamics, partially offset by tariff impacts. The company expects margin momentum to continue in the second half of 2026. For the third quarter of 2026, adjusted operating profit is projected to be between $898 million and $938 million, with an adjusted operating margin of 24% to 25%, supported by organic growth, operating leverage and productivity.
Vertiv is demonstrating strong momentum and confidence in its trajectory as a leader in AI and digital infrastructure. For the third quarter of 2026, Vertiv expects net sales in the range of $3.65 billion to $3.85 billion.
The Case for APH Stock
Amphenol is benefiting from robust demand for AI-driven connectivity solutions, expanding investments in data center infrastructure and its diversified end-market exposure.
The company’s strong position in high-speed copper, fiber-optic and power interconnect solutions is helping it capitalize on accelerating investments in AI data centers and next-generation computing infrastructure. IT datacom has become APH’s largest end market, which accounted for 43% of second-quarter 2026 sales. Sales in this market surged 89% year over year and 22% sequentially, driven by accelerating demand for products used in AI applications. Amphenol expects IT datacom revenues to grow in the mid-teens sequentially in the third quarter of 2026, supported by accelerating AI data center investments and strengthening enterprise and cloud demand.
Amphenol’s strengthening position in optical connectivity has been noteworthy. The acquisition of CommScope’s Connectivity and Cable Solutions business has expanded its advanced fiber-optic interconnect capabilities and customer relationships. Amphenol now expects CommScope to contribute $4.6 billion in revenues and 30 cents in earnings per share accretion in 2026, up from its previous expectations of $4.1 billion and 15 cents, respectively. This reflects improving operational efficiency and rising demand for AI-related products.
Amphenol’s outlook for the third quarter of 2026 remains strong, driven by accelerating AI infrastructure investments, robust demand for high-speed connectivity solutions and broad-based strength across diversified end markets. The company expects revenues between $9.3 billion and $9.4 billion, representing year-over-year growth of 50-52%.
Price Performance and Valuation of VRT and APH
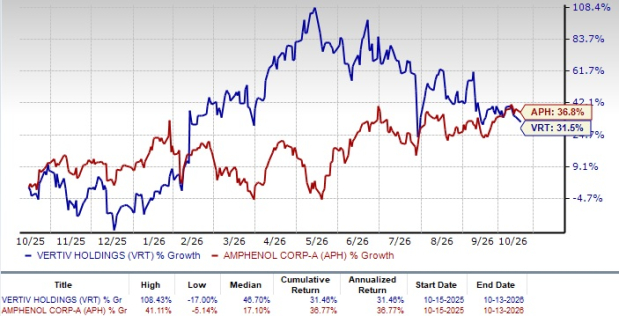
In the trailing 12-month period, Vertiv and Amphenol shares have rallied 31.5% and 36.8%, respectively. The outperformance of Amphenol can be attributed to its diversified business model. Its strong portfolio of solutions, including high-technology interconnect products, is a key catalyst. Acquisitions are also helping Amphenol expand its position across a broad array of technologies and markets.
Despite VRT’s expanding portfolio, timing shifts in large, multiphase project execution and temporary supply-chain congestion, particularly within complex infrastructure deployments, remain a headwind. Tariffs and trade-policy changes continue to create cost and logistics volatility.
VRT and APH Stock Performance
Image Source: Zacks Investment Research
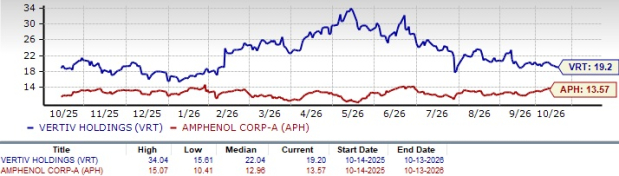
Valuation-wise, Vertiv and Amphenol shares are currently overvalued, as suggested by a Value Score of D.
In terms of trailing 12-month Price/Book, Vertiv shares are trading at 19.2X, higher than Amphenol’s 13.57X.
VRT and APH Valuation
Image Source: Zacks Investment Research
How Do Earnings Estimates Compare for VRT & APH?
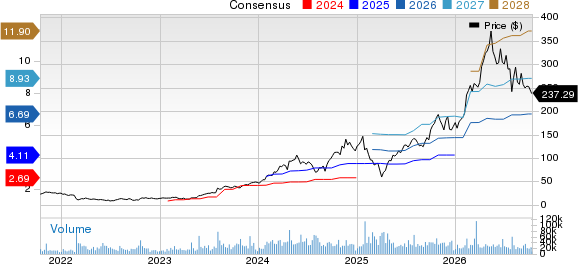
The Zacks Consensus Estimate for Vertiv’s 2026 earnings is currently pegged at $6.69 per share, which has been unchanged over the past 30 days. This represents a 59.29% year-over-year rise.
Vertiv Holdings Co. Price and Consensus
Vertiv Holdings Co. price-consensus-chart | Vertiv Holdings Co. Quote
The Zacks Consensus Estimate for Amphenol’s 2026 earnings is currently pegged at $2.66 per share, which has been unchanged over the past 30 days. This represents a 59.28% year-over-year rise.
Amphenol Corporation Price and Consensus
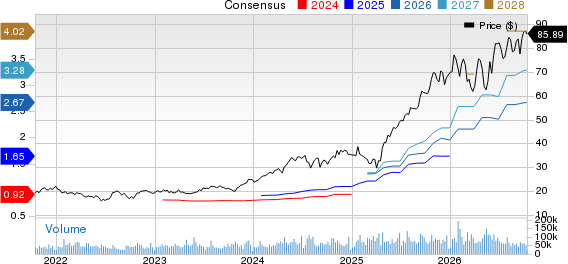
Amphenol Corporation price-consensus-chart | Amphenol Corporation Quote
Conclusion
While both Vertiv and Amphenol stand to benefit from the AI infrastructure boom, Amphenol’s strong AI-driven demand, diversified end-market exposure and strategic acquisitions suggest it may offer greater upside potential in the near term.
Vertiv’s strong AI infrastructure demand and expanding margins remain noteworthy. However, near-term execution risks and supply-chain volatility remain headwinds. Stiff competition also remains a concern.
Both Vertiv and Amphenol carry a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Amphenol Corporation (APH): Free Stock Analysis Report
Vertiv Holdings Co. (VRT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).