

General Mills, Inc. GIS shares have fallen about 13% in the past month, reflecting a fiscal 2027 setup still defined by weak demand and earnings pressure. The lower price raises the question of whether improving execution can create enough support for investors.
There are encouraging signs in U.S. retail and premium pet food, while productivity actions could help margins over time. Yet dog food remains weak, earnings are expected to contract and demand visibility is limited.
Why GIS Shares Face Persistent Pressure
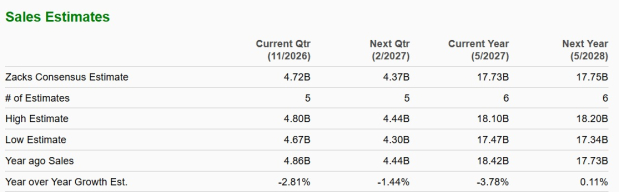
General Mills expects fiscal 2027 organic net sales to range from a 1.5% decline to 0.5% growth. Adjusted operating profit is projected to fall 8%-13% in constant currency, while adjusted earnings are expected at $3-$3.20 per share.
Image Source: Zacks Investment Research
The company expects category growth to remain below historical trends, and unfavorable comparisons are adding pressure. The difficult backdrop is broader than GIS. The Kraft Heinz Company KHC expects 2026 organic net sales to decline 0.5%-2%, while The Campbell's Company CPB guides fiscal 2027 organic net sales down 2%-4%.
General Mills Shows Early Retail Improvement
U.S. retail sales declined 2.3% in the first quarter of fiscal 2027, improving from a 4.1% decline in the second half of fiscal 2026. Most priority categories also posted better dollar-share trends, while household penetration and distribution increased.
Pillsbury retail sales stabilized after eight straight quarters of declines as General Mills renovated 70% of its canned dough portfolio. With base-price adjustments completed, management is focusing on innovation, renovation and favorable mix to support better volume trends.
GIS Pet Weakness Remains a Key Risk
Pet performance remains uneven. Tiki Cat delivered double-digit retail sales growth in the fiscal first quarter, while Blue Tastefuls grew at a mid-single-digit rate. Cat feeding has now produced at least mid-single-digit retail sales growth for eight consecutive quarters.
Dog food moved in the opposite direction, falling at a high-single-digit rate. Blue Buffalo Wilderness remains the most challenged dry dog food business, and management expects its broader product, packaging, positioning and value changes to take time.
General Mills’ Valuation Reflects Lower Expectations
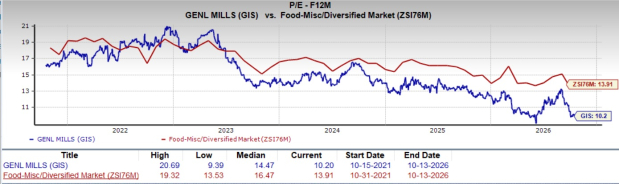
GIS trades at 10.2X forward 12-month earnings, below the Zacks sub-industry’s 13.9X and its own five-year median of 14.5X. The discount suggests investors already reflect a meaningful amount of operating pressure in the share price.
Image Source: Zacks Investment Research
That gap does not remove execution risk. General Mills is prioritizing leverage reduction, while first-quarter adjusted operating profit fell 11% in constant currency. Its $3 billion cumulative cost-savings target through fiscal 2030 could support future earnings, but demand recovery remains important.
GIS Signals Favor Value Over Growth
The sell-off has made GIS less expensive, but the investment case still depends on sustained retail improvement, a better dog-food trajectory and evidence that productivity can offset inflation and softer volumes. Valuation alone does not establish a durable earnings recovery.
GIS currently carries a Zacks Rank #3 (Hold), with a Value Score of B, Growth Score of D, Momentum Score of C and VGM Score of C. That mix is consistent with stronger value characteristics than growth characteristics, while the middling Momentum and VGM readings favor patience until operating progress becomes clearer. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
General Mills, Inc. (GIS): Free Stock Analysis Report
The Campbell's Company (CPB): Free Stock Analysis Report
Kraft Heinz Company (KHC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).