

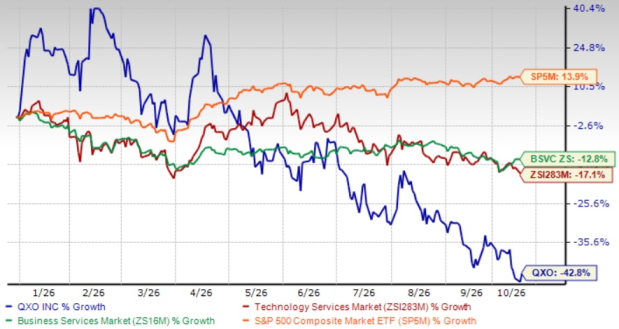
Shares of QXO, Inc. QXO have lost 42.8% over the year-to-date (“YTD”) period compared with the Zacks Technology Services industry's decline of 17.1%. The stock has also lagged the Zacks Business Services sector and the S&P 500 Index, as evidenced by the chart below.
QXO Price Performance (YTD)
Image Source: Zacks Investment Research
QXO’s higher debt levels, rising operating expenses and substantial working capital needs are weighing on profitability and cash generation. Increased interest expense and integration costs are adding pressure, while cash outflows from operating activities limit financial flexibility. The company’s ability to generate sufficient efficiencies from expanded operations remains a key concern, as delayed cost savings and elevated debt levels weigh on its earnings potential and financial flexibility.
Let us examine the key factors weighing on QXO’s prospects.
Higher Debt Levels Increase QXO’s Interest Burden
Acquisition-led expansion has increased QXO’s debt obligations, adding pressure on earnings as it integrates the enlarged operations. Long-term debt rose to $6.03 billion as of June 30, 2026, from $3.06 billion at the end of 2025. Net interest expense increased to $38 million in the second quarter of 2026 from $30 million a year earlier, while first-half interest expense reached $69 million, compared with net interest income of $26 million in the prior-year period. Higher financing costs add to the challenge of translating operating improvements into stronger bottom-line results.
Integration Costs Add to QXO’s Profitability Challenges
QXO’s expanding operating structure brings additional costs that may take time to offset through efficiencies. In the second quarter of 2026, selling, general and administrative expenses increased 42% year over year to $649 million, while depreciation rose 107% to $56 million and amortization climbed to $140 million from $80 million. The company also incurred $24 million in transformation costs during the quarter as it worked to simplify and optimize operations. These expenses add to the challenge of improving profitability as QXO integrates acquired businesses and invests in its operating infrastructure.
Working Capital Needs Continue to Pressure Cash Generation
QXO’s distribution operations require significant investment in inventory and customer receivables, making cash generation sensitive to purchasing and collection cycles. Net cash used in operating activities reached $146 million in the first half of 2026, compared with $138 million in the year-ago period. The company attributed the increase primarily to the Beacon and Kodiak acquisitions and the seasonal timing of inventory purchases and customer collections. Higher working capital requirements may limit internally generated cash available for debt reduction and other priorities, particularly as the business expands.
Acquisition Benefits Depend on Successful Integration
QXO’s acquisition-led growth strategy depends on integrating acquired businesses and converting greater scale into operating efficiencies. The company is combining processes, employees, technology and operations following recent acquisitions, while also working to modernize its systems. However, the expected benefits of the Beacon, Kodiak and TopBuild acquisitions may take longer to materialize or may not be fully realized. Delays in integration, higher-than-expected costs or disruption to customer and supplier relationships may weigh on operating performance and limit the returns from these transactions.
QXO Stock Trades at a Premium
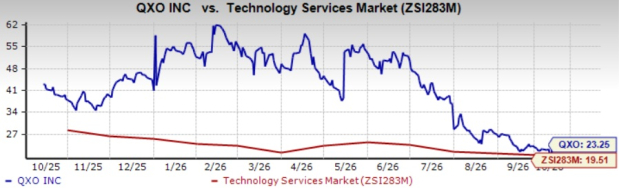
QXO stock is currently trading at a premium compared with its industry peers, with a forward 12-month price-to-earnings (P/E) ratio of 23.25, as shown in the chart below.
QXO Valuation (P/E F12M)
Image Source: Zacks Investment Research
QXO’s Earnings Estimates Revision
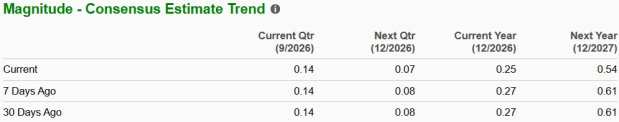
QXO’s earnings estimates for 2026 and 2027 have moved downward over the past 30 days to 25 cents and 54 cents per share, respectively. The revised estimates imply a year-over-year decline of 26.5% in 2026 and growth of 116% in 2027. The sharp difference in expected growth reflects an uneven earnings trajectory, with near-term profitability under pressure and stronger growth anticipated in 2027. The pace of operating improvements and the realization of acquisition-related efficiencies will be important in determining whether QXO meets these expectations.
EPS Trend of QXO Stock
Image Source: Zacks Investment Research
QXO & Its Key Distribution Peers
QXO competes with W.W. Grainger, Inc. GWW, SiteOne Landscape Supply, Inc. SITE and Fastenal Company FAST across the broader distribution market, although each company serves different product categories and customer needs.
W.W. Grainger operates a broad maintenance, repair and operating products distribution business, serving customers across manufacturing, government, contractors and other industrial markets. Its High-Touch and Endless Assortment segments provide multiple channels for reaching customers, while investments in digital capabilities and distribution infrastructure support W.W. Grainger’s service model. However, changes in product mix, freight expenses and inflationary pressures can affect margins.
SiteOne Landscape Supply specializes in wholesale distribution of landscaping supplies, including irrigation, nursery, hardscapes and outdoor lighting products. Its nationwide branch network and acquisition strategy support product expansion and market-share gains in a fragmented industry. However, weaker demand in new residential construction and repair-and-upgrade markets has pressured SiteOne Landscape Supply’s organic sales volumes, while higher fuel and operating costs weigh on expenses.
Fastenal focuses on industrial and construction supplies, including fasteners, supported by its distribution network, digital sales channels and Fastenal Managed Inventory services. Its focus on larger customer accounts and technology-enabled inventory solutions supports customer retention and operating efficiency. However, price-cost pressures, customer mix and transportation costs can weigh on gross margins, while investments in distribution capacity, automation and technology require capital spending.
How to Play QXO Stock?
QXO’s expanded operations and recent acquisitions provide opportunities for long-term growth, but rising costs and integration challenges remain key concerns. Despite the company’s efforts to expand its business, higher debt levels, weak cash generation and downward earnings estimate revisions for 2026 raise red flags, making QXO stock a risky bet for now. With a Zacks Rank #4 (Sell), it is prudent for investors to exit the stock and consider re-evaluating it once the company demonstrates more consistent profitability and stronger cash generation.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
QXO, Inc. (QXO): Free Stock Analysis Report
Fastenal Company (FAST): Free Stock Analysis Report
W.W. Grainger, Inc. (GWW): Free Stock Analysis Report
SiteOne Landscape Supply, Inc. (SITE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).