

Technology-driven insurance provider Neptune Insurance Holdings Inc. NP is set to report third-quarter 2026 results on Oct. 20, after the closing bell. The Zacks Consensus Estimate for the to-be-reported quarter’s earnings is currently pegged at 16 cents per shareon revenues of $54.97 million.
The third-quarter earnings estimate has remained stable over the past 60 days. The bottom-line projection indicates a year-over-year jump of 45.5%. The Zacks Consensus Estimate for quarterly revenues implies year-over-year growth of 23.9%.
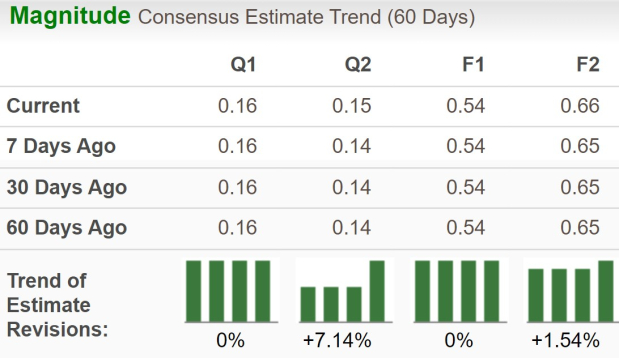
For full-year 2026, the Zacks Consensus Estimate for Neptune’s revenues is pegged at $201.15 million, implying an increase of 26.1% year over year. Also, the consensus mark for the current year EPS is pegged at 54 cents, signaling a rise of around 31.7% on a year-over-year basis.
NP’s earnings beat the consensus estimate in two of the past four quarters, met once and missed on the other occasion, with the average surprise being 2.2%.
Neptune Insurance Price and EPS Surprise
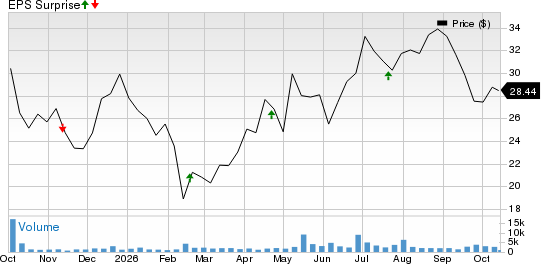
Neptune Insurance Holdings Inc. price-eps-surprise | Neptune Insurance Holdings Inc. Quote
Q3 Earnings Whispers for NP
Our proven model predicts a likely earnings beat for the company this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That is precisely the case here.
Neptune has an Earnings ESP of +1.82% and carries a Zacks Rank #2 at present. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
What’s Shaping NP’s Q3 Results?
Neptune is expected to post solid third-quarter growth, supported by an increase in policies in force, higher revenue per employee and a larger workforce. The Zacks Consensus Estimate projects commission income to rise 23.6% year over year to $41.93 million, while fee income is expected to grow 22.4% to $12.79 million.
Growth in policies in force is another positive. The period-end figure is expected to reach 323,300, up 2.3% from the previous quarter. This is likely to lift premium in force to $432.7 million, a 3.3% sequential increase.
Neptune is also expected to see better workforce productivity, with revenue per employee projected to increase 15.1% year over year. The average number of employees is expected to grow 13.8% from the year-ago quarter, further supporting business expansion.
Together, these trends could help Neptune deliver year-over-year growth and beat earnings expectations. However, higher operating expenses, driven by increased commissions and general and administrative costs, could partly offset some of the gains.
Other Stocks That Warrant a Look
Here are some other companies worth considering from the broader insurance space, as our model shows that these, too, have the right combination of elements to beat on earnings this time around:
MetLife, Inc. MET has an Earnings ESP of +1.90% and a Zacks Rank of 2. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for MetLife’s bottom line for the to-be-reported quarter is pegged at $2.65 per share, up 13.3% from a year ago. The consensus estimate for MET’s revenues is pegged at $20.07 billion, indicating 12.1% year-over-year growth.
Prudential Financial, Inc. PRU has an Earnings ESP of +0.39% and a Zacks Rank of 3.
The Zacks Consensus Estimate for Prudential Financial’s bottom line for the to-be-reported quarter is pegged at $3.47 per share, which witnessed six upward estimate revisions over the past 60 days against one downward movement. The consensus estimate for PRU’s revenues is pegged at $14.60 billion.
Willis Towers Watson Public Limited Company WTW has an Earnings ESP of +0.52% and a Zacks Rank #3.
The Zacks Consensus Estimate for Willis Towers’ bottom line for the to-be-reported quarter is pegged at $3.60 per share, which indicates 17.3% year-over-year growth. The consensus estimate for WTW’s revenues is pegged at $2.48 billion, an 8.3% increase from a year ago.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Neptune Insurance Holdings Inc. (NP): Free Stock Analysis Report
MetLife, Inc. (MET): Free Stock Analysis Report
Prudential Financial, Inc. (PRU): Free Stock Analysis Report
Willis Towers Watson Public Limited Company (WTW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).