

The Procter & Gamble Company PG, also known as P&G, is set to report first-quarter fiscal 2027 results on Oct. 22, before the opening bell. The company is expected to have witnessed year-over-year sales growth in the to-be-reported quarter.
The Zacks Consensus Estimate for fiscal first-quarter revenues is pegged at $22.7 billion, indicating a 1.4% rise from the prior-year quarter’s reported figure. The consensus mark for PG’s earnings is pegged at $1.89 per share, indicating a decline of 5% from the year-ago quarter’s actual. The consensus mark for earnings has been unchanged in the past 30 days.
PG has a trailing four-quarter earnings surprise of 2.2%, on average. The company delivered an earnings surprise of 1.4% in the fourth quarter of fiscal 2026.
Procter & Gamble Company (The) Price and EPS Surprise
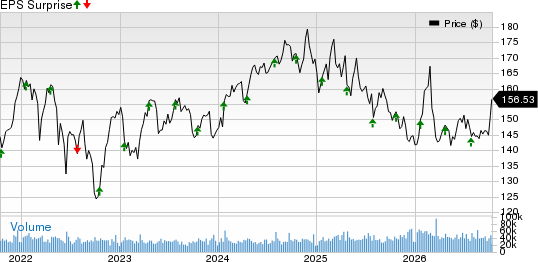
Procter & Gamble Company (The) price-eps-surprise | Procter & Gamble Company (The) Quote
PG’s Q1 Earnings Whispers
Our proven model does not conclusively predict an earnings beat for Procter & Gamble this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. But that is not the case here. You can uncover the best stocks before they are reported with our Earnings ESP Filter.
Procter & Gamble currently has an Earnings ESP of -0.46% and a Zacks Rank #3.
Key Trends to Watch Ahead of PG's Q1 Earnings
Procter & Gamble’s first-quarter fiscal 2027 results are expected to reflect persistent input cost inflation, cautious consumer spending and ongoing investments in product innovation and brand-building initiatives. Higher raw material, energy and transportation expenses, alongside supply-chain-related surcharges, are likely to have weighed on profitability.
On the last reported quarter’s earnings call, management anticipated these cost pressures to be concentrated in the first half of fiscal 2027, projecting a decline of 5% or more in fiscal first-quarter core earnings per share.
We expect the core cost of products sold to increase 4.1% year over year in first-quarter fiscal 2027. Our model predicts the core gross margin to contract 120 bps year over year to 50.3%.
On the revenue front, Procter & Gamble is likely to have benefited from improving consumption trends, targeted pricing interventions and innovation-led demand. Momentum in Greater China, particularly across Baby Care, Beauty and Fabric Care, alongside sustained growth in enterprise markets, is expected to have supported organic sales. However, sluggish category growth in North America and Europe, heightened promotional activity and retailer inventory fluctuations may have constrained the overall sales performance.
Our model predicts year-over-year organic sales growth of 0.5% for PG in the fiscal first quarter. Our model estimates organic sales growth of 4% for Beauty and 1% for the Fabric & Home Care segment, with flat organic sales for the Grooming segment. However, organic sales for the Health Care, and Baby, Feminine & Family Care segments are expected to decline 1% and 2%, respectively, in the fiscal first quarter.
The company’s integrated strategy, built on innovation, market expansion and productivity, has enabled it to adapt to shifting consumer dynamics and maintain competitiveness.
Procter & Gamble's focus on strengthening core brands, expanding premium offerings and improving consumer value propositions is expected to have aided market-share recovery. Innovations such as Tide evo and upgraded Tide liquid formulations, coupled with productivity savings and disciplined marketing investments, may have provided some support to operating performance despite elevated costs.
Procter & Gamble’s Price Performance & Valuation
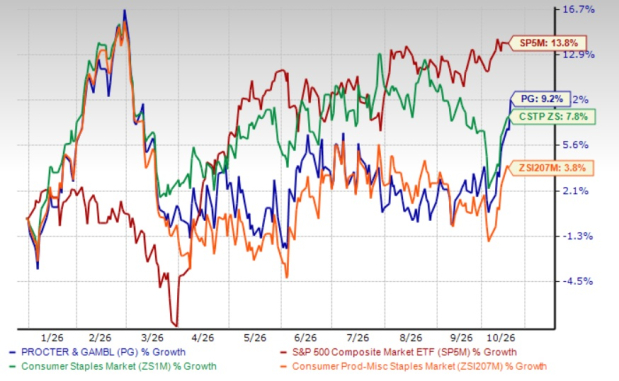
PG shares have gained 9.2% in the year-to-date period compared with the industry and Consumer Staples sector’s growth of 3.8% and 7.8%, respectively. However, the stock has underperformed the S&P 500’s return of 13.8%.
PG’s YTD Performance
Image Source: Zacks Investment Research
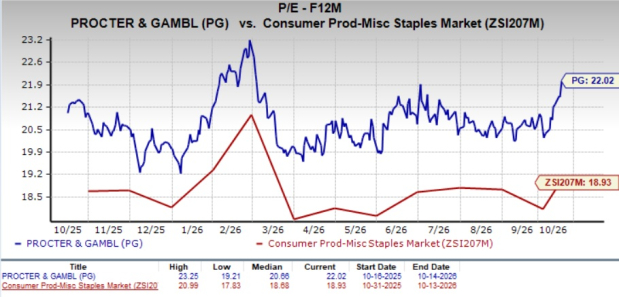
From the valuation standpoint, Procter & Gamble is trading at a forward 12-month P/E multiple of 22.02X, exceeding the industry and the S&P 500’s average of 18.93X and 19.81X, respectively. PG’s valuation appears pricey relative to the industry.
Image Source: Zacks Investment Research
Stocks With the Favorable Combination
Here are some companies that, according to our model, have the right combination of elements to beat on earnings this reporting cycle.
e.l.f. Beauty ELF currently has an Earnings ESP of +6.10% and sports a Zacks Rank #1. The company is likely to register growth in the top line when it reports second-quarter fiscal 2027 numbers. The consensus mark for revenues is pegged at $469.2 million, which indicates a rise of 36.4% from the figure reported in the year-ago quarter. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for ELF’s quarterly earnings per share of 59 cents implies a decline of 13.2% from the year-ago quarter’s actual. The consensus mark has moved down 3.3% in the past 30 days. ELF has a trailing four-quarter earnings surprise of 61.5%, on average.
Purple Innovation PRPL currently has an Earnings ESP of +32.92% and a Zacks Rank #2. The company is likely to register growth in the bottom line when it reports third-quarter 2026 numbers. The consensus mark for revenues is pegged at $117.4 million, which indicates a decline of 1.2% from the figure reported in the year-ago quarter.
The Zacks Consensus Estimate for Purple Innovation’s quarterly loss per share of $1.07 implies an improvement from a loss per share of $2.00 incurred in the year-ago quarter. The consensus mark for loss per share has narrowed in the past 30 days. PRPL has a trailing four-quarter earnings surprise of 21.3%, on average.
Archer Daniels Midland Company ADM currently has an Earnings ESP of +18.48% and a Zacks Rank #3. The company is likely to register growth in the top and bottom lines when it reports third-quarter 2026 numbers. The Zacks Consensus Estimate for ADM’s quarterly EPS is pegged at $1.44, up 56.5% from the year-ago period. The consensus mark for EPS has moved up 3.6% in the past seven days.
The consensus estimate for ADM’s quarterly revenues is pegged at $22.7 billion, which implies growth of 11.3% from the prior-year quarter’s actual. Archer Daniels has a trailing four-quarter earnings surprise of 11.3%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Procter & Gamble Company (The) (PG): Free Stock Analysis Report
Archer Daniels Midland Company (ADM): Free Stock Analysis Report
e.l.f. Beauty (ELF): Free Stock Analysis Report
PURPLE INNOVATION, INC. (PRPL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).