

Lockheed Martin Corporation LMT reported third-quarter 2026 adjusted earnings of $7.97 per share, which beat the Zacks Consensus Estimate of $7.49 by 6.4%. The bottom line increased 14.7% from the year-ago quarter's reported figure of $6.95.
Operational Highlights of Lockheed
Net sales were $20.71 billion, which beat the Zacks Consensus Estimate of $20.44 billion by 1.4%. The top line inched up 11.3% from $18.61 billion reported in the year-ago quarter.
The year-over-year improvement was driven by higher sales growth registered by LMT’s business segments.
Lockheed Martin Corporation Price, Consensus and EPS Surprise
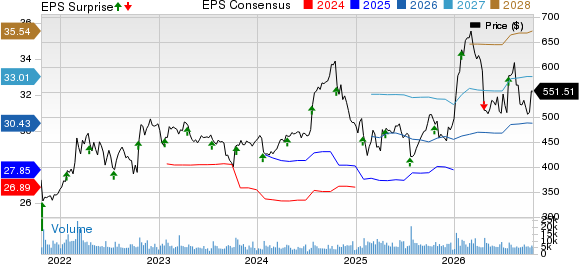
Lockheed Martin Corporation price-consensus-eps-surprise-chart | Lockheed Martin Corporation Quote
LMT’s Backlog
LMT’s backlog as of Sept. 27, 2026, was $291.98 billion compared with $193.62 billion as of Dec. 31, 2025.
The Aeronautics segment accounted for $57.33 billion of the total backlog amount, while the Missiles and Fire Control segment contributed $142.52 billion. The Rotary and Mission Systems segment contributed $49.44 billion, while the Space unit accounted for $42.70 billion.
Lockheed’s Segmental Performance
Aeronautics: Sales increased 13% year over year to $8.21 billion. The increase was primarily driven by higher sales from the F-35 program, reflecting higher volume on production and sustainment contracts, as well as increased sales from the C-130 program.
The segment reported an operating profit of $743 million compared with $682 million in the year-ago quarter. The operating margin contracted 40 basis points (bps) to 9.0%.
Missiles and Fire Control: Quarterly sales improved 24% year over year to $4.50 billion. This was primarily attributable to higher sales from integrated air and missile defense programs, including PAC-3 and THAAD, as well as tactical and strike missile programs, including GMLRS and PrSM, driven by production ramps.
The segment’s operating profit increased to $631 million from $510 million in the prior-year quarter. The operating margin contracted 10 bps to 14.0%.
Space: The top line improved 4% year over year to $3.49 billion, driven primarily by higher sales from strategic and missile defense programs, reflecting increased volume on the Fleet Ballistic Missile and Next Generation Interceptor programs. This growth was partially offset by lower sales from national security space programs.
The segment’s operating profit remained unchanged at $331 million. The operating margin contracted 40 bps to 9.5%.
Rotary and Mission Systems: Quarterly revenues increased 3% year over year to $4.51 billion, driven by higher sales from Sensors, Effectors & Mission Systems programs due to increased volume on radar programs.
The segment reported an operating profit of $524 million compared with $506 million in the second quarter of 2025. The operating margin remained unchanged at 11.6%.
Financial Condition of LMT
Lockheed’s cash and cash equivalents totaled $5.96 billion as of Sept. 27, 2026, compared with $4.12 billion at the end of 2025.
Cash from operating activities amounted to $3.44 billion in the third quarter of 2026 compared with $3.73 billion in the year-ago quarter.
Long-term debt as of Sept. 27, 2026, totaled $20.50 billion compared with $20.53 billion at the end of 2025.
Lockheed’s 2026 Guidance
Lockheed expects to generate sales in the range of $80.00-$82.00 billion in 2026 compared with its previous guidance of $79.75-$81.75 billion. The Zacks Consensus Estimate is pegged at $80.86 billion, which lies below the midpoint of the company’s sales guidance.
LMT expects to generate adjusted EPS in the range of $30.35-$30.75 compared with its previous guidance of $29.95-$30.65. The consensus estimate is currently pegged at $30.43 per share, which lies below the midpoint of the company’s guidance.
Lockheed expects to generate cash from operations in the range of $10.00-$10.20 billion.
It expects capital expenditures of approximately $2.10-$2.30 billion.
Lockheed expects to generate free cash flow of approximately $7.80-$8.00 billion.
LMT’s Zacks Rank
LMT currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Upcoming Defense Releases
The Boeing Company BA is set to report third-quarter 2026 earnings on Oct. 27, 2026, before market open.
The Zacks Consensus Estimate for BA’s loss is pegged at 14 cents per share. The consensus estimate for its sales is pegged at $24.53 billion, indicating year-over-year growth of 5.4%.
Huntington Ingalls Industries HII is set to report third-quarter 2026 earnings on Oct. 29, 2026, before market open.
The consensus estimate for HII’s earnings is pegged at $4.45 per share. The consensus estimate for its sales is pegged at $3.39 billion, indicating year-over-year growth of 6.1%.
General Dynamics Corporation GD is set to report third-quarter 2026 results on Oct. 30, 2026, before market open.
The Zacks Consensus Estimate for GD’s earnings is pegged at $4.14 per share. The consensus estimate for its sales is pegged at $13.71 billion, indicating year-over-year growth of 6.2%.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Lockheed Martin Corporation (LMT): Free Stock Analysis Report
The Boeing Company (BA): Free Stock Analysis Report
General Dynamics Corporation (GD): Free Stock Analysis Report
Huntington Ingalls Industries, Inc. (HII): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).