

Pentair plc. PNR is set to release third-quarter 2026 results on Oct. 27, before the opening bell.
The Zacks Consensus Estimate for PNR’s third-quarter sales is pegged at $963.6 million, indicating a 5.7% decline from the year-ago reported figure.
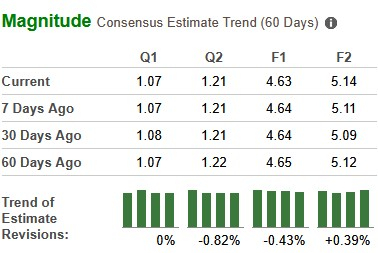
The consensus estimate for PNR’s earnings has been unchanged at $1.07 over the past 60 days. The estimate suggests a year-over-year decline of 13.7%.
Pentair’s Strong Earnings Surprise History
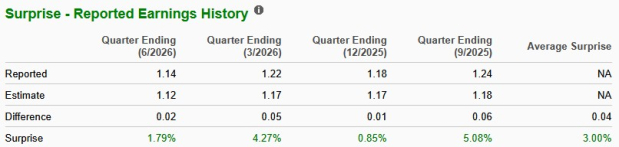
PNR’s earnings beat the Zacks Consensus Estimate in the trailing four quarters, delivering an average surprise of 3%. This is depicted in the following chart.
What the Zacks Model Unveils for PNR Stock
Our model does not conclusively predict an earnings beat for Pentair this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. However, that is not the case here, as you can see below.
Earnings ESP: Pentair has an Earnings ESP of -1.56%. You can uncover the best stocks before they are reported with our Earnings ESP Filter.
Zacks Rank: PNR currently carries a Zacks Rank #3.
Factors Likely to Have Shaped Pentair’s Q3 Performance
For the third quarter of 2026, PNR expects reported sales to fall 4-6% year over year. Over the past few quarters, Pentair’s revenues have been driven by the Water Solutions and Flow segments, which have helped offset the decline in the Pool segment. This is expected to have continued in the third quarter of 2026 as well.
The Water Solutions segment has been witnessing a decrease in sales in the past few quarters, reflecting the impacts of portfolio exits. However, return on sales improved 560 basis points to 30% in the second quarter of 2026, supported by productivity and price exceeding inflation.
Pentair expects Water Solutions sales to be flat in 2026, with low-single-digit sales growth expected in the third quarter of 2026. Our model predicts the Water Solutions segment’s net sales to rise 1.4% year over year to $422 million. Volumes are expected to dip 2.7%, while pricing is anticipated to rise 3.1% in the quarter.
For the third quarter of 2026, the company expects Flow sales to rise in the high single digit. We expect the Flow segment’s sales to be $274 million, indicating an increase of 8.9% from the prior-year quarter’s actual. Our model predicts a 1.2% year-over-year jump in volumes. Pricing is expected to have a positive impact of 2.7%, while acquisitions, reflecting the contribution of Hydra-stop, are expected to have added 4%.
Pentair’s volume outlook deteriorated materially in the second quarter of 2026 as Pool channel partners reduced orders to right-size inventory. Pool sales fell 42% year over year, including about $170 million of destocking. Weak end-market demand amid elevated interest rates and persistent inflation continues to impact demand. Third-quarter 2026 Pool sales are expected to decline 23-25%, extending the revenue drag into the second half.
We anticipate a year-over-year volume decline of 29%, while pricing is expected to rise 3.4% in the third quarter. Our model projects the Pool segment’s sales for the third quarter of 2026 to fall 25% from the year-ago actual to $266 million.
PNR Stock Price Performance
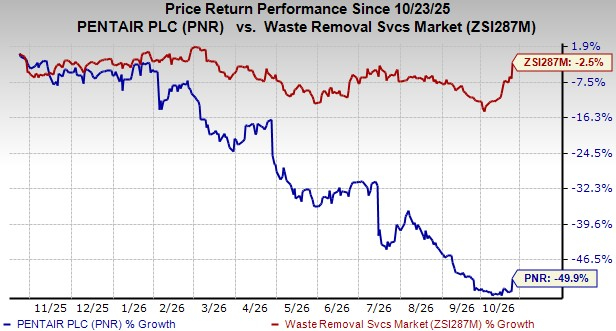
Pentair shares have lost 49.9% over the past year compared with the industry’s 2.5% decline.
Stocks That Warrant a Look
Here are some companies with the right combination of elements to post an earnings beat in their upcoming releases.
Eaton Corporation plc ETN, slated to release third-quarter 2026 results soon, has an Earnings ESP of +0.53% and a Zacks Rank of 2 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Eaton’s third-quarter 2026 earnings is pegged at $3.53 per share, suggesting a year-over-year rise of 15%. ETN has a trailing four-quarter average surprise of 1.3%.
Deere & Company DE, slated to release fourth-quarter fiscal 2026 results on Nov. 25, has an Earnings ESP of +3.59% and a Zacks Rank of 3 at present.
The Zacks Consensus Estimate for Deere’s fourth-quarter fiscal 2026 earnings is pegged at $4.07 per share, indicating a year-over-year rise of 3.6%. DE has a trailing four-quarter average surprise of 11.1%.
Emerson Electric Co. EMR, slated to release fourth-quarter fiscal 2026 results on Nov. 4, has an Earnings ESP of +1.00% and a Zacks Rank of 2 at present.
The Zacks Consensus Estimate for Emerson Electric’s fourth-quarter 2026 earnings is pegged at $1.84 per share, implying a year-over-year rise of 13%. EMR has a trailing four-quarter average surprise of 1.3%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Pentair plc (PNR): Free Stock Analysis Report
Emerson Electric Co. (EMR): Free Stock Analysis Report
Eaton Corporation, PLC (ETN): Free Stock Analysis Report
Deere & Company (DE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).