

MP Materials MP and Lynas Rare Earths Limited LYSDY are key players in the global rare earth supply chain and are expected to play key roles in the West’s efforts to secure critical mineral independence and reduce reliance on Chinese supply.
Las Vegas, NV-based MP Materials is the only fully integrated rare earth producer in the United States. It has capabilities covering the entire supply chain, from mining and processing to advanced metallization and magnet manufacturing. MP has a market capitalization of $7 billion. Perth, Australia-based Lynas, valued at around $8 billion, engages in the exploration, development, mining, extraction and processing of rare earth minerals in Australia and Malaysia.
Both companies are expanding their production capabilities and strengthening their positions in the permanent magnet market, which serves electric vehicles (EVs), defense systems and other advanced technologies. However, differences in operational execution, profitability and valuation warrant a closer look before investors choose between the two stocks.
The Case for MP Materials
MP Materials operates the Mountain Pass mine and processing facility, producing refined rare-earth products, concentrates and related materials. It also owns the Independence facility in Fort Worth, TX, where it manufactures magnetic precursor products and began producing permanent magnets in December 2025.
Supported by government incentives, the company is constructing the second domestic magnet manufacturing facility (the 10X Facility) in Northlake, TX, which will lift its total U.S. magnet capacity to 10,000 metric tons.
MP has been making progress in expanding its rare earth production. Neodymium-praseodymium (NdPr) production increased 41% year over year to 840 metric tons in the second quarter of 2026, despite a scheduled semiannual maintenance outage at Mountain Pass. Management expects third-quarter NdPr production to have exceeded 1,000 metric tons as throughput and plant reliability improved.
The company also remains on track to begin producing terbium (Tb) and dysprosium (Dy) later in 2026, with initial samarium production targeted for 2028. MP recently entered into a multiyear agreement to supply gadolinium oxide to a leading U.S. aerospace and defense manufacturer.
The company’s downstream business is also gaining traction. During the second quarter, MP Materials delivered magnets to General Motors Company GM for in-vehicle qualification testing and expects to begin commercial shipments in the fourth quarter, followed by a steady production ramp. Its partnership with Apple Inc. AAPL on magnet recycling, production and joint development is also progressing. In addition, Project Swarm, an initiative developed with U.S. and allied drone manufacturers, aims to aggregate and standardize future magnet demand. MP has already signed subscription agreements with several participants.
MP reported an 89% year-over-year increase in second-quarter 2026 revenues to $108.5 million. The company also recorded $17.58 million in income tied to a price protection agreement (PPA) with the U.S. Department of War (DoW).
However, rising costs remain a concern. Cost of sales increased 43.3% year over year, while selling, general and administrative expenses climbed 28.2%. Start-up costs rose sharply to $14.4 million from $0.76 million a year earlier as the company advanced initial magnet production. Further cost pressures and higher start-up expenses are likely as MP scales its manufacturing operations.
Thus, while government support, production growth and downstream integration offer substantial long-term opportunities, MP must demonstrate that its expanding operations can translate into sustainable profitability.
The Case for Lynas
The company’s operations are anchored by the high-grade Mt Weld mine in Western Australia. Material from Mt Weld is processed at facilities in Kalgoorlie and the Lynas Malaysia advanced materials plant in Kuantan. Lynas is also developing a Heavy Rare Earth (HRE) processing facility in Texas under a U.S. DoW contract.
Lynas reached a milestone in 2025 by producing dysprosium oxide (Dy) and terbium oxide (Tb) on the new production line at Lynas Malaysia. It marked Lynas' first commercial production of separated HRE and its first production outside China in decades. In March 2026, the company also produced samarium oxide, a month ahead of its target. Lynas is targeting gadolinium production in early fiscal 2028 and yttrium production in early calendar 2028, with lutetium to follow.
Lynas reported NdPr production of 7,260 tons in fiscal 2026 (ended June 30, 2026), up 11% year over year. Total REO production reached 13,089 tons, up 25% from the prior year.
Lynas’ revenues jumped 76% year over year to a record AUD 977.9 million ($680.5 million) in fiscal 2026 on higher prices and volumes. Adjusted EBITDA surged 281% year over year to AUD 386 million ($268.6 million) in fiscal 2026. Net Profit After Tax (NPAT) increased to AUD 222.4 million ($156 million) compared with AUD 8 million in fiscal 2025.
Lynas continues to face operational and cost challenges as it integrates new facilities and expands capacity. Higher fixed costs associated with facilities undergoing commissioning and ramp-up, more expensive inputs sourced outside China and geopolitical cost pressures weighed on its cost base. At Mt Weld, the company experienced challenges involving the new water recycling plant and variations in ore characteristics that affected downstream processing. It has improved operating standards to manage these variations.
The Kalgoorlie processing facility also continued its ramp-up, with process modifications completed to improve product quality and productivity. These included changes to the precipitation process to increase capacity and improve the quality of mixed rare earth carbonate. Electricity supply disruptions affected operations during the December quarter of fiscal 2026, although supply stabilized later in the second half of fiscal 2026. Lynas continues to explore alternative supply options.
Having largely completed its Lynas 2025 growth plan, the company is now pursuing its “Towards 2030” strategy. Its priorities include optimizing the returns from recent capital investments, expanding its resource base and production scale, and increasing its participation in the metal and magnet supply chain through partnerships with downstream manufacturers.
The proposed acquisition of Meteoric Resources is another important component of this strategy. The transaction would combine Meteoric’s flagship Caldeira deposit, described as the largest known ionic clay rare earth Mineral Resource outside China, with Lynas’ Mt Weld resource and established operating capabilities. The deal is expected to support resource expansion, increase future feedstock capacity for NdPr and heavy rare earths, and strengthen Lynas’ longer-term growth prospects, subject to completion and execution.
Lynas has also secured a 10-year renewal of its Malaysian operating license, providing greater regulatory certainty than the previous three-year licenses. Together with its expanding product portfolio, improving earnings and investments in downstream capabilities, this offers a stronger foundation for future growth. However, successful execution of its expansion plans and continued improvement in operating efficiency will remain important.
How do Estimates Compare for MP & LYSDY?
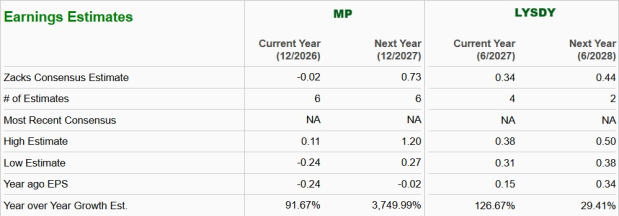
The Zacks Consensus Estimate for MP Materials’ fiscal 2026 earnings is pegged at a loss of 2 cents per share compared with a loss of 24 cents in 2025. The estimate for MP Materials’ 2027 earnings is 73 cents per share.
The Zacks Consensus Estimate for Lynas’ fiscal 2027 earnings (ending June 2027) is pegged at 34 cents per share, indicating an increase of 127% year over year. The fiscal 2027 estimate of 44 cents indicates 29.4% year-over-year growth.
Image Source: Zacks Investment Research
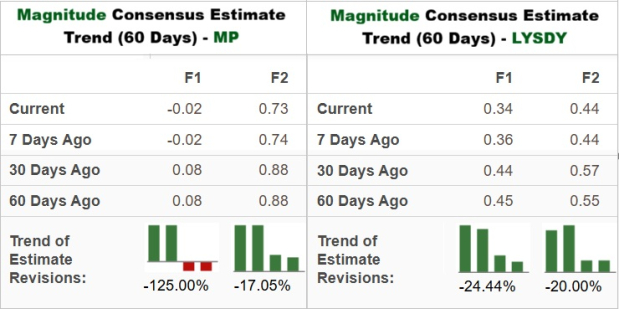
However, analyst sentiment has weakened for both companies. Both companies have been witnessing downward revisions to their estimates, as shown in the chart below.
Image Source: Zacks Investment Research
MP vs. LYSDY: Price Performance & Valuation
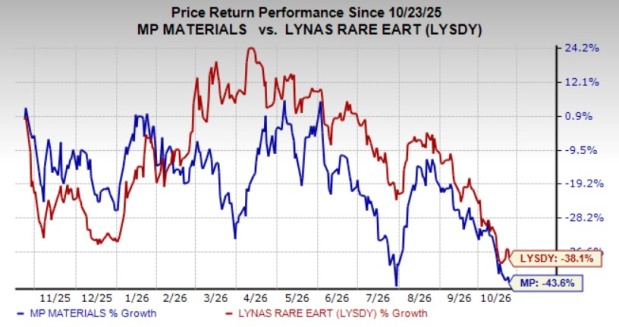
Over the past year, MP Materials stock has declined 43.6% compared with Lynas’ 38.1% fall.
Image Source: Zacks Investment Research
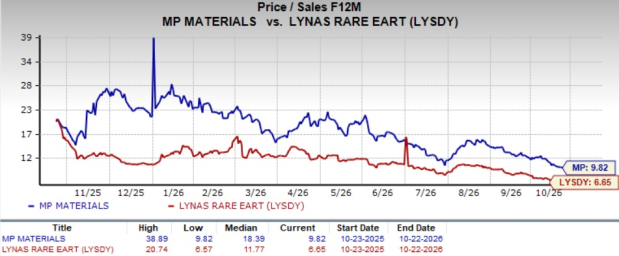
MP Materials is currently trading at a forward 12-month price-to-sales ratio of 9.82, while Lynas is trading at a lower 6.65.
Image Source: Zacks Investment Research
MP Materials or Lynas: Which Stock is the Better Buy?
MP Materials and Lynas Rare Earths are positioned to benefit from growing demand for rare earths and efforts to diversify global supply chains. MP’s government-backed initiatives, expanding magnet manufacturing capacity and downstream integration offer significant long-term growth potential. However, elevated start-up costs, rising operating expenses and continued investment requirements weigh on near-term profitability.
Lynas has demonstrated stronger financial performance, with record fiscal 2026 revenues, higher profits and commercial production of heavy rare earths. Its lower forward price-to-sales multiple of 6.65 compared with MP’s 9.82 also makes it relatively more attractive. However, operational challenges and downward earnings estimate revisions remain concerns.
MP Materials currently carries a Zacks Rank #5 (Strong Sell), while Lynas holds a Zacks Rank #4 (Sell). Investors may prefer to wait for earnings estimates to stabilize and operational improvements to translate into sustained profitability before considering either stock.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
MP Materials Corp. (MP): Free Stock Analysis Report
Lynas Rare Earths Limited - Sponsored ADR (LYSDY): Free Stock Analysis Report
Apple Inc. (AAPL): Free Stock Analysis Report
General Motors Company (GM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).