

Mid-America Apartment Communities MAA — commonly known as MAA — is a real estate investment trust (REIT) that focuses on owning, operating and acquiring apartment communities throughout the Southeast, Southwest and Mid-Atlantic regions of the United States. The company is slated to report third-quarter 2026 results on Oct. 28, after market close.
In the last reported quarter, this Germantown, TN-based residential REIT reported core FFO per share of $2.08, in line with the Zacks Consensus Estimate. Results reflected same-store effective blended lease rate growth year over year.
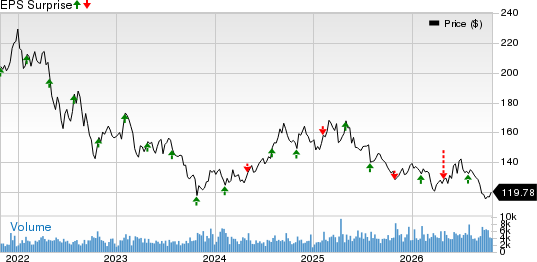
Over the trailing four quarters, MAA surpassed the Zacks Consensus Estimate on two occasions, met once and missed on the other, with the average beat being 0.12%. This is depicted in the chart below:
Mid-America Apartment Communities, Inc. Price and EPS Surprise
Mid-America Apartment Communities, Inc. price-eps-surprise | Mid-America Apartment Communities, Inc. Quote
Let’s see how things have shaped up before this announcement.
US Apartment Market in Q3
The U.S. multifamily residential market continues to recover, supported by strong rental demand, declining supply and improving occupancy. According to Cushman & Wakefield’s third-quarter 2026 report, national multifamily vacancy declined 30 basis points sequentially to 8.6%, its lowest level in three years. Net absorption reached nearly 350,000 units during the first nine months of 2026, up 14% year over year, reflecting resilient renter demand.
Meanwhile, new apartment deliveries declined 25% year over year to approximately 250,000 units, while the construction pipeline fell to its lowest level since 2015. Annual asking rent growth accelerated to 2.3% in the third quarter from 1.1% in the first quarter, with average monthly rents reaching $1,950. High financing costs are slowing new developments, supporting a gradual recovery across Sunbelt markets.
Factors to Consider Ahead of MAA’s Upcoming Results
MAA’s third-quarter 2026 results are expected to benefit from improving leasing momentum, strong renewals and moderating supply pressures. Management expects blended lease growth to improve from the second quarter, supported by renewal rates above 5%, higher resident retention and stronger pricing trends in August and September.
Higher lead volumes and improving absorption should support new lease pricing, while pre-leasing rates were running 70-80 basis points ahead of year-ago levels. Disciplined expense management, lower insurance and property tax costs, and incremental NOI contributions from lease-up properties are likely to have supported earnings.
However, slower-than-expected rent recovery, occupancy pressures and high financing costs may have remained concerns.
Projections for MAA
The Zacks Consensus Estimate for quarterly revenues is pegged at $557.98 million. This suggests a 0.65% rise from the year-ago quarter’s reported figure.
For the third quarter, we project an average physical occupancy of 95.4%. However, our estimate indicates a 15.7% increase in the company’s interest expenses.
Before the second-quarter earnings release, the company’s activities were not adequate to gain analysts’ confidence. The Zacks Consensus Estimate for the quarterly core FFO per share has remained unchanged at $2.10 for more than three months. This also suggests a year-over-year decline of 2.78%.
Here Is What Our Quantitative Model Predicts for MAA
Our proven model does not conclusively predict a surprise in terms of FFO per share for MAA this season. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an FFO beat, which is not the case here.
MAA currently carries a Zacks Rank of 4 (Sell) and has an Earnings ESP of -0.76%. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Stocks That Warrant a Look
Here are two stocks from the broader REIT sector, Innovative Industrial Properties IIPR and Host Hotels & Resorts HST, which you may want to consider, as our model shows that these have the right combination of elements to report an FFO beat this quarter.
Innovative Industrial Properties is slated to report quarterly numbers on Nov. 2. IIPR has an Earnings ESP of +1.64% and carries a Zacks Rank of 3 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
Host Hotels & Resorts is slated to report quarterly numbers on Nov. 4. HST has an Earnings ESP of +3.20% and a Zacks Rank of 3 at present.
Note: Anything related to earnings presented in this write-up represents funds from operations (FFO), a widely used metric to gauge the performance of REITs.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Mid-America Apartment Communities, Inc. (MAA): Free Stock Analysis Report
Host Hotels & Resorts, Inc. (HST): Free Stock Analysis Report
Innovative Industrial Properties, Inc. (IIPR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).