

Smurfit Westrock PLC SW is scheduled to report third-quarter 2026 results on Oct. 28, before market open.
The Zacks Consensus Estimate for revenues is pegged at $8.32 billion, indicating 3.9% growth from the year-ago quarter's reported figure.
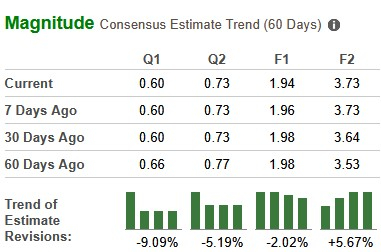
The consensus mark for earnings per share is pegged at 60 cents, indicating year-over-year growth of 3.4%. The bottom-line estimate has moved down in the past 60 days.
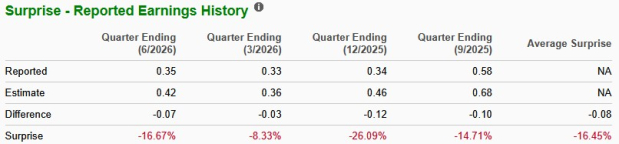
Smurfit Westrock’s Earnings Surprise History
The company’s earnings missed the Zacks Consensus Estimate in the trailing four quarters, delivering an average negative surprise of 16.5%.
Factors Likely to Shape SW’s Q3 Results
The demand for corrugated packaging and containerboard used to package essential items, such as food, beverages and medicines, has been stable. Strong growth in e-commerce and rising demand for paper as a sustainable packaging solution have favored the industry. These trends are expected to get reflected in Smurfit Westrock’s third-quarter 2026 results.
However, some of these gains are likely to have been offset by lower volumes in North America and lower box demand. This is expected to hurt Smurfit Westrock’s quarterly results. The company expects year-over-year volume growth in either the third or fourth quarter, but the timing remains uncertain.
Inflation in freight, energy and labor is expected to have affected SW’s quarterly performance and free cash flow margin. Pricing actions and cost-saving initiatives are likely to have negated some of these headwinds.
Smurfit Westrock’s Q3 Segmental Projection
The Zacks Consensus Estimate for Europe, MEA and APAC’s revenues is pegged at $2.97 billion for the third quarter, indicating an increase from the $2.82 billion reported in the third quarter of 2025. The segment’s adjusted EBITDA is pegged at $435 million. In the prior-year quarter, the segment reported adjusted EBITDA of $419 million.
The estimates for the North America segment’s third-quarter 2026 revenues are pegged at $4.81 billion, whereas it reported $4.64 billion in the year-ago quarter. The Zacks Consensus Estimate for the segment’s adjusted EBITDA is pegged at $799 million, suggesting a 1.4% year-over-year dip.
The LATAM segment’s revenue estimate is pegged at $558 million, suggesting year-over-year growth from $545 million. The Zacks Consensus Estimate for the segment’s adjusted EBITDA is pegged at $120 million, indicating a rise from the $116 million reported in the prior-year quarter.
What the Zacks Model Unveils for SW Stock
Our model predicts an earnings beat for Smurfit Westrock this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That is not the case here.
SW’s Earnings ESP: The Earnings ESP for Smurfit Westrock is +1.67%. You can uncover the best stocks before they are reported with our Earnings ESP Filter.
SW’s Zacks Rank: SW currently has a Zacks Rank #3.
Smurfit Westrock Stock’s Price Performance
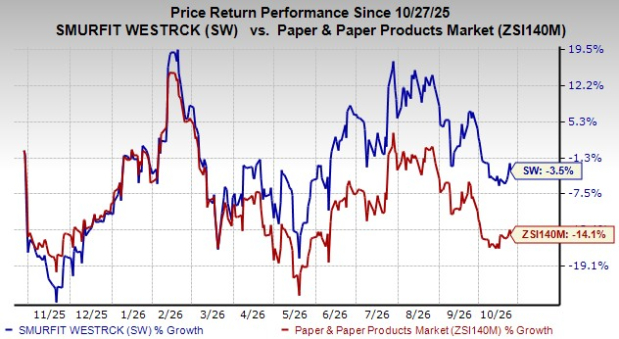
Shares of the company have lost 3.5% in the past year compared with the industry’s 14.1% growth.
Stocks to Consider
Here are some Basic Materials stocks, which, according to our model, have the right combination of elements to post an earnings beat in their upcoming releases.
FreeportMcMoRan FCX, scheduled to release third-quarter 2026 earnings on Oct. 27, has an Earnings ESP of +0.63% and a Zacks Rank of 2 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for earnings for FreeportMcMoRan for the third quarter of 2026 is 75 cents per share, indicating a 50% year-over-year increase. FreeportMcMoRan has a trailing four-quarter average earnings surprise of 32.6%.
DuPont de Nemours, Inc. DD, scheduled to release earnings on Nov. 3, has an Earnings ESP of +1.35%.
The Zacks Consensus Estimate for earnings for DuPont for the third quarter of 2026 is pegged at $1.86 per share, suggesting a 43% year-over-year dip. DD has a trailing four-quarter average earnings surprise of 8.3%.
Huntsman Corporation HUN, slated to release third-quarter earnings on Nov. 2, has an Earnings ESP of +36.12% and a Zacks Rank #3 at present.
The Zacks Consensus Estimate for Huntsman earnings for the third quarter of 2026 is pegged at 7 cents per share, indicating 333% growth from the year-ago quarter’s reported figure.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Smurfit Westrock PLC (SW): Free Stock Analysis Report
Freeport-McMoRan Inc. (FCX): Free Stock Analysis Report
DuPont de Nemours, Inc. (DD): Free Stock Analysis Report
Huntsman Corporation (HUN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).