

Quanta Services, Inc. PWR and EMCOR Group, Inc. EME are leading players in the U.S. infrastructure services market, benefiting from rising investments in data centers, power infrastructure, advanced manufacturing and mission-critical facilities. Both companies are capitalizing on growing demand for specialized construction services, infrastructure modernization and increased project complexity.
Quanta focuses on electric infrastructure, power generation, utility networks and underground infrastructure, while EMCOR specializes in electrical and mechanical construction, industrial infrastructure and building services. Their complementary exposure to expanding infrastructure investments makes them worth comparing, particularly ahead of their third-quarter 2026 earnings releases.
Let's dive deep and closely compare the fundamentals of the two stocks to determine which one is a better investment now.
The Case for Quanta Stock
Quanta continues to benefit from accelerating investments in electric grid modernization, power generation, data centers and large-scale infrastructure projects. Rising electricity consumption, driven by artificial intelligence (AI), electrification and industrial expansion, is creating substantial opportunities across its core markets.
The company's second-quarter 2026 revenues surged 41.1% year over year to $9.56 billion, supported by 27.4% organic growth. Adjusted earnings per share jumped 71% to $4.24. Its Electric Infrastructure Solutions segment recorded 44% revenue growth, while Underground Utility and Infrastructure Solutions revenues increased 31%.
Quanta's record backlog of $53.4 billion provides considerable revenue visibility. The Electric segment accounted for $43.8 billion of this backlog, reflecting sustained customer investments in grid reliability, transmission infrastructure and technology-related projects.
Strategic acquisitions are strengthening Quanta's competitive position. The additions of Phalcon, Enerfab, Percheron and PSD expand its capabilities across electrical, mechanical, fabrication and engineering services. These acquisitions are expected to contribute approximately $1.2-$1.4 billion in 2026 revenues and $120-$140 million in adjusted EBITDA.
Following its strong first-half performance, management raised its 2026 revenue guidance to $39.3-$39.7 billion and adjusted earnings per share (EPS) expectations to $16.45-$16.95. Adjusted EBITDA is projected to be in the range of $4.09-$4.21 billion, while free cash flow is anticipated to be between $2 billion and $2.5 billion.
However, Quanta faces challenges from rising labor costs, supply-chain constraints, inflation and project execution risks. Its acquisition-led expansion also increases integration requirements and capital commitments. Regulatory delays, permitting challenges and changes in project schedules could affect revenue conversion and profitability.
The Case for EMCOR Stock
EMCOR is benefiting from strong demand for electrical and mechanical construction services across data centers, healthcare facilities, manufacturing plants and institutional infrastructure. Its diversified operations and disciplined project selection continue to support profitable expansion.
Second-quarter 2026 revenues increased 19.8% year over year to $5.15 billion, supported by 19.6% organic growth. Earnings per share rose 34.8% to $9.06, while operating margin improved 100 basis points to 10.6%.
EMCOR's Electrical Construction and Mechanical Construction businesses registered revenue growth of 24% and 31%, respectively. Their operating margins reached 13.9% and 12.5%, highlighting strong execution and favorable project opportunities.
Remaining performance obligations or RPOs reached a record $17.14 billion, increasing 43.9% year over year. Growing opportunities in network and communications, water and wastewater, institutional facilities and healthcare support its medium-term revenue prospects.
Management raised its 2026 revenue outlook to $20-$20.5 billion and EPS guidance to $32-$33.25. The projected operating margin of 9.5%-9.8% reflects confidence in profitability and execution.
EMCOR's strategic acquisitions, prefabrication capabilities and disciplined capital allocation further support expansion. Its building services operations also provide diversification beyond large construction projects.
Nevertheless, EMCOR faces risks from skilled-labor shortages, rising material costs, project delays and competitive pricing. Increased exposure to large technology-related projects could also create execution and customer-concentration challenges. Maintaining elevated margins amid a changing project mix remains important.
PWR Outpaces EME in Share Price Performance
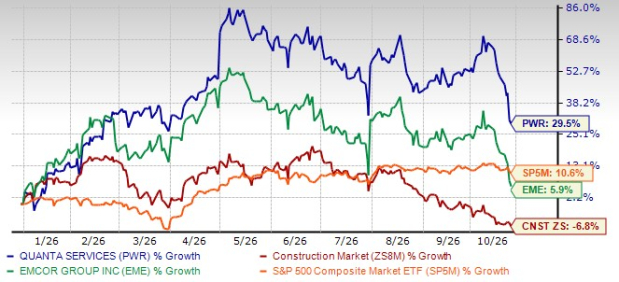
Quanta shares have gained 29.5% year to date (YTD), significantly outperforming EMCOR's 5.9% increase. Both stocks have outperformed the broader Zacks Construction sector, which has declined 6.8%, while the S&P 500 has gained 10.6%.
Quanta's stronger stock performance reflects greater investor confidence in its growth prospects. However, its substantial rally also increases expectations for sustained earnings momentum.
PWR vs EME Price Performance (YTD)
Image Source: Zacks Investment Research
PWR's Premium Valuation Versus EME's Discount
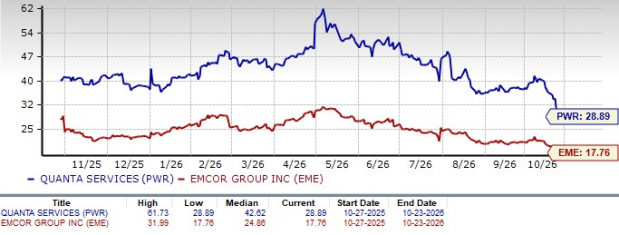
On a forward 12-month price-to-earnings (P/E) basis, Quanta trades at 28.89X, considerably above EMCOR's 17.76X and the Construction sector's 16.72X.
Quanta's premium reflects its stronger growth expectations, substantial backlog and exposure to long-term electrification opportunities. However, this valuation leaves limited room for execution setbacks.
EMCOR appears relatively attractive on valuation, particularly considering its profitability and backlog strength. Its lower multiple offers a more favorable entry point, though slower projected growth and weaker earnings revision momentum partially explain the discount.
PWR vs EME Valuation (P/E F12M)
Image Source: Zacks Investment Research
PWR Leads EME in Earnings Estimate Revisions
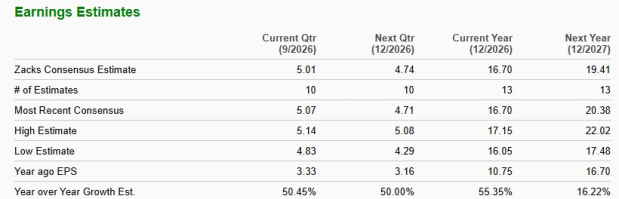
Over the past 60 days, the Zacks Consensus Estimate for Quanta's 2026 EPS increased from $16.43 to $16.70, while the 2027 estimate rose from $19.23 to $19.41. The projections indicate 55.4% EPS growth on 38.4% revenue growth in 2026, followed by 16.2% earnings growth on 14.8% revenue growth in 2027.
Quanta’s EPS Estimate
Image Source: Zacks Investment Research
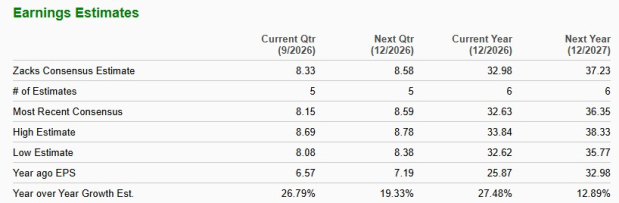
Conversely, EMCOR's consensus estimate for EPS remained unchanged at $32.98 for 2026 and $37.23 for 2027. The projections suggest 27.5% earnings growth on 19.6% revenue growth in 2026, followed by 12.9% EPS growth on 11% revenue growth in 2027.
EMCOR’s EPS Estimate
Image Source: Zacks Investment Research
Quanta's positive estimate revisions and faster projected growth provide a clear advantage.
PWR or EME: Which Stock Offers Better Upside?
Both companies remain well-positioned to benefit from infrastructure modernization and rising technology-related construction activity. EMCOR's lower valuation, strong margins and disciplined execution make it attractive from a value perspective.
However, Quanta appears to be the better investment choice, supported by stronger revenue growth, accelerating earnings estimates, larger backlog and broader exposure to electric infrastructure investments. Although its premium valuation warrants caution, its superior growth prospects provide greater potential for sustained earnings expansion.
Quanta currently carries a Zacks Rank #3 (Hold) compared with EMCOR's Zacks Rank #4 (Sell), further supporting a preference for PWR over EME at present.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Quanta Services, Inc. (PWR): Free Stock Analysis Report
EMCOR Group, Inc. (EME): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).