

Marathon Petroleum Corporation MPC has benefited from stronger refining margins, improved operational performance and resilient demand for refined products. The company's second-quarter 2026 results reflected a sharp recovery in profitability, supported by higher crack spreads, effective crude optimization and disciplined execution. Marathon Petroleum’s growing midstream business and substantial shareholder returns further strengthen its investment case.
MPC has also outperformed peers over the past six months, while upward earnings estimate revisions and a below-industry earnings multiple add to its appeal. However, after a significant rally, investors must assess whether its improving fundamentals can support further gains.
Strong Refining Performance Supports Earnings Growth
MPC reported second-quarter 2026 adjusted EBITDA of $8.5 billion, up from $3.3 billion in the prior-year quarter. Net income attributable to MPC increased to $5.1 billion from $1.2 billion. This improvement was driven primarily by stronger refining margins and higher crack spreads across all regions.
The Refining & Marketing (R&M) segment generated adjusted EBITDA of $6.7 billion, compared with $1.9 billion a year earlier. Adjusted EBITDA per barrel increased to $24.84 from $6.79, while crude capacity utilization reached 94%.
MPC's operational execution further strengthens its competitive position. The company achieved R&M margin capture of 112% in the second quarter and 108% in the first half of 2026. Management also reported the lowest level of unplanned downtime in a decade. These results highlight MPC's ability to capture value through advantaged crude sourcing, feedstock optimization and reliable refinery operations.
MPC is also investing in projects designed to improve product yields. Its Robinson refinery investment enables approximately 10,000 barrels per day of incremental jet fuel production, while the El Paso project enhances specialty gasoline production. These completed projects could strengthen margins by increasing higher-value product output, although actual returns will depend on market conditions.
MPC Outpaces Valero and Phillips 66 Over the Past 6 Months
MPC has outperformed its peers and sub-industry, gaining 87.4% compared with 76.8% for the Oil Refining & Marketing sub-industry, 62.6% for Phillips 66 PSX and 61.2% for Valero Energy VLO over the six-month period shown in the chart.
Image Source: Zacks Investment Research
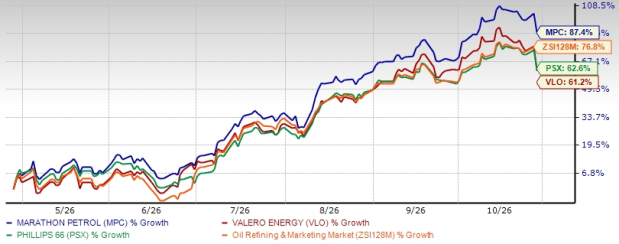
The stronger share-price performance suggests investor confidence in MPC's earnings outlook and operating performance. Phillips 66 and Valero Energy also posted substantial gains during the period, but MPC's larger advance reflects its stronger relative share-price performance.
However, past performance does not guarantee further gains. MPC, Phillips 66 and Valero Energy remain exposed to changes in refining margins, refined product demand and industry capacity. MPC's ability to sustain its outperformance will depend on whether its earnings growth remains strong as market conditions evolve.
MPC's Valuation Looks Reasonable, but the Rally Raises the Bar
MPC's valuation remains a positive factor. The stock trades at approximately 7.15X, below the Oil Refining & Marketing sub-industry average of 8.11X. This suggests that MPC's shares are trading at a discount relative to the sub-industry despite their substantial appreciation.
Image Source: Zacks Investment Research
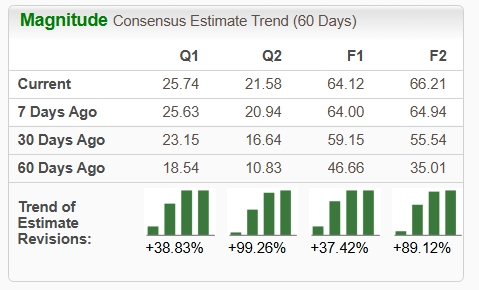
The earnings outlook is also strengthening. The consensus estimates for MPC's 2026 and 2027 earnings have increased 37.42% and 89.12%, respectively, over the past 60 days. These upward revisions indicate improving analyst expectations for the company's earnings potential.
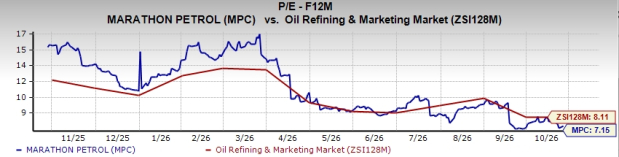
Image Source: Zacks Investment Research
Midstream Rise, Liquidity and Capital Returns Add to the Investment Case
MPC's investment case extends beyond refining. Its midstream business, MPLX LP, is expanding natural gas and natural gas liquids infrastructure to meet growing demand. MPLX increased its 2026 growth capital spending outlook by $500 million to $2.9 billion, primarily reflecting the accelerated execution of the Gulf Coast fractionation project. These investments are expected to support mid-single-digit adjusted EBITDA improvement in 2026 and 12.5% annual distribution growth in both 2026 and 2027.
MPC's strong liquidity also provides financial flexibility. As of June 30, 2026, the company held $7.8 billion in cash and cash equivalents and had no borrowings outstanding under its $5 billion revolving credit facility. This financial position supports its investment plans and provides flexibility during periods of market volatility.
MPC returned approximately $2.8 billion to its shareholders in the second quarter, including $2.5 billion in share repurchases. Its Renewable Diesel segment also returned to profitability, generating $258 million in adjusted EBITDA in contrast to a loss of $19 million in the prior-year quarter. Stronger margins, higher throughputs and improved regulatory credit values supported the recovery, providing an additional earnings contributor beyond conventional refining and midstream operations.
Is MPC Stock a Buy Now?
MPC's strong refining performance, margin capture above 100%, rising earnings estimates, competitive valuation and substantial share repurchases strengthen its bullish outlook. Operational reliability, solid liquidity and midstream growth provide additional support.
MPC's 87.4% six-month gain reflects strong momentum, while its valuation remains below the Oil Refining & Marketing sub-industry average. The stock sports a Zacks Rank #1 (Strong Buy), supported by favorable earnings estimate revisions. Strong operating performance and improving earnings prospects reinforce the positive investment case, despite the cyclical nature of refining. You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Marathon Petroleum Corporation (MPC): Free Stock Analysis Report
Valero Energy Corporation (VLO): Free Stock Analysis Report
Phillips 66 (PSX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).