

Cameco Corporation CCJ offers investors exposure to uranium mining, fuel services and Westinghouse as nuclear-energy demand strengthens. The attraction is broad participation across the fuel cycle, backed by established assets and long-term contracts.
The trade-off is price and execution. CCJ still commands a premium valuation even as earnings, cash generation and mine performance remain uneven, making patience a reasonable consideration for investors weighing the long-term nuclear thesis.
Cameco’s Valuation Leaves Little Room for Slippage
CCJ trades at 13.49X forward 12-month sales, well above the Zacks sub-industry’s 4.55X and Cameco’s five-year median of 9.16X. The stock also carries a Value Score of D, consistent with a valuation that does not screen as inexpensive.
Image Source: Zacks Investment Research
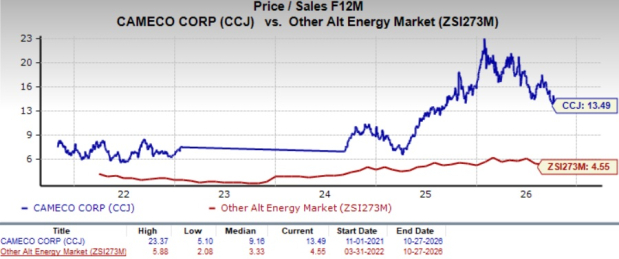
That premium raises the cost of operational disappointment. Weaker uranium deliveries, higher purchased-material costs or delays in realizing Westinghouse-related growth could pressure the multiple if results fail to support elevated expectations.
CCJ Has Multiple Paths to Long-Term Growth
Cameco participates across uranium mining, refining, conversion and fuel fabrication, while its 49% stake in Westinghouse adds exposure to reactor technology, plant services and development. The company also has uranium delivery commitments averaging more than 28 million pounds annually from 2026 through 2030.
The wider nuclear market is attracting investment as well. Constellation Energy Corporation CEG recently received a conditional U.S. Department of Energy loan commitment of up to $5 billion to support nuclear uprates across selected facilities, while recent long-term customer agreements are tied to additional nuclear capacity. Centrus Energy Corp. LEU is expanding domestic enrichment capacity and signed a $900 million Department of Energy award for high-assay, low-enriched uranium enrichment, underscoring activity across the nuclear fuel chain.
Cameco’s Earnings Quality Remains Uneven
Cameco’s 10-year earnings-per-share linearity is 34.8%, below the industry median of 51.2%. The measure points to an inconsistent earnings path despite 10-year earnings-per-share growth of 31.9%, reflecting the difference between long-term growth and smooth year-to-year compounding.
Recent results illustrate that volatility. Second-quarter 2026 adjusted net earnings fell 75% year over year to C$77 million, while first-half operating cash flow declined 81% to C$109 million. Uranium delivery timing, mine interruptions and project-linked Westinghouse contributions can produce sizable swings between periods.
Cameco Corporation Price and EPS Surprise
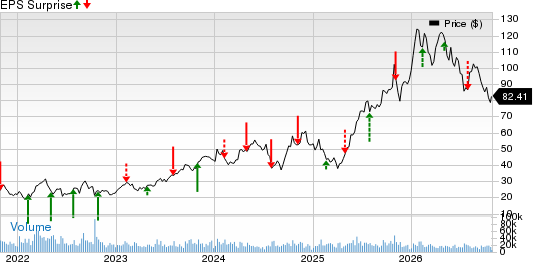
Cameco Corporation price-eps-surprise | Cameco Corporation Quote
CCJ’s Balance Sheet Provides Strategic Flexibility
As of June 30, 2026, Cameco held C$1.1 billion in cash and cash equivalents against C$1.0 billion in total debt. It also maintained an undrawn C$1.0 billion revolving credit facility.
That liquidity gives the company room to manage production variability, meet delivery commitments and fund investments across the nuclear fuel cycle. It also matters because Westinghouse expansion and mine operations can require substantial capital before returns are fully realized.
CCJ’s Scores Support a Patient Investment Stance
The long-term nuclear backdrop remains favorable, but CCJ’s premium valuation and uneven earnings profile argue against treating industry strength alone as a reason to buy. Investors may want clearer evidence of consistent mine execution, cash generation and Westinghouse contributions before assigning more confidence to the current valuation.
CCJ currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Its VGM Score of F includes a Value Score of D, Growth Score of F and Momentum Score of B. A Zacks Rank #3 can be appropriate for holding, while the Style Scores suggest a mixed setup, with momentum stronger than value and growth. Taken together, the signals support a selective, patient stance rather than an aggressive entry.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Cameco Corporation (CCJ): Free Stock Analysis Report
Constellation Energy Corporation (CEG): Free Stock Analysis Report
Centrus Energy Corp. (LEU): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).