

Capri Holdings Limited CPRI is strengthening consumer connections across Michael Kors and Jimmy Choo through refreshed collections, targeted campaigns and personalized experiences. Both brands are attracting younger shoppers while giving existing customers more reasons to return. These initiatives are reinforcing brand desirability and supporting Capri’s strategy to rebuild demand, improve sales quality and achieve sustainable growth.
Michael Kors’ global customer database increased 8% year over year in second-quarter fiscal 2027. Expanded influencer partnerships, destination-led storytelling and a newly launched TikTok shop broadened engagement with younger consumers. Management said the shop’s early performance exceeded expectations, generating strong engagement and sales. Analytics and artificial intelligence are helping the brand understand preferences and personalize customer relationships.
Jimmy Choo’s global consumer database grew 7% year over year, supported by anniversary campaigns and marketing featuring Devon Lee Carlson. Expanding accessories and casual footwear assortments created additional purchase opportunities. Accessories sales increased at a double-digit rate, with Bon Bon and Cinch delivering robust growth. Brand revenues rose 11.5% to $146 million, including about $5 million from earlier wholesale shipments.
Product and store initiatives reinforced engagement. Michael Kors’ Hamilton Soft became a best-selling handbag, with demand exceeding expectations, while renovated stores generated higher traffic and revenues. Although Capri’s revenues declined 5.5% to $809 million, gross margin expanded 230 basis points to 63.3%, supported by higher full-price sell-throughs, brand mix and lower tariff rates.
Capri raised fiscal 2027 guidance to approximately $3.42 billion in revenues and adjusted earnings of $2.20 per share. Michael Kors is expected to generate $2.77 billion in revenues with a low-double-digit adjusted operating margin, returning to revenue growth in the fourth quarter. Jimmy Choo is projected to deliver $650 million in revenues and a low-single-digit adjusted operating margin, returning to annual revenue growth and profitability. Management expects Capri’s revenue growth to resume in the second half of fiscal 2027.
CPRI’s Price Performance, Valuation & Estimates
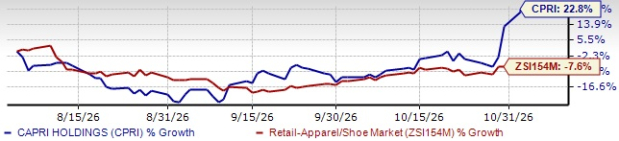
Shares of Capri Holdings have gained 22.8% over the past three months against the industry’s 7.6% decline.
Image Source: Zacks Investment Research
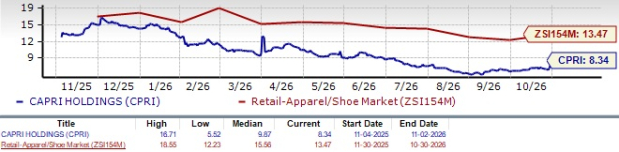
From a valuation standpoint, CPRI trades at a forward price-to-earnings ratio of 8.34, below the industry’s average of 13.47. It has a Value Score of A.
Image Source: Zacks Investment Research
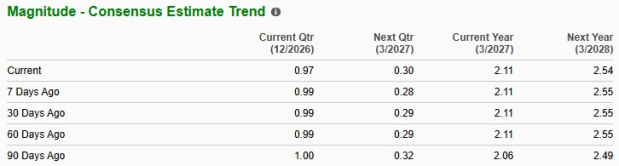
The Zacks Consensus Estimate for Capri Holdings’ fiscal 2027 earnings implies year-over-year growth of 40.7%, whereas the same for fiscal 2028 indicates an uptick of 20.8%. Earnings estimates for fiscal 2027 and 2028 have remained unchanged and decreased by 1 cent, respectively, over the past seven days.
Image Source: Zacks Investment Research
CPRI’s Zacks Rank & Other Key Picks
Capri Holdings currently carries a Zacks Rank #2 (Buy).
Genesco Inc. GCO is a Nashville-based specialty retailer and branded company. It sells footwear and accessories through retail stores. The company flaunts a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Genesco’s current fiscal-year earnings indicates 62.1% growth from the year-ago actuals. GCO delivered a trailing four-quarter average earnings surprise of 11.2%.
Designer Brands Inc. DBI designs, produces and retails footwear and accessories. It offers shoes, boots, sandals, sneakers, socks, handbags and accessories. It currently carries a Zacks Rank #2.
The Zacks Consensus Estimate for Designer Brands’ current fiscal-year earnings and sales suggests growth of 225% and 0.6%, respectively, from the year-ago actuals. DBI delivered a trailing four-quarter average earnings surprise of 108.1%.
Urban Outfitters, Inc. URBN is a lifestyle products and services company that sells fashion apparel, accessories, footwear, home goods and related offerings through a portfolio of global consumer brands. The company carries a Zacks Rank #2 at present.
The Zacks Consensus Estimate for Urban Outfitters’ current fiscal-year earnings and sales suggests growth of 14% and 9.5%, respectively, from the year-ago actuals. URBN delivered a trailing four-quarter average earnings surprise of 9.7%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Capri Holdings Limited (CPRI): Free Stock Analysis Report
Urban Outfitters, Inc. (URBN): Free Stock Analysis Report
Genesco Inc. (GCO): Free Stock Analysis Report
Designer Brands Inc. (DBI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).