

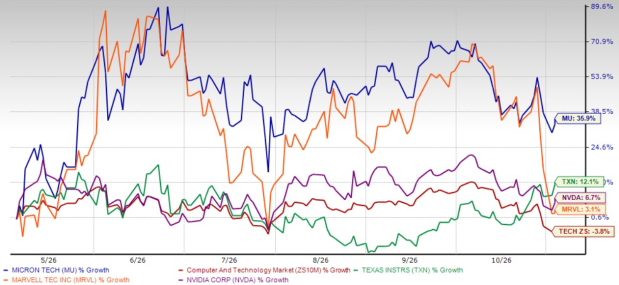
Micron Technology, Inc. MU has delivered an impressive 35.9% gain over the past six months, even as macroeconomic uncertainty and geopolitical tensions have weighed on the broader market. The stock has comfortably outperformed the Zacks Computer and Technology sector, which has declined 3.9% during the same period.
Micron has also outpaced several prominent semiconductor stocks, including Texas Instruments Incorporated TXN, NVIDIA Corporation NVDA and Marvell Technology, Inc. MRVL. Shares of Texas Instruments, NVIDIA and Marvell Technology have gained 12.1%, 6.7% and 3.1%, respectively, over the past six months.
Micron Six-Month Price Return Performance
Image Source: Zacks Investment Research
The strong rally reflects Micron's growing importance in the artificial intelligence (AI) ecosystem. The rapid expansion of AI infrastructure is creating enormous demand for advanced memory chips, particularly high-bandwidth memory (HBM), DRAM and data center solid-state drives (SSDs). With these trends expected to support industry growth for several years, Micron appears well-positioned to benefit.
However, after such a sharp rally, investors may wonder whether the stock still offers an attractive entry point. A closer look at its financial performance, growth opportunities and valuation suggests that Micron's rally may still have room to run.
Micron's Financial Performance Continues to Impress
Micron's fourth-quarter fiscal 2026 results highlight the strength of its current business momentum. The company reported revenues of $54.23 billion, soaring 379% year over year. This marked its sixth consecutive quarterly revenue record.
The bottom line was equally impressive. Non-GAAP earnings per share (EPS) surged to $33.42 from $3.03 in the year-ago quarter. Non-GAAP gross margin expanded significantly to 87% from 45.7%, reflecting strong pricing conditions and a favorable product mix.
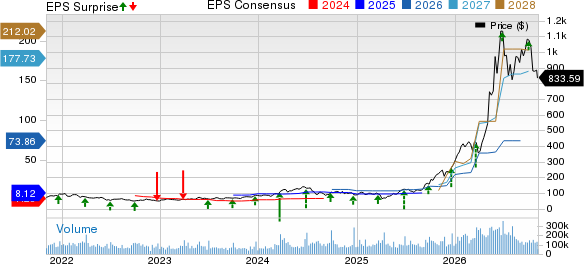
Micron Technology, Inc. Price, Consensus and EPS Surprise
Micron Technology, Inc. price-consensus-eps-surprise-chart | Micron Technology, Inc. Quote
Micron's cash generation also improved considerably. Operating cash flow reached nearly $44 billion in the fourth quarter, taking the full fiscal 2026 figure to $89.68 billion.
Management expects this momentum to continue. For the first quarter of fiscal 2027, Micron projects revenues of $61.5 billion, plus or minus $1.5 billion, and non-GAAP EPS of $38.15, plus or minus $1. These estimates indicate year-over-year growth of approximately 351% in revenues and 698% in earnings.
Such guidance reinforces the view that Micron is operating in an exceptionally strong memory market. While quarterly growth rates of this magnitude may eventually moderate, the company's earnings outlook remains encouraging.
AI Spending Creates a Long Growth Runway for Micron
AI remains the biggest growth opportunity for Micron. Modern AI systems require significantly more memory bandwidth and capacity than traditional computing systems. Training and running increasingly complex AI models require advanced memory solutions, particularly HBM, high-performance DRAM and data center SSDs.
The capital spending plans of major cloud companies strengthen this opportunity. Amazon, Microsoft, Alphabet and Meta Platforms are expected to invest nearly $745 billion in capital expenditures in 2026, with a substantial portion directed toward AI infrastructure.
This spending is important for Micron because AI servers require considerably more memory than conventional servers. As AI models become larger and workloads more complex, memory content per server is likely to increase. This should support demand for Micron's advanced memory products.
Micron's HBM business is already benefiting from this trend. HBM revenues grew faster than total company revenues in the fourth quarter. The company has also secured agreements for most of its 2027 HBM bit supply at significantly higher prices than the previous year. Micron is progressing with its HBM4 production ramp-up and working with NVIDIA on a custom HBM4E solution. These developments could strengthen its position in the high-end AI memory market.
NAND storage is emerging as another important growth driver. Micron's data center SSD revenues came in at $10 billion in the fourth quarter, more than 10 times the year-ago level. Increasing AI workloads and applications such as KV-cache offload are creating additional demand for high-performance storage solutions.
Beyond data centers, physical AI could open another growth avenue. Autonomous vehicles and humanoid robots are expected to require substantially more memory and storage than today's systems. Although this opportunity may take time to develop, it could provide another source of demand later this decade.
Long-Term SCAs Improve Revenue Visibility for Micron
Apart from strong AI demand, Micron is taking steps to make its business more predictable. The company has signed 26 Strategic Customer Agreements (SCAs), which it expects to cover more than 35% of its revenues through 2030. Financial commitments from customers under these agreements have increased to $32 billion, with most of the amount backed by cash deposits.
These take-or-pay agreements are important because they provide Micron with better visibility into future demand and help the company plan its manufacturing capacity more efficiently. They also strengthen relationships with major customers and support long-term technology collaboration.
Micron is also investing heavily to expand its manufacturing and packaging capabilities across the United States, Singapore, Japan and Taiwan. Its ID1 fabrication facility is expected to begin wafer output in mid-2027, while its Singapore HBM packaging facility is expected to start initial production in early 2027. These investments should help Micron address growing demand and strengthen its position in advanced memory manufacturing.
Micron's Valuation Still Looks Attractive
Despite its impressive rally, Micron's valuation remains relatively low. The stock currently trades at a forward 12-month price-to-earnings (P/E) multiple of just 4.65, significantly below the sector average of 17.09.
Micron Forward 12-Month P/E Ratio
Image Source: Zacks Investment Research
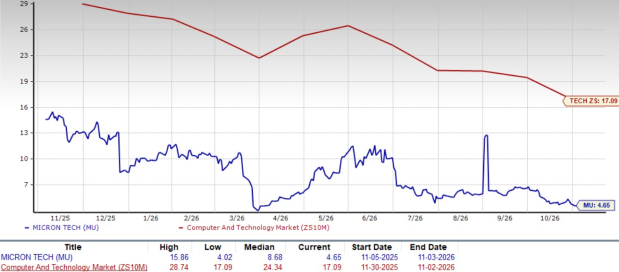
Micron also looks inexpensive compared with several semiconductor peers. Texas Instruments, Marvell Technology and NVIDIA trade at a forward P/E multiple of 29.02, 26.05 and 14.57, respectively.
This valuation gap is particularly interesting, given Micron's exceptional earnings growth and strong position in the AI memory market.
Final Thoughts: Micron Stock Still Worth Buying
Micron's 35.9% rally over the past six months reflects a significant improvement in its business fundamentals. Strong AI-related memory demand, rising HBM revenues, favorable pricing conditions and robust cash generation have transformed its earnings outlook.
The company's long-term customer agreements also provide better revenue visibility, while investments in manufacturing and packaging capacity should help it capture future demand.
Micron's growth prospects remain compelling, and its valuation looks attractive relative to its earnings potential and semiconductor peers. Given the strong demand outlook and improving fundamentals, investors should consider buying MU stock at current levels for long-term gains.
Micron currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Micron Technology, Inc. (MU): Free Stock Analysis Report
Texas Instruments Incorporated (TXN): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Marvell Technology, Inc. (MRVL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).