

Western Digital Corporation WDC is pairing faster earnings growth with widening margins and sustained cloud-storage demand. Fiscal first-quarter 2027 results exceeded expectations, and management expects another step up in the December quarter.
The trade-off is valuation and execution. WDC already carries a premium to its sub-industry and historical median, while its ePMR-to-HAMR roadmap still depends on customer qualifications, manufacturing readiness and disciplined supply execution.
WDC’s Earnings Momentum Strengthens the Bull Case
Western Digital reported fiscal first-quarter 2027 revenues of $4.38 billion, up 55% year over year. Non-GAAP earnings rose 161% to $4.64 per share. Earnings beat the Zacks Consensus Estimate by 13.5%, while revenues topped the consensus mark by 5.2%.
Image Source: Zacks Investment Research
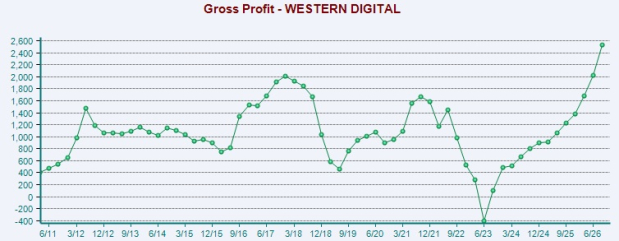
Management expects fiscal second-quarter revenues of about $5.1 billion, plus or minus $100 million, and non-GAAP earnings of $5.80 per share, plus or minus 20 cents. Guidance also calls for a 60-61% non-GAAP gross margin, extending the profitability gains visible in the first quarter.
Western Digital’s Valuation Leaves Less Room for Error
WDC trades at 11.5X forward 12-month earnings, compared with 7.05X for the Zacks sub-industry and its own five-year median of 9.75X. That premium indicates that investors already expect a substantial portion of the earnings improvement to persist.
The valuation increases the importance of pricing, demand and product execution. A slowdown in exabyte growth, weaker pricing or delays in higher-capacity product ramps could make the current multiple harder to sustain, even if the long-term storage demand backdrop remains constructive.
WDC’s Technology Roadmap Adds Execution Risk
Western Digital is ramping next-generation ePMR drives with capacities of up to 40 terabytes. Management expects the platform to approach 30% of nearline shipments in the fiscal second quarter and 50% in the third quarter. First-generation HAMR qualifications with two hyperscale customers are expected to finish in the first quarter of calendar 2027, followed by volume shipments in the first half.
Second-generation HAMR qualification is scheduled to begin in the second half of calendar 2027. Product validation, reliable manufacturing yields and supply-chain readiness remain important. Seagate Technology Holdings plc STX is also advancing HAMR through its Mozaic platform, while NetApp, Inc. NTAP is benefiting from AI and hybrid multicloud infrastructure demand, underscoring broader investment in data storage.
Western Digital’s Cash Flow Supports Capital Returns
Western Digital generated $3.51 billion of free cash flow in fiscal 2026, up 145% year over year, with a 27% free cash flow margin. First-quarter fiscal 2027 free cash flow reached $1.38 billion, up 130%, while the company ended the quarter with a net cash position of roughly $500 million.
WDC repurchased about $1 billion of common stock and paid $56 million in dividends during the quarter. The board also raised the quarterly dividend 17% to 17.5 cents per share, while management continues to fund investments in heads, media technology and factory automation.
WDC’s Ratings Favor Growth Over Value
WDC’s operating momentum supports a favorable near-term setup, but the valuation premium and technology-transition requirements argue for selectivity. Investors focused on earnings growth and momentum have more support here than those seeking a discounted entry point.
Western Digital currently carries a Zacks Rank #1 (Strong Buy). Its Growth Score of B and Momentum Score of B align with favorable growth and price-trend characteristics, while the Value Score of D signals weaker value attributes. The VGM Score of C captures that mixed profile. The ratings favor the stock’s current growth and momentum case, but valuation-sensitive investors may still prefer a wider margin of safety. You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Western Digital Corporation (WDC): Free Stock Analysis Report
NetApp, Inc. (NTAP): Free Stock Analysis Report
Seagate Technology Holdings PLC (STX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).