

Envista Holdings Corporation NVST raised its 2026 earnings outlook following third-quarter results, supported by productivity improvements, pricing initiatives and growth across most major markets.
Management emphasized sustained margin expansion and product commercialization while addressing China's upcoming volume-based procurement (VBP) reforms, which could pressure pricing and profitability in 2027.
NVST Beats Earnings & Revenue Estimates
Envista reported third-quarter 2026 adjusted earnings of $0.40 per share, beating the Zacks Consensus Estimate of $0.35. Earnings increased 25% from $0.32 in the prior-year quarter.
Revenues reached $691.50 million, surpassing the Zacks Consensus Estimate of $686.31 million. Sales increased 3.2% year over year, while core sales advanced 2.7%.
Envista Holdings Corporation Price, Consensus and EPS Surprise
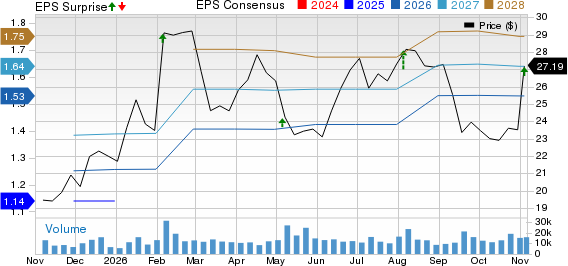
Envista Holdings Corporation price-consensus-eps-surprise-chart | Envista Holdings Corporation Quote
CEO Paul Keel attributed the performance to broad-based growth and improved operational execution. Adjusted EBITDA increased 9%, reflecting productivity gains and pricing contributions.
NVST Raises 2026 Earnings Outlook
Envista increased its 2026 adjusted EPS guidance to $1.54-$1.58 from $1.50-$1.55. Adjusted EBITDA growth expectations rose to 12.5%-14% from 11%-14%.
Core sales growth guidance narrowed to 3.75%-4.25% from 3.5%-4.5%. CEO Paul Keel attributed the improved earnings outlook to operational execution and continued profitability gains.
CFO Eric Hammes explained that fourth-quarter core growth would be slightly negative at the guidance midpoint, reflecting four fewer selling days. Excluding this calendar effect, underlying growth would align with full-year expectations.
Envista Faces China Pricing Pressure
China remained a significant discussion point as orthodontics distributors reduced inventories ahead of government VBP reforms. The resulting revenue headwind totaled approximately $7 million during the quarter.
During questions from Baird, Keel clarified that channel destocking and future price reductions represent separate challenges. Management anticipates orthodontics pricing declines of approximately 50% and implant pricing reductions of 10%-15% following implementation.
Keel expects additional market share and procedure volumes to support Chinese revenue growth. However, he acknowledged that VBP would pressure local margins, with implementation anticipated during the first half of 2027.
NVST Targets Further Margin Expansion
Operational improvements remained central to management's outlook. Adjusted EBITDA margin expanded 80 basis points to 15.3%, supported by pricing, factory productivity and procurement efficiencies.
Hammes reported approximately $12 million in positive pricing contributions, alongside $2 million from net productivity. These benefits helped offset approximately $6 million in incremental investments supporting future growth.
During Stifel's questioning, Keel expressed confidence that profitability improvements outside China would outweigh VBP-related margin pressure. Management consequently expects consolidated gross and EBITDA margin expansion to continue in 2027.
Envista Expands Innovation and Commercialization
New product development remains a major growth priority. Keel highlighted introductions spanning diagnostic imaging, orthodontics and dental technologies, including NOMAD Pro 3 and the AI-assisted DTX Studio Endo Module.
Spark clear aligners delivered high-single-digit growth, outperforming management's mid-single-digit estimate for category growth. Diagnostics and implants recorded mid-single-digit growth, while consumables advanced at a low-single-digit rate.
Responding to Leerink Partners, Keel emphasized commercialization through geographic expansion, customer segmentation and distribution partnerships. He also identified Envista's installed imaging base and integrated hardware, software and services as competitive advantages.
NVST Balances Acquisitions and Share Repurchases
Capital allocation attracted attention during BMO Capital Markets' questioning. Hammes reaffirmed organic investment as the company's foremost priority, followed by acquisitions and shareholder returns.
Management continues evaluating acquisitions that complement existing products or expand geographic reach. Recent implant-focused acquisitions have performed well, supporting continued interest in selective transactions.
Envista repurchased approximately $10 million in shares during the quarter. Hammes indicated that shareholder returns would generally represent about one-third of annual free cash flow, preserving flexibility for investment and acquisitions.
Envista Maintains Focus on Execution
Management characterized dental market conditions as broadly unchanged, with U.S. demand remaining soft and elective procedures facing pressure. Developing markets outside China and Europe continued delivering stronger growth.
Keel's closing remarks reinforced the company's focus on growth, operational productivity and people. Entering 2027, management intends to prioritize commercialization, manufacturing efficiencies and sustained profitability despite macroeconomic and regulatory challenges.
What NVST's Zacks Rank & Style Scores Indicate
NVST currently carries a Zacks Rank #4 (Sell), reflecting an unfavorable earnings estimate revision outlook. Its Value Score of B and Momentum Score of B indicate relatively attractive characteristics in those investment styles.
However, its Growth Score of D highlights weaker growth characteristics, while its VGM Score of C reflects a mixed overall profile. The favorable individual scores do not offset the less favorable Zacks Rank. The rank can change as analysts revise earnings estimates following the latest quarterly results.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Envista Holdings Corporation (NVST): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).