

Axon Enterprise, Inc. AXON emphasized accelerating software adoption, expanding Artificial Intelligence capabilities and a major drone investment during its third-quarter 2026 earnings call. However, delayed federal counter-drone deployments prompted management to reduce its annual revenue outlook.
Despite robust underlying demand, the company faces challenges involving government procurement timing, hardware costs and elevated inventory spending.
AXON Lowers 2026 Revenue Outlook
Axon now expects fourth-quarter revenues between $990 million and $1.01 billion, implying full-year revenues of $3.61-$3.63 billion and approximately 30% annual growth. Its previous forecast called for 32% to 34% growth.
President Joshua Isner attributed the reduction to three delayed federal Dedrone deployments representing approximately $130 million in expected 2026 revenues.
Isner explained that procurement approvals, installation requirements and deployment schedules have increased revenue timing uncertainty. Management excluded these projects from updated guidance while maintaining confidence in underlying demand.
Axon Earnings and Revenues Miss Estimates
AXON reported third-quarter adjusted earnings of $1.72 per share, missing the Zacks Consensus Estimate of $1.90 by 9.50%. Adjusted earnings increased from $1.24 in the year-ago quarter.
Axon Enterprise, Inc Price, Consensus and EPS Surprise
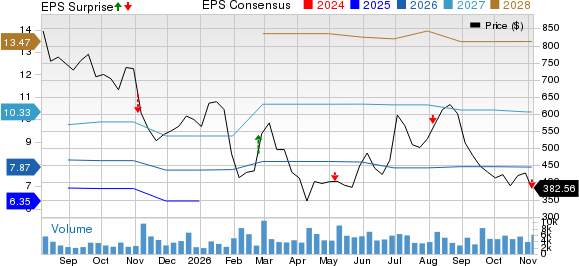
Axon Enterprise, Inc price-consensus-eps-surprise-chart | Axon Enterprise, Inc Quote
Quarterly revenues reached $908.6 million, up approximately 28% year over year but below the Zacks Consensus Estimate of $931.1 million. The revenue shortfall represented a 2.40% negative surprise.
COO and CFO Brittany Bagley highlighted adjusted EBITDA growth of 33% to $236 million, with a 25.9% margin. However, adjusted gross margin declined to 59.2% from 62.7%, reflecting product mix and higher component costs.
AXON Software Growth Accelerates
Bagley identified Software & Services as the quarter's standout business. Segment revenues increased 43% year over year to $437 million, approaching half of consolidated revenues.
Annual recurring revenues increased 40% to $1.75 billion, while net revenue retention remained at 126%. AI annual recurring revenues surpassed $100 million, reflecting adoption of premium offerings.
Real-time operations, Axon Records, AI, Axon 911 and Dedrone software collectively achieved an annual revenue run rate approaching $500 million, more than doubling year over year.
Axon Expands Drone Strategy Through Skydio
Founder and CEO Patrick Smith discussed Axon's additional $1.2 billion investment in Skydio, increasing its fully diluted ownership to 37%.
The agreement also establishes Axon as Skydio's exclusive public safety distributor across the United States and Canada, strengthening its integrated drone response offering.
During questioning from JPMorgan, Smith defended maintaining Skydio's independence rather than pursuing complete ownership. He emphasized that the structure allows both companies to expand their capabilities while concentrating on their respective operations.
AXON Faces Margin and Cash Flow Pressures
Bagley noted that elevated memory costs and counter-drone hardware mix pressured profitability. Management expects memory-related headwinds to persist through 2027 and 2028.
Operating cash flow declined to $20 million from $60 million a year earlier. Free cash flow was negative $19 million, reflecting approximately $100 million of strategic inventory investment during the quarter.
Full-year free cash flow guidance decreased to $350-$400 million from $450 million. During questioning from Citizens JMP Securities, Isner reiterated confidence that inventory accumulation would moderate in early 2027.
Axon Addresses Growth Questions From Analysts
During questioning from Piper Sandler, management clarified that federal Dedrone delays primarily reflected procurement timing rather than deteriorating customer demand.
Responding to Barclays, Bagley explained that the upcoming Axon Body 5 launch could temporarily affect first-quarter 2027 purchasing before supporting another hardware upgrade cycle.
In response to Baird, Bagley maintained expectations for double-digit TASER growth, supported by TASER 10 adoption and the newly introduced TASER Ion.
AXON Maintains Focus on Long-Term Expansion
Management maintained an expansion-oriented approach despite near-term revenue uncertainty, emphasizing software subscriptions, AI capabilities and counter-drone opportunities.
Axon's future contracted bookings reached $15.8 billion, increasing 39% year over year. Executives emphasized execution, product availability and disciplined forecasting as priorities entering 2027.
Axon Zacks Rank and Style Scores Signal Caution
AXON currently carries a Zacks Rank #3 (Hold), indicating a neutral near-term outlook under the earnings-estimate-revision-based ranking system.You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Its Value Score of F, Growth Score of D, Momentum Score of F and combined VGM Score of F indicate unfavorable characteristics across the evaluated investment styles. These scores do not provide the stronger combination generally associated with top-ranked stocks carrying A or B grades.
The Zacks Rank can change as analysts revise earnings estimates following the recently reported results, potentially altering the stock's near-term assessment.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Axon Enterprise, Inc (AXON): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).