

AI is driving demand for computing power, but is also creating a growing need for data storage. As cloud providers, AI developers and enterprises generate and retain more data, Western Digital Corporation WDC is positioned to benefit from rising demand for high-capacity HDDs. Robust cloud demand, higher pricing and a shift toward higher-capacity drives fueled substantial revenue and earnings growth in the fiscal first quarter. Cloud revenue, which accounted for 88% of total sales, increased 54% year over year to $3.9 billion, underscoring the importance of hyperscale cloud providers and other large customers investing in storage infrastructure.
AI adoption is driving a surge in data creation and storage needs. Inference and agentic AI are generating increasing volumes of logs, model outputs and performance data, while physical AI applications, including robotics, factory automation and autonomous vehicles, are adding to storage demand through data- and video-intensive workloads. Western Digital is advancing its technology roadmap and transition to higher-capacity drives. Its latest ePMR platform, offering up to 40TB, is seeing strong production and customer adoption. It expects these drives to account for nearly 30% of nearline shipments in the fiscal second quarter and 50% in the fiscal third quarter, supporting continued growth in exabyte shipments through fiscal 2027 and beyond.
Meanwhile, innovations such as high-bandwidth HDDs and dual-pivot technology aim to expand the role of hard drives in cloud and AI infrastructure by addressing growing capacity and performance needs.
WDC expects its momentum to continue into the second quarter of fiscal 2027. Management guided revenue of $5.1 billion (+/- $100 million), representing a sequential increase of 16% and a year-over-year rise of 69%. It also reported a net cash position of approximately $500 million and returned $1.1 billion to shareholders through dividends and share repurchases. Its board raised the quarterly dividend by 17% to 17.5 cents per share. Long-term demand visibility is another positive. Management highlighted that its seven largest customers have planning visibility extending into 2030 and 2031. While such visibility does not guarantee future orders, it suggests that major customers are making extended infrastructure plans.
Is WDC's AI Growth at Risk From Rising Competition?
Seagate Technology Holdings plc STX is benefiting from increasing data creation, retention and reuse across cloud and enterprise environments. AI inference and agentic applications require persistent historical context, reinforcing the role of cost-efficient HDDs in tiered storage architectures. Cloud revenue has risen for 12 consecutive quarters, while enterprise OEM revenue advanced for six straight quarters. Most nearline exabyte supply is allocated through calendar 2028, with some cloud agreements extending through 2030. Build-to-order contracts establish configurations and pricing through calendar 2027, while 2028 terms are expected to be finalized over the coming quarters. Management expects near-line exabyte supply growth in the mid-20% range on a compound basis, supporting long-term revenue visibility.
NetApp, Inc. NTAP is benefiting from higher enterprise spending on AI-ready storage, with all-flash, Public Cloud and Keystone demand broadening across customer types. NetApp is positioning its unified data platform to activate enterprise data for AI without requiring data movement, recording more than 1,100 AI and data preparation wins in fiscal 2026. In first-quarter fiscal 2027, it added about 350 AI and data lake modernization deals. DataPelago adds in-place data processing capabilities, while AFX and the AI Data Engine target high-performance AI workloads and governed data access. AI is also driving broader modernization of databases and unstructured data environments, expanding the opportunity beyond dedicated AI infrastructure.
WDC Price Performance, Valuation and Estimates
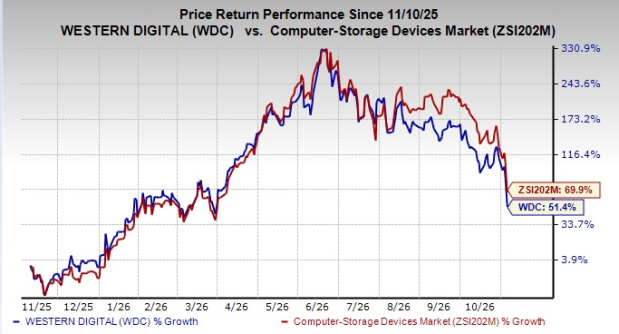
In the past year, shares of WDC have surged 51.4% compared with the Zacks Computer-Storage Devices industry’s growth of 69.9%.
Image Source: Zacks Investment Research
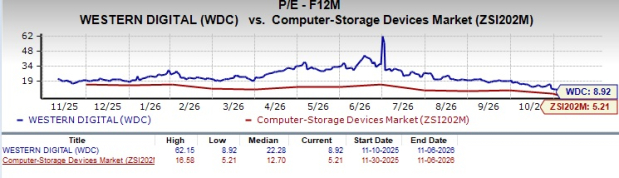
Going by the price/earnings ratio, the company’s shares currently trade at 8.92 times forward earnings compared with 5.21 for the industry.
Image Source: Zacks Investment Research
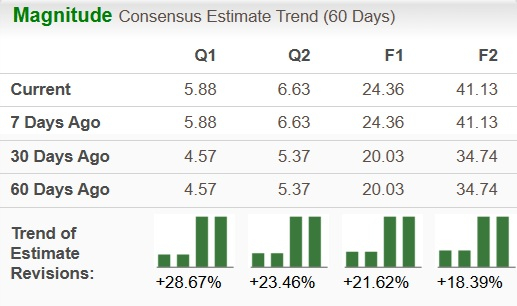
WDC’s estimate revisions are currently on an upward trajectory. The Zacks Consensus Estimate for its earnings for fiscal 2027 has been revised upward by 21.6% to $24.36 over the past 60 days, while the same for fiscal 2028 has gone up 18.4% to $41.13.
Image Source: Zacks Investment Research
Currently, Western Digital has a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Western Digital Corporation (WDC): Free Stock Analysis Report
NetApp, Inc. (NTAP): Free Stock Analysis Report
Seagate Technology Holdings PLC (STX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).