

Target Hospitality Corp. TH emphasized accelerating contract execution, expanding workforce accommodations demand and improving operating leverage during its third-quarter 2026 earnings call. Management highlighted substantial growth in its Workforce Hospitality Solutions (WHS) business, supported by infrastructure development projects.
The company reaffirmed its 2026 financial outlook and outlined expectations for continued revenue and EBITDA expansion through 2027, backed by existing contracts and a growing commercial pipeline.
TH Reports Revenue Beat Amid Earnings Pressure
TH reported third-quarter revenues of $129.1 million, exceeding the Zacks Consensus Estimate of $120.2 million by 7.40%. Revenues increased 30% year over year and 51% sequentially.
Reported earnings were a loss of eight cents per share, compared with the Zacks Consensus Estimate of breakeven earnings. On a GAAP basis, the company reported a loss of nine cents per share.
Target Hospitality Corp. Price, Consensus and EPS Surprise
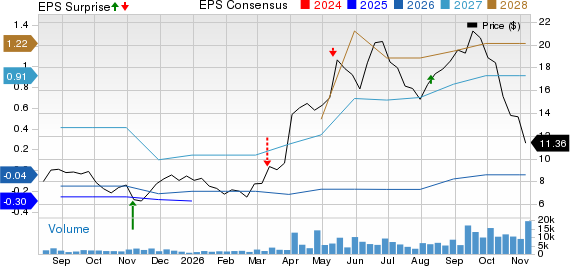
Target Hospitality Corp. price-consensus-eps-surprise-chart | Target Hospitality Corp. Quote
Chief financial officer Jason Vlacich attributed revenue growth to expanding WHS contributions. Adjusted EBITDA increased 59% year over year to $34.2 million, while the adjusted EBITDA margin expanded approximately 480 basis points to 27%.
Target Expands Its Workforce Hospitality Business
President and CEO Brad Archer emphasized the company's growing presence in critical infrastructure markets, including AI data centers and power generation facilities.
Since January 2026, Target secured more than $1.7 billion in multiyear contract awards representing more than 10,000 beds. WHS utilized beds exceeded 6,200 during the quarter.
The WHS segment generated $79.5 million in revenues, increasing 116% year over year. Archer expects utilized beds to grow at a double-digit quarterly rate through mid-2027 as additional contracted communities become operational.
TH Reaffirms Outlook and Sets 2027 Targets
Management reaffirmed its full-year 2026 revenue guidance of $435-$445 million and adjusted EBITDA expectations of $105-$115 million.
Capital expenditures are projected between $490 million and $510 million, excluding acquisitions. Vlacich explained that customer advance payments are helping fund investments supporting long-term contracts.
Looking further ahead, management expects annualized revenues exceeding $750 million and adjusted EBITDA above $300 million exiting 2027. These projections rely entirely on existing contracts, excluding prospective awards and additional variable revenue opportunities.
Target Addresses Contract Protections and Pipeline
During the analyst discussion, Stifel questioned the strength of contractual protections and assumptions underlying the company's 2027 outlook.
Vlacich explained that recently awarded contracts generally carry four- to five-year terms with minimum revenue guarantees. Cancellation provisions protect capital recovery, provide additional compensation and allow Target to retain equipment ownership.
Oppenheimer also sought clarification on the commercial pipeline, which expanded beyond 25,000 beds from 20,000 previously. Archer highlighted geographically diverse opportunities across multiple customers, with advanced negotiations involving projects that have secured necessary permits.
TH Sees Additional Services Supporting Margins
Northland Capital Markets questioned management about opportunities to expand service offerings within existing customer relationships.
Archer identified transportation, job-site catering, security and enhanced site development as potential sources of incremental revenues. These offerings extend Target's presence beyond workforce accommodations.
Responding to Deutsche Bank, Vlacich said these enhanced services carry profitability broadly consistent with WHS adjusted gross margins of approximately 50%. Archer added that certain services require relatively limited capital investment.
Target Balances Investment With Financial Flexibility
Management maintained an execution-focused stance, emphasizing disciplined capital deployment and contracted revenue visibility.
Vlacich expects leverage to rise temporarily during community construction before declining as operating cash generation increases. The company anticipates exiting 2027 with net leverage well below 2x, while prioritizing WHS expansion and financial flexibility.
What TH's Zacks Rank and Style Scores Indicate
TH currently carries a Zacks Rank #2 (Buy), indicating favorable near-term prospects under the Zacks earnings estimate revision framework. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Its Growth Score of A reflects attractive growth characteristics, while its Momentum Score of B signals favorable price momentum characteristics.
However, the Value Score of D indicates comparatively weaker valuation characteristics. The VGM Score of B combines the company's value, growth and momentum attributes into a favorable overall assessment. The combination of a Zacks Rank #2 (Buy) and VGM Score of B aligns with the framework's preferred screening characteristics, although the Zacks Rank may change as analysts revise earnings estimates following the latest quarterly results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Target Hospitality Corp. (TH): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).