

Somnigroup International Inc. SGI reported third-quarter 2026 adjusted earnings of $1.04 per share, up 9.5% year over year but missing the Zacks Consensus Estimate of $1.06. Net sales increased 10.8% to $2.35 billion but missed the consensus mark of $2.42 billion.
The top line benefited from the Leggett & Platt acquisition, while weaker Mattress Firm sales and operational disruptions at Dreams weighed on performance. Mattress Firm's same-store sales declined 2%, reflecting challenging consumer demand.
Somnigroup International Inc. Price, Consensus and EPS Surprise
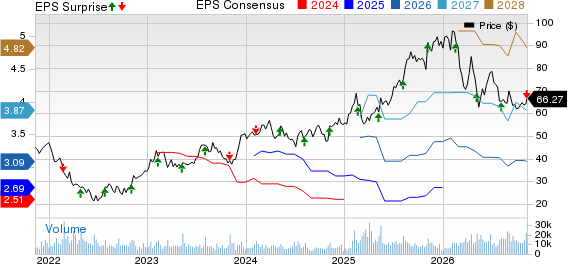
Somnigroup International Inc. price-consensus-eps-surprise-chart | Somnigroup International Inc. Quote
SGI's Margin Picture Reflects Acquisition Costs
Gross margin contracted 290 basis points (bps) year over year to 42%, while adjusted gross margin declined 260 bps to 43%.
Operating income declined 5.5% to $297.4 million, primarily due to acquisition-related costs. However, adjusted operating income increased 6% to a record $364.2 million. Adjusted operating margin contracted 70 bps to 15.5%.
Adjusted EBITDA increased 6.8% to a record $447.5 million. The company benefited from acquisition synergies and approximately $20 million in tariff refunds, although higher transportation costs and operational challenges at Dreams partially offset these gains.
Somnigroup's Mattress Firm Sales Decline in Q3
Mattress Firm generated net sales of $1.01 billion, down 5.8% from $1.07 billion a year earlier, primarily due to softer online sales. Management attributed part of the online weakness to advertising investments shifting toward driving in-store traffic.
Adjusted gross margin declined 100 bps to 34.6%, reflecting store investments and higher consumer financing costs, partially offset by synergies. Adjusted operating margin improved 20 bps to 9.6%, supported by favorable cooperative advertising expenses.
The company plans to begin expanding Mattress Firm's retail footprint in 2027, targeting more than 2,500 locations over time. Management expects an enterprise-wide payback period of approximately 1.5 years per new store.
SGI's North America Margins Expand
Tempur Sealy North America reported net sales of $693.1 million, down 5.8% year over year. Wholesale bedding and furnishings sales declined 7.2% to $581.5 million, while direct bedding sales increased 1.7% to $111.6 million.
On a like-for-like basis, North American sales declined 4%, reflecting continued industry weakness. However, the direct channel benefited from improved customer conversion and stronger retail execution.
Adjusted gross margin expanded 690 bps to 65.5%, primarily driven by tariff refunds and Mattress Firm acquisition synergies. Adjusted operating margin improved 450 bps to 34%, with higher cooperative advertising investments partly offsetting gross margin gains.
Somnigroup's International Business Faces Headwinds in Q3
Tempur Sealy International sales declined 12.3% to $276.8 million, while constant-currency sales decreased 11.7%. Wholesale sales increased 3.5% to $116.9 million, whereas direct sales fell 21.2% to $159.9 million.
Dreams experienced a 34.7% sales decline following implementation of a new enterprise resource planning system, which disrupted manufacturing and deliveries. Management estimated the disruption's year-over-year impact at approximately $50 million in sales and $25 million in adjusted EBITDA. Excluding Dreams, International sales grew at a high-single-digit rate.
International gross margin contracted 360 bps to 45.5%, while operating margin declined 870 bps to 9.4%, reflecting operating deleverage and unfavorable product mix.
SGI's Leggett Acquisition Adds to Sales
Leggett contributed $372.6 million in sales following the acquisition's completion on Aug. 26, 2026. Wholesale bedding and furnishings generated $271.3 million, while specialized products contributed $101.3 million.
The acquired business recorded an adjusted gross margin of 21.9% and an adjusted operating margin of 11%. On a full-quarter, like-for-like basis, Leggett generated $973 million in sales, including intercompany transactions. Strength in trade, rod and wire, and geotextiles helped offset weakness in residential and automotive markets.
Somnigroup's Cash Flow Strengthens, Outlook Cut
Somnigroup generated operating cash flow of $349 million and free cash flow of $290 million during the quarter. It ended September with $612.1 million in cash and cash equivalents and consolidated indebtedness less netted cash of approximately $5 billion. Leverage improved to 2.69 times.
The company lowered its 2026 adjusted earnings guidance to $2.85-$2.95 per share from $2.85-$3.15. The revised outlook assumes approximately $8.65 billion in sales and adjusted EBITDA of $1.4 billion at the respective midpoints.
Management expects the global bedding industry to decline by a mid-single-digit percentage in the second half of 2026. Capital expenditures are projected at approximately $255 million, including $75 million for Mattress Firm store refreshes and brand-wall installations.
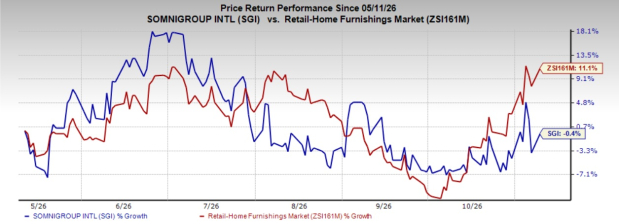
Somnigroup's shares have lost 0.4% in the past six months against the industry’s 11.1% growth. SGI currently has a Zacks Rank #4 (Sell).
Image Source: Zacks Investment Research
Stocks Looking Red Hot
Williams-Sonoma, Inc. WSM, which operates as an omni-channel specialty retailer of various products for home, currently carries a Zacks Rank of 2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Zacks Consensus Estimate for Williams-Sonoma’s current fiscal-year sales and EPS implies growth of 4.1% and 7.5%, respectively, from the year-ago figures. WSM delivered a trailing four-quarter earnings surprise of 4.9%, on average.
Target Corporation TGT, which operates as a general merchandise retailer, currently carries a Zacks Rank #2. TGT delivered a trailing four-quarter earnings surprise of 10.5%, on average.
The Zacks Consensus Estimate for Target’s current fiscal-year sales and EPS implies growth of 4.6% and 39%, respectively, from the year-ago figures.
Wayfair Inc. W, a leading online retailer of furniture and home goods, currently carries a Zacks Rank #2. Wayfair delivered a trailing four-quarter earnings surprise of 11.5%, on average.
The Zacks Consensus Estimate for Wayfair’s current fiscal-year sales and EPS calls for growth of 7.9% and 15.4%, respectively, from the year-ago figures.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Somnigroup International Inc. (SGI): Free Stock Analysis Report
Target Corporation (TGT): Free Stock Analysis Report
Williams-Sonoma, Inc. (WSM): Free Stock Analysis Report
Wayfair Inc. (W): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).