

Cipher Digital Inc. CIFR is shifting from Bitcoin mining toward contracted high-performance computing (HPC) infrastructure. This transition makes the stock harder to value on current revenues alone, but it also creates a growing base of long-term lease commitments.
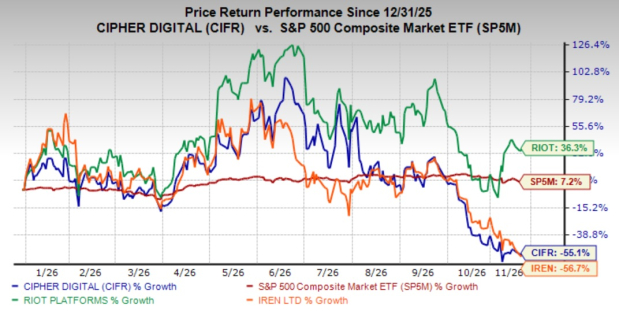
However, the market has been less forgiving. So far in the year, CIFR has declined roughly 55%. After the third-quarter results, shares jumped 18.4% on Nov. 3, then fell over the next two sessions. By Nov. 17, they were about 6% below the Nov. 2 close.
Still, the comparison with IREN Limited IREN and Riot Platforms, Inc. RIOT shows that investors have become selective. IREN stock was down about 56% year to date through Nov. 17, while RIOT was up roughly 36%, reflecting different views on execution, financing and the timing of AI-related revenues. Cipher will need to prove that its long-term colocation model can produce attractive returns without excessive equity funding.
However, the question is whether the selloff discounts too much execution risk. Cipher reported its first HPC lease revenues, progress at Black Pearl and Barber Lake, and a 5.9-GW near-term pipeline. The Barber Lake amendment lifted contracted revenues to $9.1 billion, improving the setup even as funding and construction risks remain.
Image Source: Zacks Investment Research
Cipher's Q3 Results Reflect Its Business Transition
Cipher’s third-quarter numbers looked weak on the surface. Revenues fell 62.8% year over year to $26.7 million, largely because Bitcoin-mining revenues declined to $20.8 million from $71.7 million. However, the quarter also included $5.9 million of first HPC leasing revenues. Adjusted EBITDA remained negative at $10.0 million, showing that the new business is still in its early ramp-up.
Long-Term HPC Contracts Strengthen Growth Visibility for CIFR
More important is the contracted base. Cipher now has 700 MW of contracted HPC capacity across Barber Lake, Black Pearl and Stingray, with $16.6 billion of contracted revenues and a weighted average lease term of 17.3 years. Projected average annualized NOI is about $864 million. Barber Lake was especially important: its amended lease doubled the base term to 20 years and lifted contracted revenues to $9.1 billion, adding $5.2 billion of incremental rent.
Cipher's Data Center Expansion Supports Future Revenue Growth
Execution remains the main test. Black Pearl delivered its first 18 MW of critical IT capacity in August, while Barber Lake is scheduled to bring data halls online from the fourth quarter of 2026 through the first quarter of 2027. Stingray’s shell is expected to be completed in the fourth quarter. Cipher is also developing natural-gas lateral pipelines that could support up to 2.5 GW of on-site generation, potentially improving time-to-power for future customers.
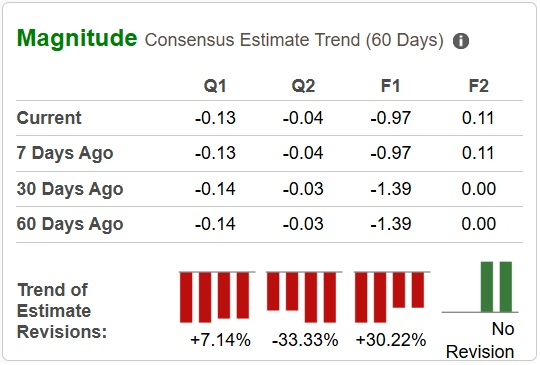
The Zacks Consensus Estimates for CIFR’s 2026 and 2027 earnings have improved in the past 30 days.
Image Source: Zacks Investment Research
High Debt and Execution Risks Remain Key Concerns for Cipher
The funding picture is more mixed. Cipher had $6.7 billion of total debt and $3.1 billion of net debt on a pro forma basis, alongside about $724 million of unrestricted cash. The company raised $850 million of 0% convertible notes after quarter-end to help fund Barber Lake and equitized about $166 million of older converts. The capped call provides protection against dilution below $28.35 per share, but the financing still highlights the capital intensity of the strategy.
CIFR’s Growth Outlook Depends on Timely Project Execution
The next few quarters are expected to show whether Cipher can turn its contracted portfolio into visible operating revenues. Successful deliveries at Black Pearl and Barber Lake would provide a clearer link between its long-term contracts and reported results. New leases at Reveille, Ulysses or Colchis are also expected to support the growth story, especially if structured with better cost protection.
CIFR Cheaper Than RIOT, but Not as Cheap as IREN
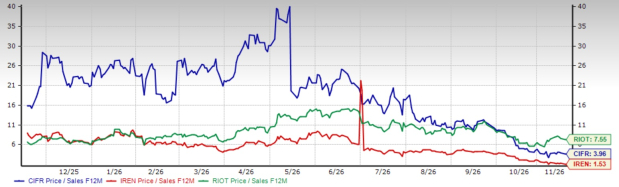
On a forward 12-month price-to-sales (P/S) basis, CIFR trades at 3.96X, significantly below RIOT at 7.55X, but ahead of IREN at 1.53X.
This puts Cipher in the middle of the peer group. The discount to RIOT suggests the market is assigning less value to Cipher’s contracted HPC pipeline, while the premium to IREN reflects differences in business mix, revenue timing and funding concerns. Cipher’s multiple is no longer extreme, but it is not low enough to remove execution risk. The valuation case improves if signed capacity begins converting into recurring rent on schedule and new leases add visibility.
Valuation: Forward 12-month Price-to-Sales (P/S) Basis
Image Source: Zacks Investment Research
Conclusion: Is CIFR's Selloff Overdone?
Cipher Digital's year-to-date decline appears to reflect concerns over financing, construction costs and the pace of its HPC transition. However, its expanding contracted revenue base, long-term leases and progress across major data center projects provide meaningful growth opportunities. The company's strong development pipeline could support future revenue visibility as additional capacity becomes operational.
Nevertheless, elevated debt, execution challenges and potential shareholder dilution warrant caution. While the recent correction has made CIFR's valuation relatively more attractive, investors may prefer to maintain their existing positions and await clearer signs of revenue growth, improving profitability and successful project execution before increasing exposure.
At present, CIFR carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Discover the Stocks Our Experts Want to Own This Quarter
Each quarter, four Zacks editors compile their favorite stocks into one report. As a sign of the times, three of this quarter's picks can potentially cash in on the massive AI boom. One grew its commercial revenue more than 140% last quarter.
The fourth stock is an online retailer posting its most significant growth since the pandemic. Its shares jumped more than 25% after its last earnings report, then pulled back, giving investors a chance to capitalize on what could be a longer-term bullish trend.
Get Your Free Ultimate Four Report >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Cipher Digital Inc. (CIFR): Free Stock Analysis Report
Riot Platforms, Inc. (RIOT): Free Stock Analysis Report
IREN Limited (IREN): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).