

Dell (DELL) doesn’t have the same glamour as Apple (AAPL), but there was a time when the two were battling for attention with their PCs and laptops. Today, their stories look very different. While Apple is grabbing headlines with its latest products such as the foldable iPhone Duo, Dell has quietly transformed itself into an AI infrastructure powerhouse.
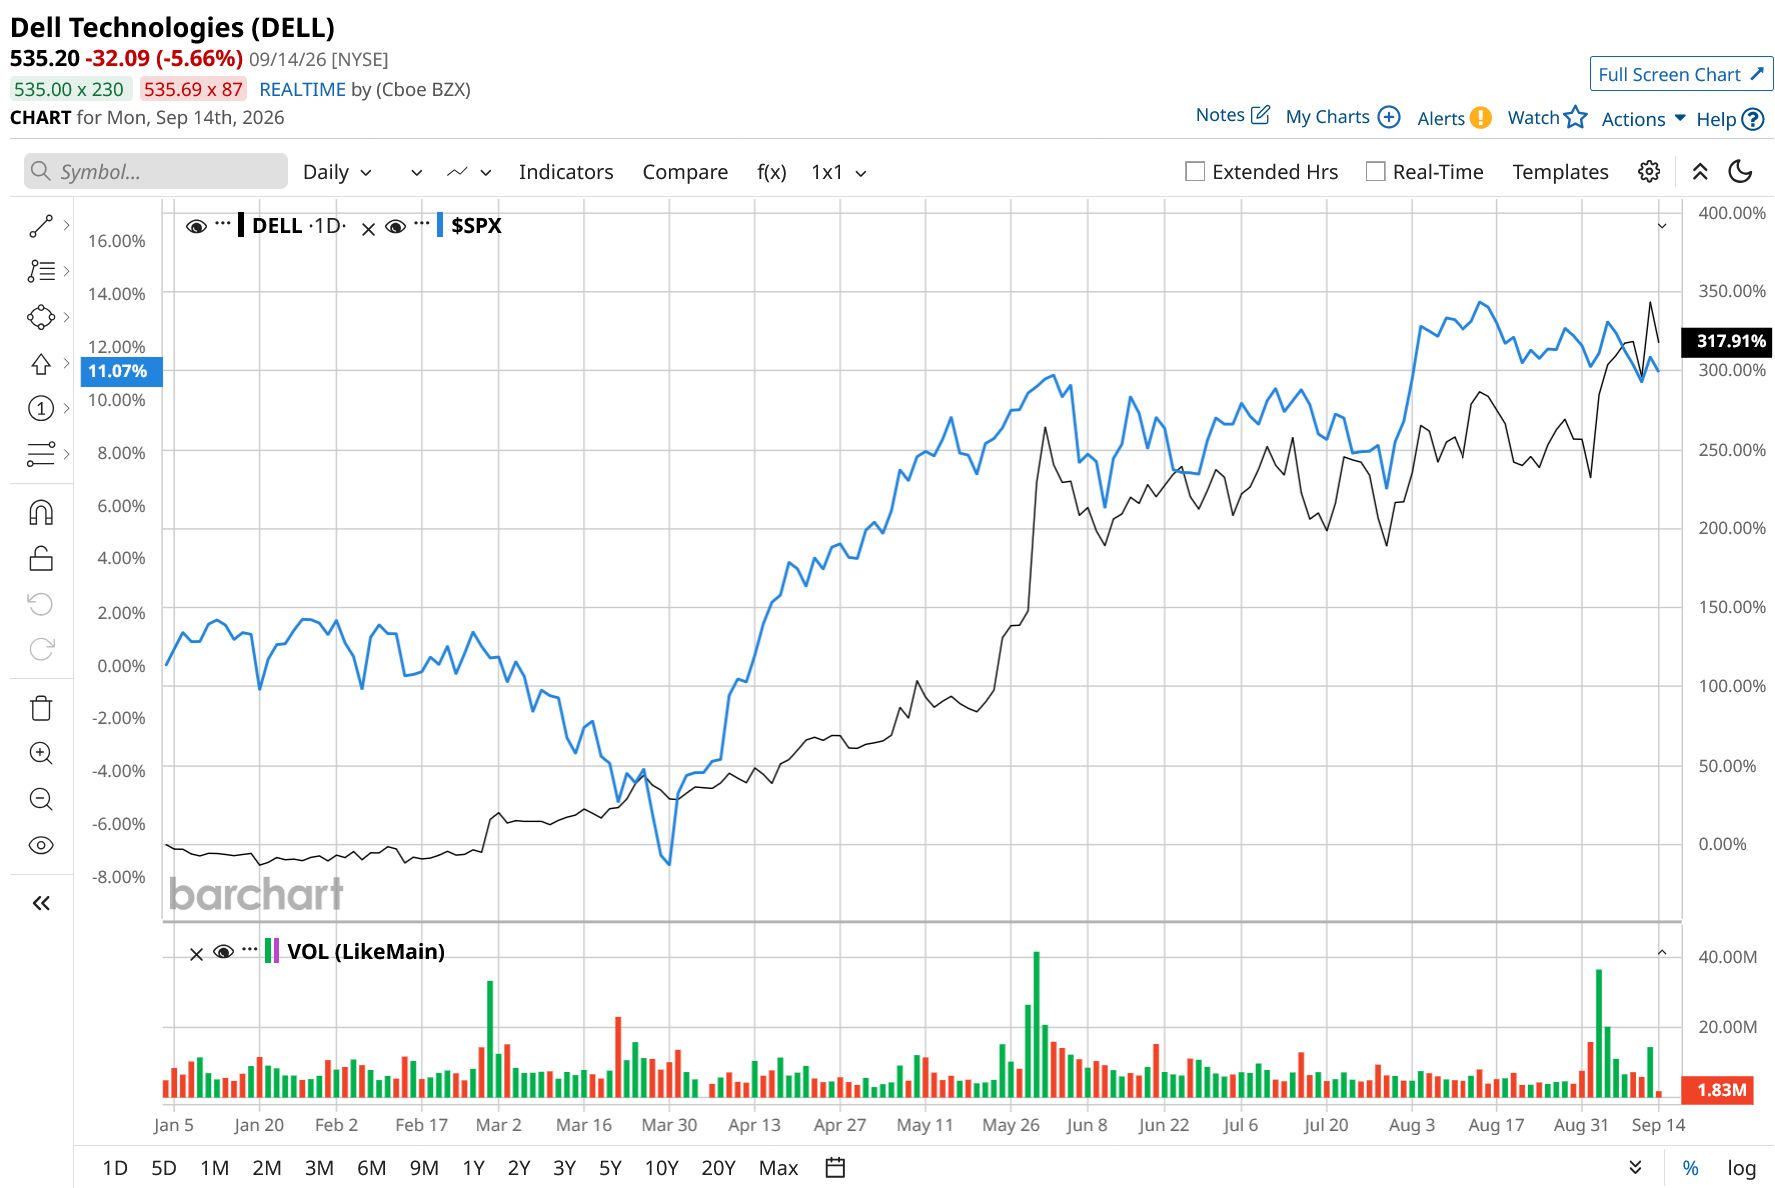
Dell shares have climbed 323% in 2026, touching a new high of $567.75 on Friday, compared to Apple’s 22% gain. After a move like that, taking profits feels almost automatic. But I would wait. Dell’s story may be less sensational than Apple's, but it is generating some remarkably exciting numbers that suggest the story may have more room to run.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Here’s why I wouldn’t lock in profits yet.
 www.barchart.com
Dell Hasn't Lost Its Charm. It May Have Found a New One.
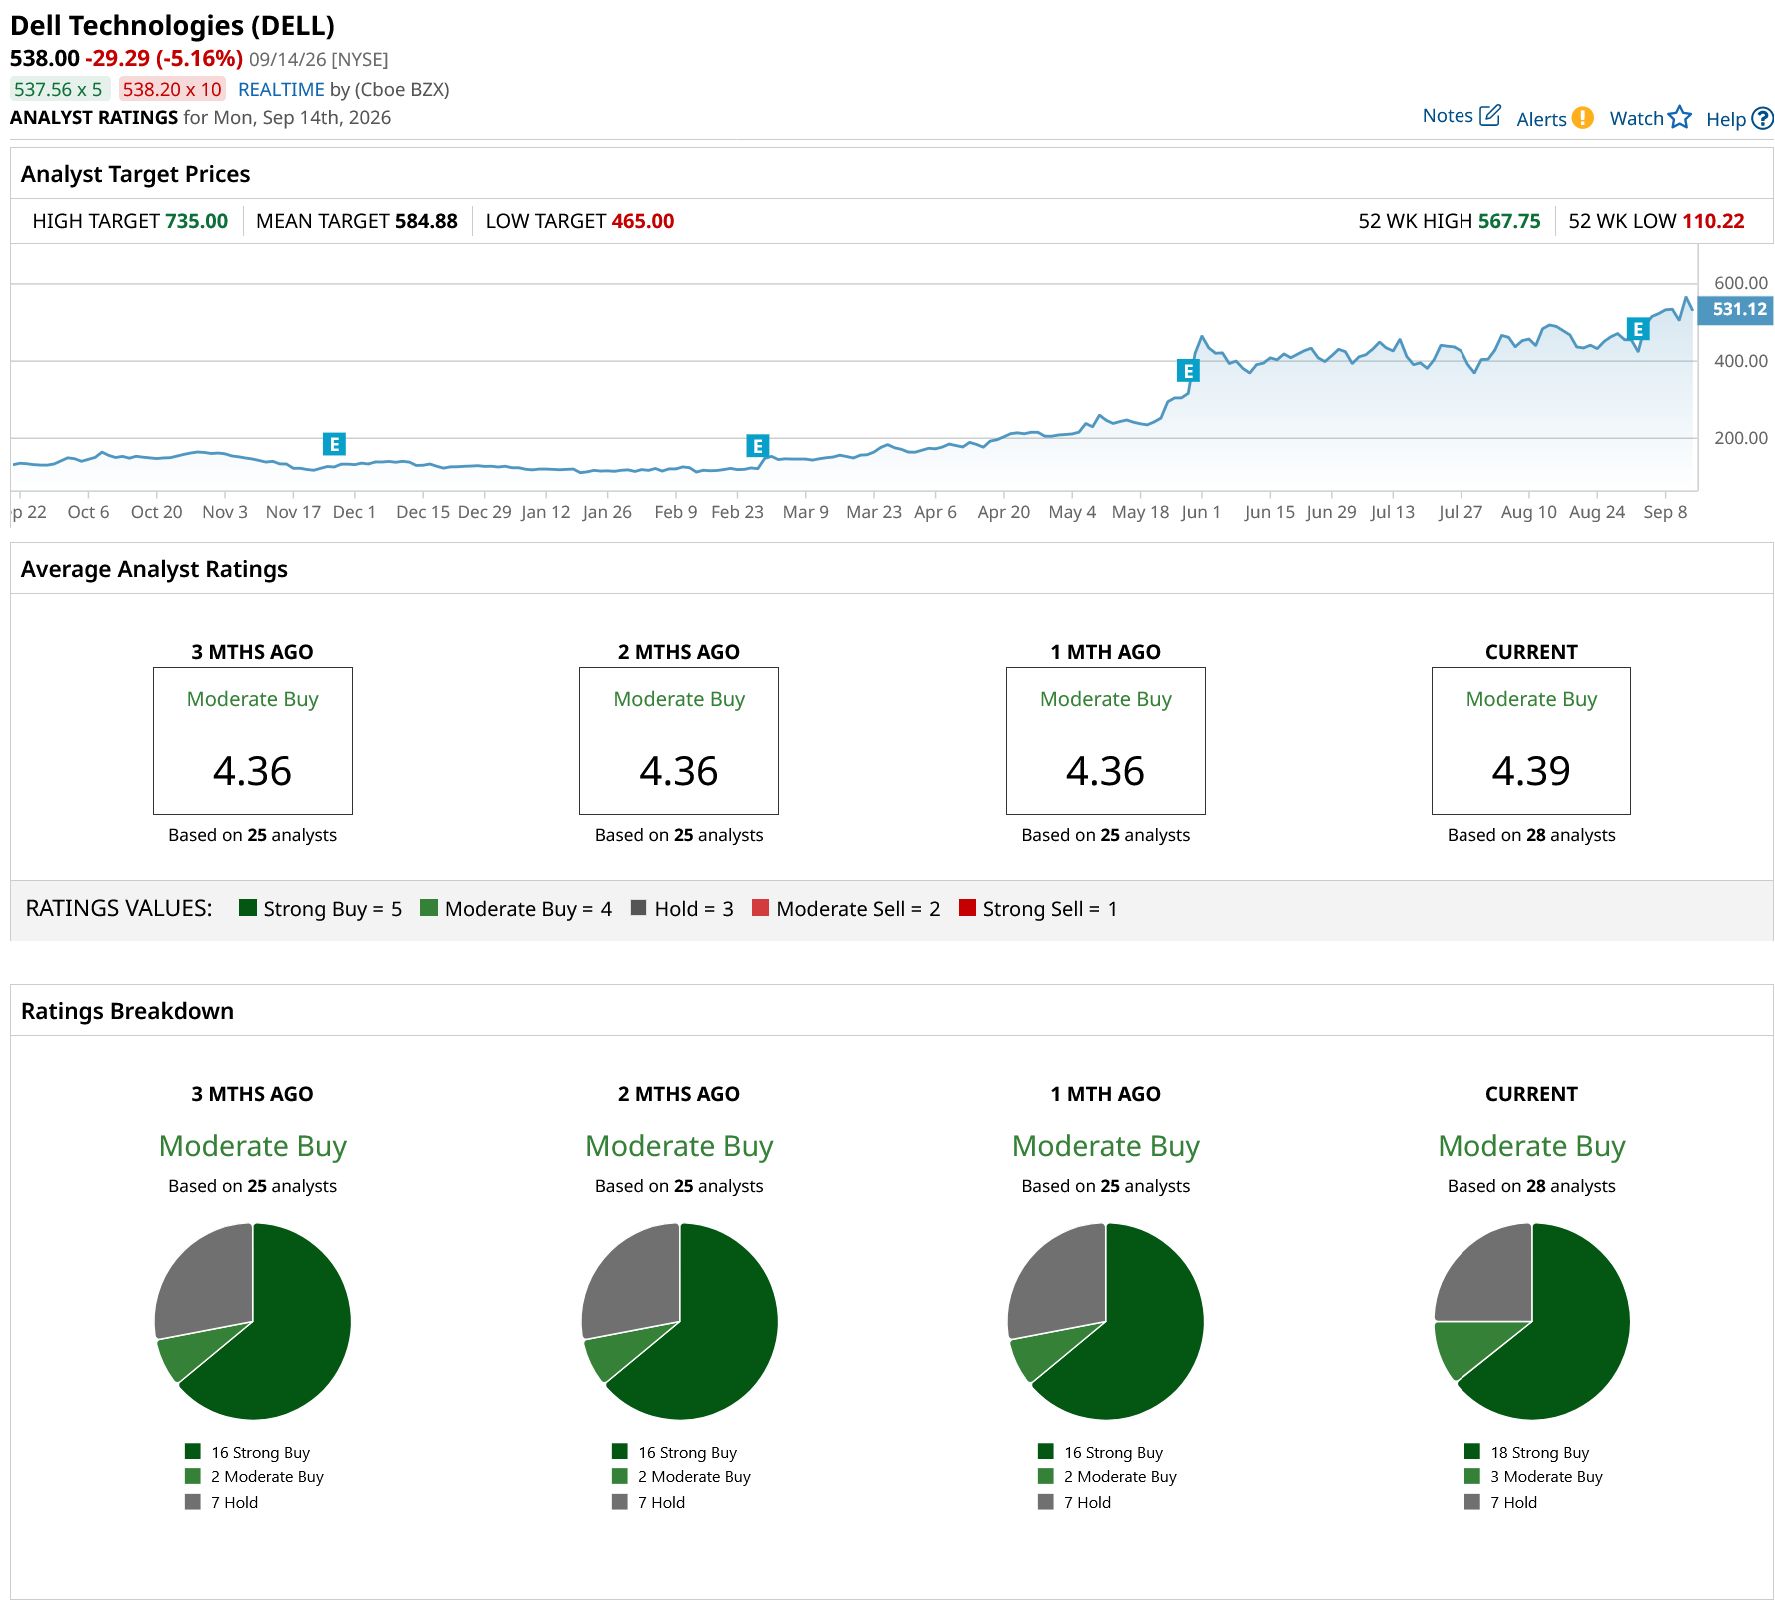
Dell Technologies was once primarily known as a PC and laptop company, but that is no longer the business investors are looking at. Today, it has evolved into a major infrastructure player, spanning AI servers, traditional servers, networking, storage, and PCs. DELL stock may have run hard this year, but its business is running harder, and the second-quarter earnings showed that. Many analysts even raised the target price for the stock. The most bullish estimate sits at $735, which implies the stock can still climb by another 29% from current levels.
There are a few reasons why analysts are so strongly optimistic for Dell’s future. AI and data center spending are now driving much of the company’s growth. In the second quarter, Dell reported a 58% year-over-year (YoY) increase in revenue to $47 billion, with $16.4 billion just from AI server revenue. Earnings per share also surged a staggering 203% to $7.04. Storage revenue also rose 26% in the quarter, boosted by demand for Dell's internally created storage products.
While AI is driving Dell’s growth, its legacy PC business isn’t dead either. Revenue for its client solutions business rose 20% in the quarter as large enterprises continue to replace older PCs. Customers that are more sensitive to costs are stretching replacement cycles. While this appears to be a bad sign, Dell believes delaying upgrades leaves more aging devices in the installed base, potentially creating a larger pool of machines that will eventually need to be replaced.
Not only does Dell's present look appealing, but its future also appears promising. The company received $60.9 billion in AI orders, increasing its total backlog to $95 billion. Its AI infrastructure client base has also surpassed 6,500, with demand coming from neocloud providers, sovereign customers, and enterprises. This indicates that demand is still increasing, and the order pipeline remains abnormally vast.
Turning to cash flow, Dell generated $8.1 billion in adjusted free cash flow and returned $4.3 billion to shareholders. At the end of the quarter, the balance sheet showed $14.2 billion in cash and investments. These growth drivers don’t guarantee that the stock will keep climbing. However, it does suggest that Dell’s fundamental story has obviously not yet reached the endpoint.
Management Raised the Bar Again
Another reason that impressed investors was management’s upbeat outlook for the future. Management expects the second half of the year to be stronger than the first, with ongoing advantages from the company's multiyear effort to simplify and strengthen its operating model.
For the third quarter, Dell guided revenue growth of 80% to $49 billion. ISG revenue is expected to rise roughly 145%, with AI server revenue is projected to be around $19 billion. For the full fiscal year 2027, Dell raised its revenue outlook to $192 billion, implying roughly 70% growth at midpoint. The company also expects full-year adjusted earnings per share of $25.50, approximately 150% higher than the prior year. These are enormous growth estimates for a stock that has already exploded this year. While this is good news, it also raises expectations. Analysts also expect revenue to increase by 14.7% and earnings by 10.7% in fiscal 2028. Trading around 22 times forward 2027 earnings, the stock looks reasonable given that earnings are expected to jump more than 150%.
Why I Wouldn’t Lock in Profits Yet
I wouldn’t lock in profits just because DELL stock has tripled so far this year. No doubt, investors should expect some volatility after such a dramatic run. But if you are a long-term investor, the focus should be on the growing business. DELL’s surge has been backed by accelerating AI demand, strong server and storage growth, market-share gains, and improving profitability, rather than just hype. Furthermore, management and analysts expect revenue and earnings growth momentum to continue. The smartest move now is to hold the stock and gradually build a position for the long term.
On Wall Street, DELL stock holds a consensus “Moderate Buy” rating. Of the 28 analysts covering the stock, 18 say it is a “Strong Buy,” three rate it a “Moderate Buy,” and seven rate it a “Hold.”
 www.barchart.com
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
CL Stock Alert: Colgate-Palmolive Reportedly Considers $1 Billion Brand Sale American Airlines (AAL) Stock’s Probability Curve Is Screaming for a Staggered Options Spread The EV Bubble Has Burst. How to Play Rivian Stock Now. Morgan Stanley Doubles Down on Apple Stock as New Offerings Become ‘More Exciting’