

Goleta, California-based Deckers Outdoor Corporation (DECK) is a global footwear and lifestyle company with products spanning performance running, outdoor activities, and premium casual fashion. Valued at a market cap of $11.1 billion, the company offers its products under the UGG, HOKA, Teva, Koolaburra, and AHNU brand names.
Companies with a market cap between $10 billion and $200 billion are typically called “large-cap stocks,” and DECK fits that definition. Its portfolio of distinctive, high-growth footwear brands, particularly HOKA and UGG, drives its market dominance. HOKA stands out for its performance-driven, comfort-focused running shoes, while UGG combines its iconic heritage with evolving lifestyle products. This strong brand equity, differentiated product design, and loyal customer base give Deckers pricing power and help it compete beyond traditional footwear trends.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
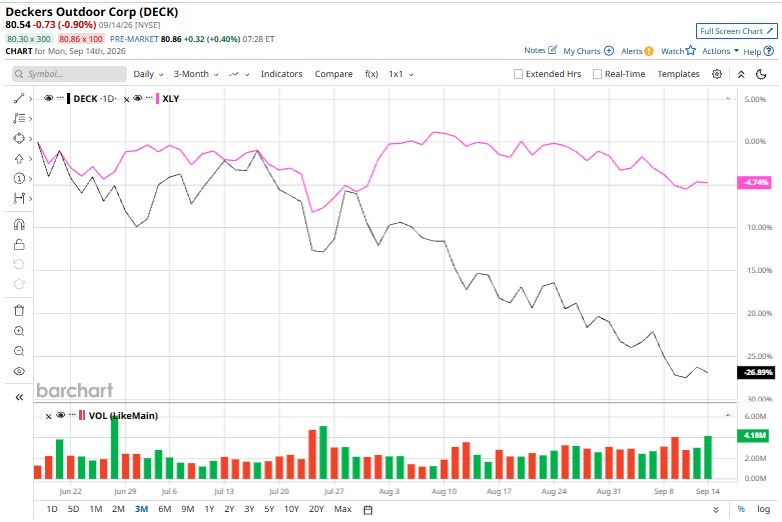
Deckers’ once-hot rally has lost some of its momentum, with DECK stock down 34.1% from its 52-week high of $122.29, reached on July 25. The recent weakness has been particularly sharp, with shares tumbling 29.3% over the past three months, far worse than the State Street Consumer Discretionary Select Sector SPDR ETF’s (XLY) 3.2% drop during the same time frame.
 www.barchart.com
The longer-term picture is equally challenging. DECK has fallen 32% over the past 52 weeks and is down 22.3% in 2026, substantially underperforming XLY’s 5.4% and 5.5% declines, respectively.
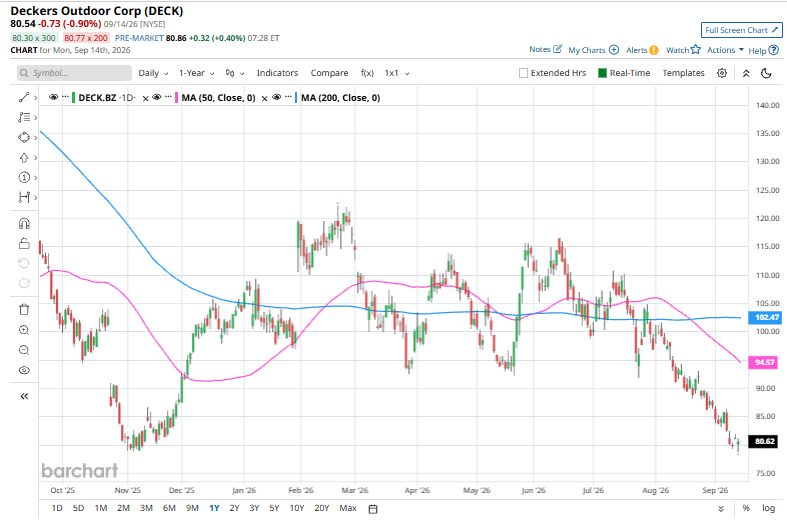
From a technical perspective, the stock’s momentum remains weak, with DECK trading below both its 50-day and 200-day moving averages since late July, reinforcing the broader downtrend.
 www.barchart.com
DECK has lagged the broader market over the past year as slower underlying revenue growth and weaker financial flexibility have weighed on investor sentiment. Sluggish constant-currency revenue growth has raised questions about whether consumers are still willing to pay premium prices for its brands, while relatively thin margins and weak free cash flow leave Deckers with less firepower to adapt to changing trends or reinvest aggressively.
Those concerns came into sharper focus on July 23, when Deckers Brands reported Q1 2027 earnings, and shares fell about 6.1% as investors focused on tariff pressures and the company’s margin outlook. The quarter wasn’t exactly a disaster, as Deckers’ revenue crossed the $1 billion mark for the first time, rising 5.7% year over year to $1.02 billion, led by 7.7% growth at HOKA and 4.9% growth at UGG. EPS also edged up 1.1% to $0.94.
Additionally, Deckers raised its full-year EPS guidance to $7.35-$7.50 from $7.30-$7.45 and nudged its gross-margin outlook above 56.5%, while keeping its sales forecast intact at $5.86 billion-$5.91 billion.
DECK’s selloff looks less severe than its heavyweight rival, NIKE, Inc. (NKE). While Deckers has endured a steep decline, NKE has fared considerably worse, with shares plunging 49.3% over the past year and 41.9% in 2026.
Despite DECK’s recent struggles, Wall Street isn’t writing off the stock just yet. Of the 27 analysts covering the company, the consensus rating stands at “Moderate Buy.” More notably, the average price target of $117.67 implies 46.1% upside from current levels, suggesting analysts see considerable room for a rebound.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.