

DaVita Inc. (DVA) is a leading U.S. provider of kidney dialysis and related clinical services for patients with chronic and end-stage kidney disease. Headquartered in Denver, Colorado, it operates thousands of outpatient dialysis centers, offers home-based modalities, and runs integrated kidney care and lab services. The company has a market capitalization of $11.72 billion, which makes it a “large-cap” stock.
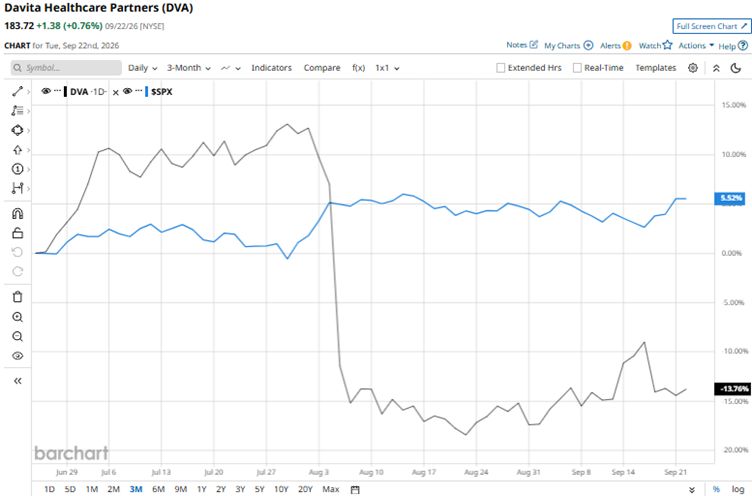
DaVita’s shares reached a 52-week high of $247.49 on Aug. 3, but are down 25.8% from that level. DaVita’s stock is down 12.4% over the past three months as investors take profits after a strong rally and weigh near-term volume and mix headwinds. Meanwhile, the broader S&P 500 Index ($SPX) is up 5.4% over the past three months. Therefore, DVA has clearly underperformed over this period.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
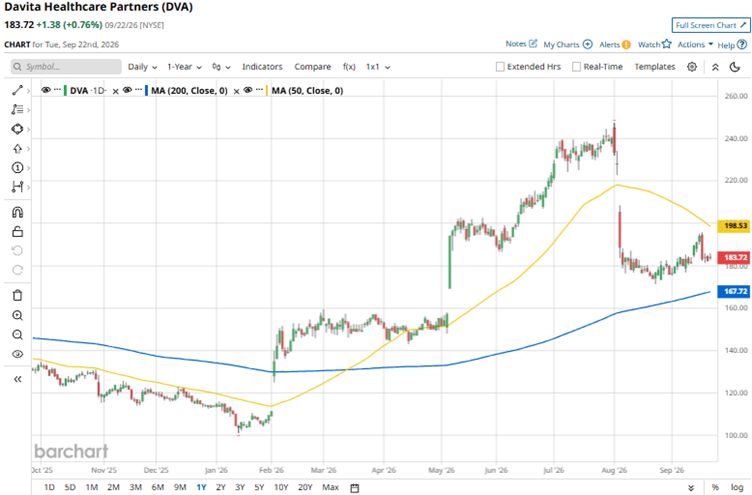
Growth in its higher-margin Integrated Kidney Care platform, improving treatment volumes, and operational productivity further supported the stock over the past year. Over the past 52 weeks, the stock has gained 40.1%, while the S&P 500 index is up 16.6%. DaVita’s stock is up 61.7% year-to-date (YTD), while the broader index is up 13.4%. The company’s shares have traded above its 200-day moving average since early March but have dropped below its 50-day moving average since early August.
 www.barchart.com
On Aug. 5, DaVita’s stock declined by 17.2% intraday after the company reported its Q2 results. Investors chose to focus on the decline in revenue per treatment quarter-over-quarter (QOQ). The quarter’s change was mainly due to shifts in payor mix and typical fluctuations, partly offset by seasonal effects from co-insurance and deductibles, along with higher average rates. Adjusted EPS for the quarter rose 40.1% QOQ to $4.02.
Wall Street analysts have positive views on DaVita’s bottom-line trajectory. For the current quarter, its profit is expected to increase by 50.6% YOY to $3.78 per share. For fiscal 2026, the company’s bottom line is projected to increase by 35.2% annually to $14.57 per share, followed by an 18.4% climb to $17.25 per share in fiscal 2027.
We compare DaVita’s performance with that of another medical care facilities stock, Encompass Health Corporation (EHC), which is down 2.6% over the past 52 weeks, but increased 15.7% YTD. Therefore, DaVita has clearly outperformed over these periods.
Wall Street analysts are moderately bullish on DaVita’s stock. The eight analysts covering it have a consensus rating of “Moderate Buy.” The mean price target of $224.86 implies a 22.4% upside from current levels. The Street-high price target of $270 indicates a 47% upside.
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Yum China Stock Is Satistically Terrible. Here’s What Wall Street Isn’t Telling You. Microsoft Is Cutting 268 Xbox Roles as Activision Takes Over Halo. This Is a Simple Restructuring, Not a Broader Panic Signal for MSFT Stock. Nvidia Partner IonQ Sparks a Quantum Computing Stock Rally — Here’s One Way to Invest. Late Billionaire Charlie Munger Said American Medical Costs Are ‘A Disgrace’ And That Singapore Does It Better At ‘20% Of What We Pay’