

On Oct. 1, keep an eye on Corteva (CTVA). That’s when the company will give shareholders ownership in two separate agricultural stocks. One will be its Crop Protection business, known as New Corteva; the other will be its Seed business, being spun off into Vylor.
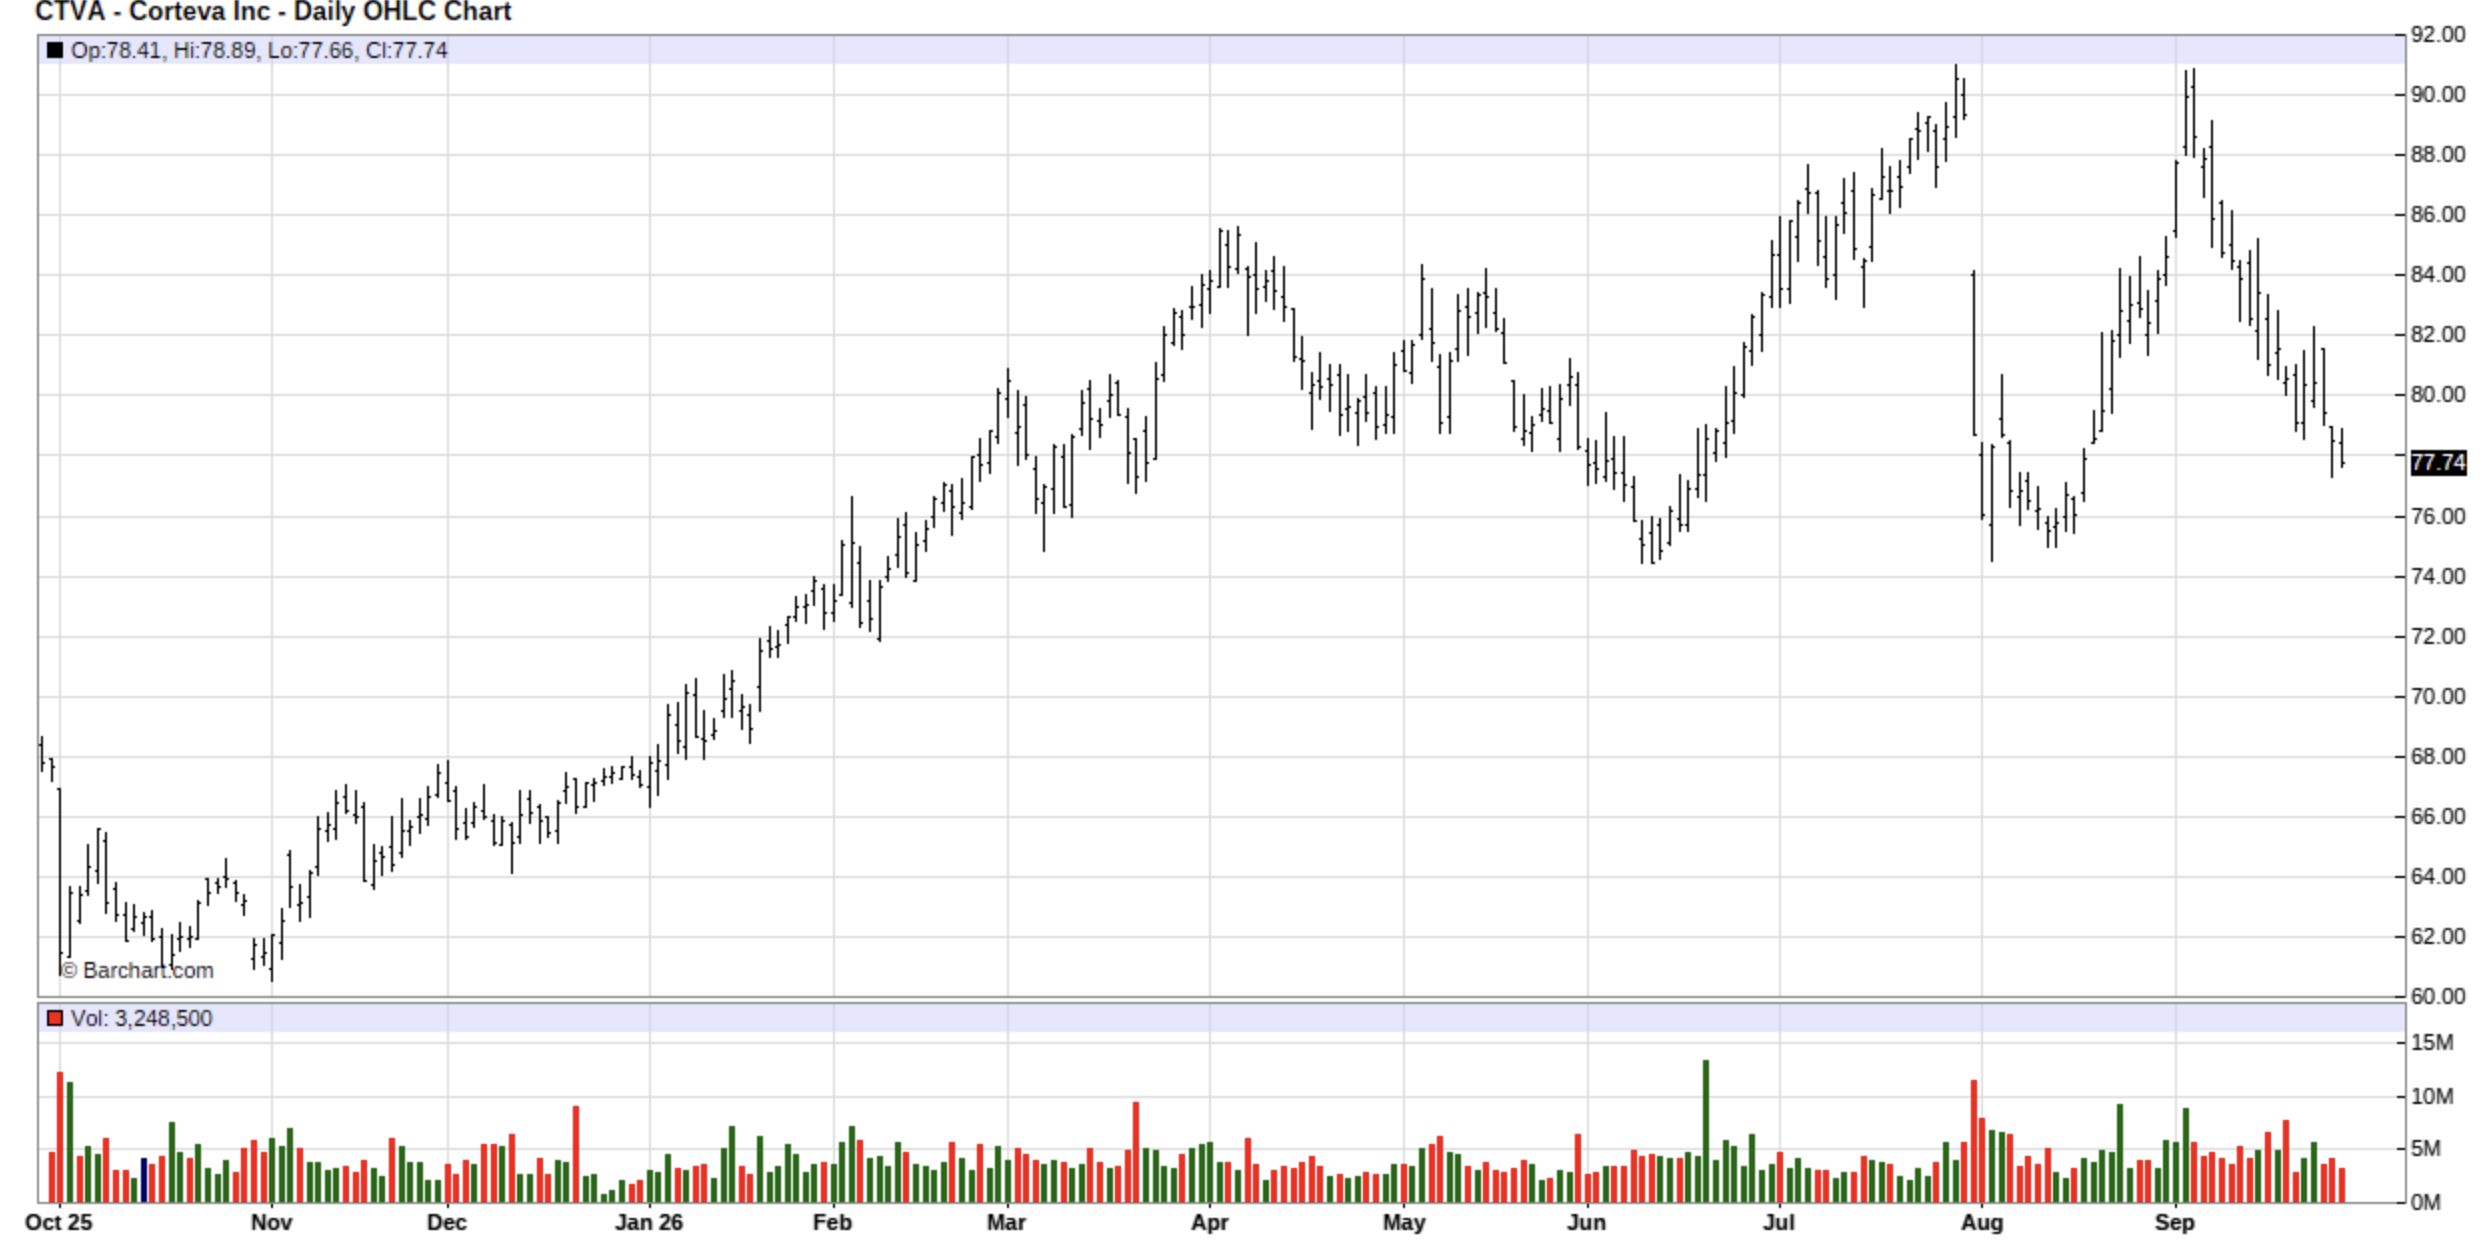 www.barchart.com
Under the announced terms, shareholders will receive one Vylor share for every Corteva share held at the close of Sept. 24. The distribution is expected to happen on Oct. 1, with Vylor beginning regular trading on the NYSE under the ticker VYLR. So, an investor holding 100 Corteva shares would receive 100 Vylor shares while keeping the Corteva shares. Once the deal is completed, Vylor will focus on advanced seeds and genetics, including the established Pioneer brand. Corteva will concentrate on crop protection and nature-inspired technologies that help farmers protect their crops.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Two Businesses with Different Priorities
With the deal, each company can now build an investment strategy around its own products, customers, and growth opportunities. As noted by CEO Chuck Magro, “The seed and crop protection markets have evolved, and as a result, we see the opportunities ahead for both companies diverging — this is the right time to act to stay ahead of the market. This separation will allow both businesses to maximize long-term value creation by focusing on their own priorities. As such, we see this separation as the logical next step in their growth trajectory.”
On one side, we have Vylor, described as having the world’s largest seed production network across key crop markets, as noted by Corteva Agriscience.com. For example, it already has iconic brands, such as Pioneer and Brevant. In addition, Vylor has 4,000 germplasm patents and more than 2,000 biotechnology patents. On the other side is Corteva, which can now focus on its crop protection portfolio of herbicides, fungicides, insecticides, and nature-inspired biological technologies. The strongest evidence of success will emerge after the separation, especially if we see successful products, improving profitability, and better cash flow. If both can deliver, the split could create substantial shareholder value over the long haul.
Analyst at UBS Sees a Stronger Profit Outlook
UBS analyst Joshua Spector raised his profit forecasts for both companies. The most significant changes were made for Corteva, where the analyst raised its EBITDA forecast by 12% for 2027, and 11% for 2028. It now expects Corteva to generate about $1.46 billion in EBITDA and EPS of about $1.15 a share in 2027, and $1.30 in 2028. For Corteva as a whole, UBS raised its EBITDA forecast by 1.8% for 2026, 3.5% for 2027, and 1.9% for 2028. As for EPS, UBS raised its estimates by 2.3% to $3.88 for 2026, 6.5% to $4.15 for 2027, and 3.4% to $4.65 for 2028.
Regarding Vylor, UBS raised its 2026 EBITDA estimate by 2.9%. It also left its 2027 forecast almost unchanged, and cut its 2028 estimate by 1.6%. EPS estimates increased by 9.6% for 2026, by 4.7% for 2027, and by 2.3% for 2028. Adjusted EPS estimates of $2.81 are expected in 2026, $3.01 in 2027, and $3.40 in 2028.
Recent Earnings Were Mixed
In its most recent earnings report, the company's EPS of $2.30 beat by 40.07, and revenue of $6.38 billion was down 2.4% year over year, missing by $220 million.
"Our strong first half was fueled by demand for next-gen Seed technologies, differentiated Crop Protection products, and focused execution. This level of performance, combined with our company-wide focus on productivity, cost discipline, and operational excellence, allowed us to deliver continued margin expansion. Given these results, and our confidence in the opportunities ahead, we are raising our full-year guidance,” said Magro.
The company raised its operating EBITDA guidance to a range of $4.1 billion to $4.3 billion, which would be 9% growth at the midpoint. Operating EPS is expected to range from $3.60 TO $3.80, which is 11% growth at the midpoint.
What Do Analysts Say About CTVA Stock?
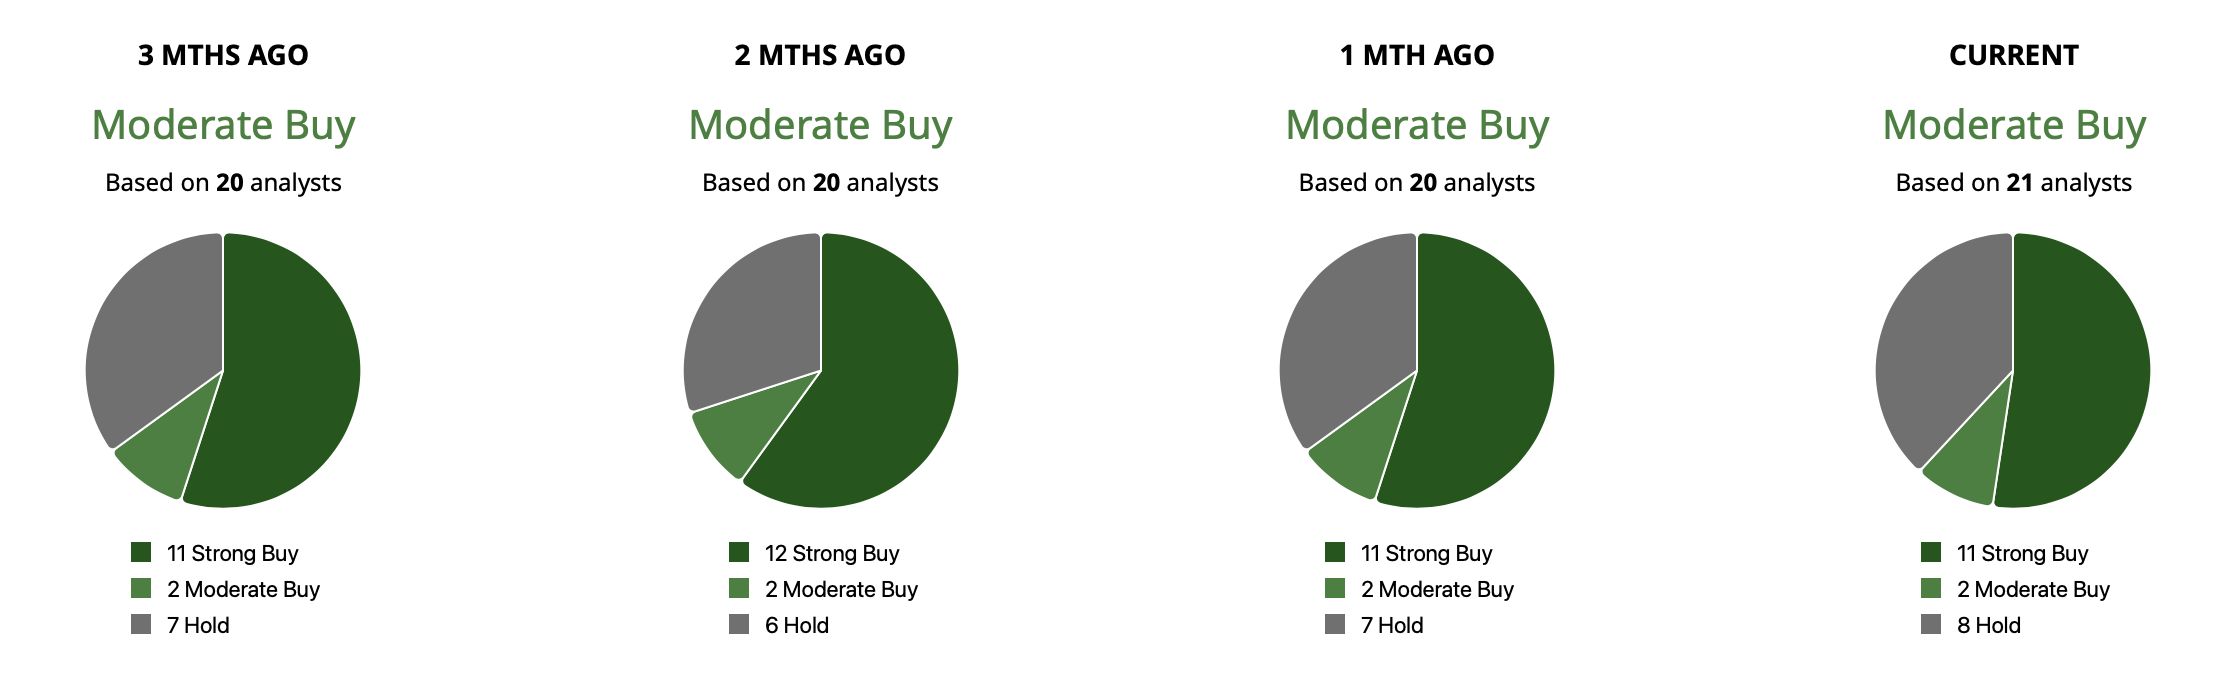
Overall, Corteva has a consensus “Moderate Buy” rating on Wall Street. Of the 21 analysts covering CTVA stock, 11 have a “Strong Buy” rating, two have a “Moderate Buy” rating, and eight have a “Hold” rating. The mean target price of $91.70 implies a potential upside of 18% from current levels. Meanwhile, its high-end price target of $103 implies a potential upside of 32% moving forward.
 www.barchart.com
On the date of publication, Ian Cooper did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play QCOM Stock as Apple Renews Licensing Agreement With Qualcomm Dear Corteva Stock Fans, Mark Your Calendars for Oct. 1 Nvidia Just Spent Nearly $13 Billion on Something Other Than GPUs. Here’s How It Helps NVDA. Dear Nike Stock Fans, Mark Your Calendars for Oct. 1