

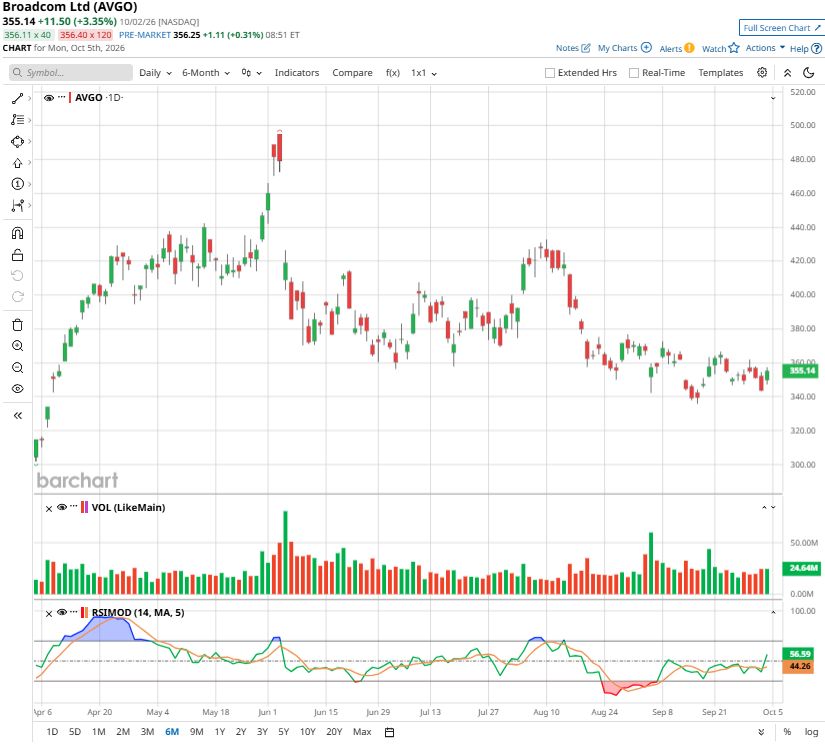
Broadcom (AVGO) stock has trailed the broader market this year, gaining just 5% year-to-date (YTD) versus a 13.5% increase for the S&P 500 ($SPX). AVGO stock has faced pressure after the company issued forward guidance that fell modestly short of expectations. Growing concerns over rising competition in the custom AI chip space have also weighed on investor sentiment.
Despite these challenges, Broadcom’s outlook remains compelling. Strong demand for its custom AI accelerators among its largest customers could help ease concerns about competitive pressures. With the custom AI chip opportunity continuing to expand and demand for networking products remaining strong, the company appears well positioned for renewed growth, pointing to a solid recovery in its share price.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
Broadcom: Competition Concerns are Overblown
Concerns about intensifying competition in custom AI semiconductors, particularly following Marvell Technology’s (MRVL) relationship with Alphabet’s (GOOG) (GOOGL) Google, appear to be overblown. Broadcom’s latest results indicate demand for its AI infrastructure remains exceptionally strong, suggesting competitive pressures are unlikely to materially weaken its growth trajectory anytime soon.
Broadcom will continue to deliver strong growth led by AI semiconductors. Revenue from this business increased 221% year-over-year (YoY) and 54% sequentially in the third quarter. Thanks to strong momentum in AI semiconductors, consolidated quarterly revenue jumped 86% YoY. Profitability improved even more rapidly, with operating income rising 92% YoY.
The company’s custom accelerator business is accelerating. Broadcom’s six XPU customers are accelerating deployments, causing AI semiconductor revenue to more than triple YoY to $16.7 billion. XPU shipments increased more than 3.5 times from the prior year and accounted for 73% of AI revenue during the quarter. Meanwhile, AI networking revenue also grew more than 2.5 times YoY.
Product momentum supports its future growth outlook. Broadcom delivered its Ironwood TPU platform in volume to Anthropic and Google while simultaneously beginning production shipments of its next-generation TPU v8i to Google. The newer platform incorporates greater memory capacity and bandwidth and is optimized for inference workloads, positioning it for the expanding demand associated with AI deployment.
The outlook for Q4 remains robust. Broadcom expects XPU and AI networking revenue to each triple YoY, pushing quarterly AI revenue to approximately $21.7 billion, representing 236% annual growth. For fiscal 2026, management projects AI revenue of $58 billion, up 186% YoY.
Importantly, Broadcom’s relationship with Google appears to be strengthening, not weakening. A long-term agreement covering future TPU generations and AI networking is expected to support annual TPU deployments worth tens of billions of dollars over the coming years. This relationship creates a meaningful competitive barrier.
Broadcom’s competitive advantages extend beyond individual chip designs. Its broad product portfolio, ability to move products rapidly from design to volume production, and established customer relationships indicate that its competitive moat remains substantial.
Broadcom’s Valuation Still Appears Reasonable
Broadcom’s valuation looks reasonable against its strong long-term growth prospects, suggesting AVGO shares may have room to appreciate. The stock currently trades at 33.2 times forward earnings, which is justified given its strong EPS growth potential.
Broadcom anticipates a significant increase in demand from major AI companies. Management expects AI-related revenue to reach approximately $115 billion in 2027, doubling from current levels, before doubling again to $230 billion in 2028.
The company’s earnings outlook is similarly robust. Analysts expect Broadcom’s EPS to rise by more than 68% in fiscal 2027. For fiscal 2028, management has indicated that EPS could exceed $30, representing an additional YoY increase of roughly 72%.
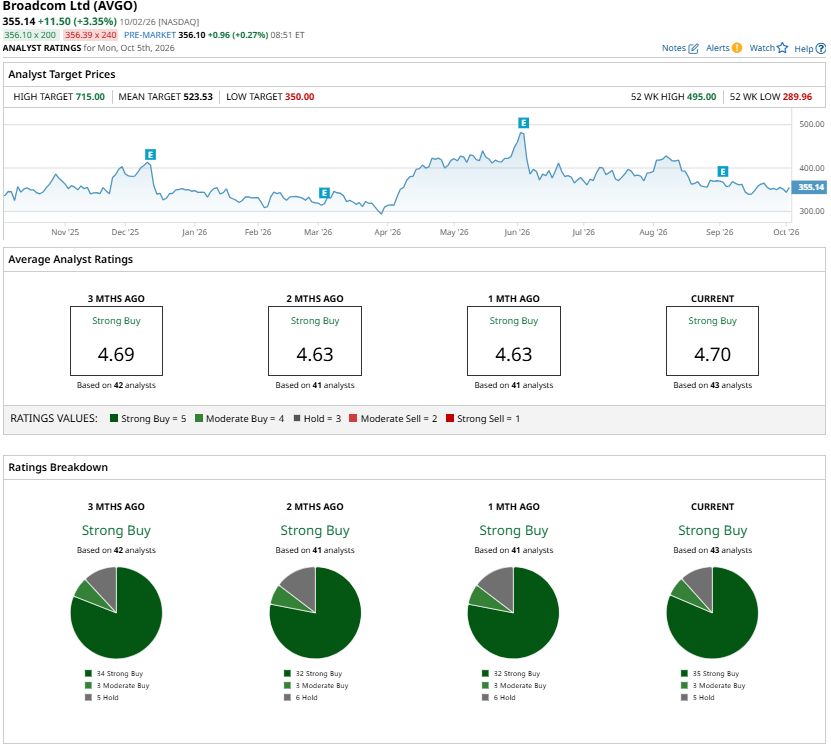
Wall Street analysts are also optimistic about AVGO stock, with an average price target of $523.53, suggesting potential upside of more than 47% from current levels.
 www.barchart.com
The Bottom Line for AVGO Stock
Broadcom’s rapid growth in custom AI accelerators, expanding AI networking demand, and deepening relationships with hyperscalers provide a strong foundation for sustained earnings growth. At the same time, competition concerns appear manageable given Broadcom’s scale, technology portfolio, and customer relationships.
With AI revenue expected to continue growing sharply and EPS potentially exceeding $30 by fiscal 2028, AVGO stock’s current valuation leaves room for further multiple expansion. Against this backdrop, the average Wall Street price target of $523.53 appears achievable considering its solid AI roadmap and earnings growth.
On the date of publication, Sneha Nahata did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.