

AST SpaceMobile (ASTS) is moving three more satellites from Midland, Texas, toward Cape Canaveral, Florida, via a good old-fashioned convoy. BlueBirds 14, 15, and 16 will follow BlueBirds 11 to 13, which launched on Aug. 5, and BlueBirds 8 to 10, which launched in June. The company has not yet set a launch date.
About ASTS Stock
AST SpaceMobile is building a network of satellites that act like cell towers in space. It is the world’s first and only space-based cellular broadband network company. Its goal is to let regular smartphones connect directly to satellites, providing cellular and broadband coverage in areas where traditional mobile networks are unavailable. The company serves both commercial and government users. Founded in 2017, the company is headquartered in Midland, Texas.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
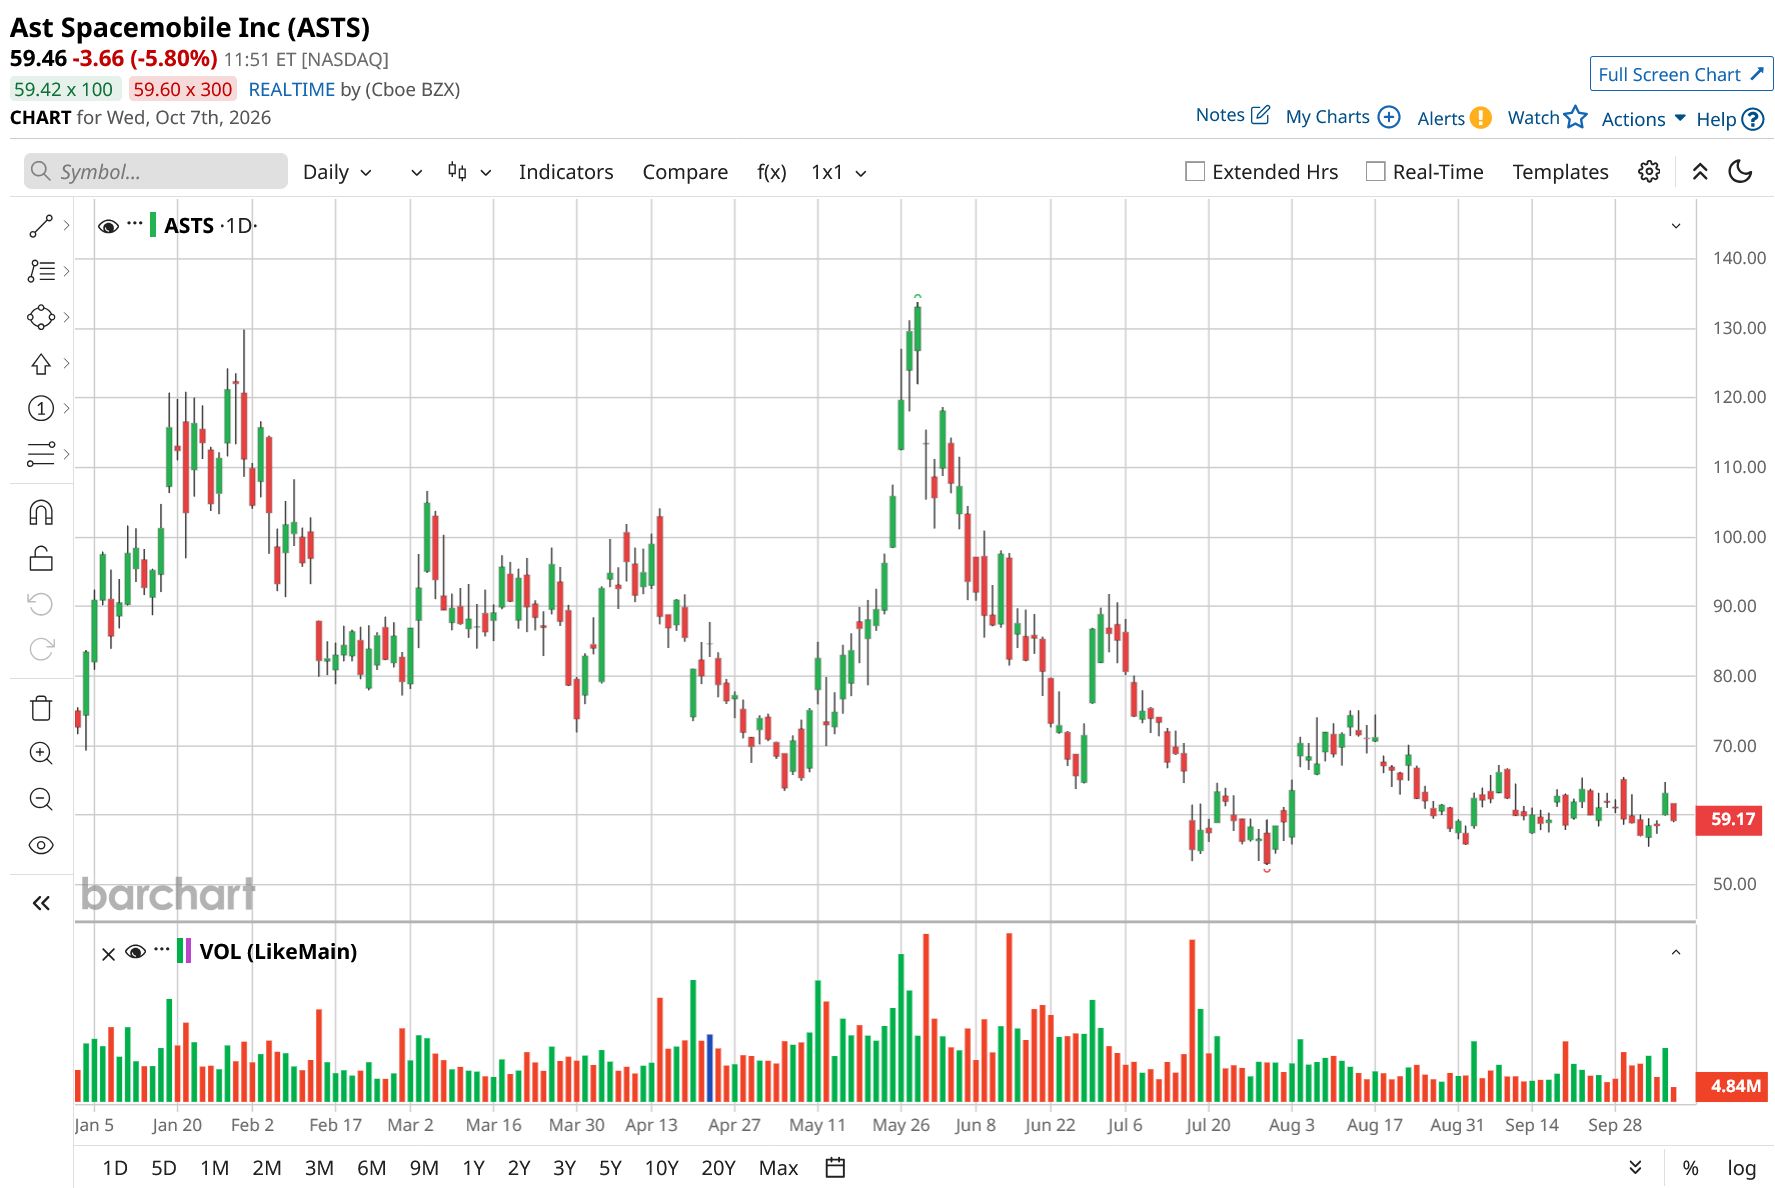
Over the past year, ASTS shares have declined about 21%, underperforming the S&P 500’s ($SPX) gain of 16% during the same period. The stock has been fairly volatile over the past 52 weeks. At the end of May, it was trading at $129, and it has continued to decline since then. It is currently trading near its 52-week low.
Earnings are expected to grow 36.72% in 2027 and 78.88% in 2028. The company is expected to be profitable in 2029. The balance sheet adds another consideration. AST SpaceMobile carries $2.99 billion in debt against $2.29 billion in cash.
 www.barchart.com
From Prototype to Production
Production in Midland has now progressed through BlueBird 50, with more than 20 spacecraft structures currently being assembled. This is important because AST SpaceMobile needs a sufficient number of satellites to move beyond patchy coverage and provide continuous service.
The opportunity is significant. The company has deals with nearly 60 mobile operators whose networks serve over 3 billion subscribers. AST SpaceMobile says its satellites can deliver a peak capacity of more than 150 Mbps per coverage cell. The latest production progress suggests the company is moving from proving its technology toward building out a network.
Is the Price Ahead of the Network?
The market is already pricing AST SpaceMobile for substantial future growth. With no meaningful earnings yet, investors are primarily paying for the company’s growth potential. Its forward price-to-sales (P/S) multiple is 104.51x, compared with a sector median of just 1.08x. Sales remain relatively small compared with ASTS’s $22.91 billion market cap, meaning the valuation is largely based on the network the company plans to build. That gap may explain why about 21.84% of the float is betting against the stock.
To me, that premium only holds if launches stay on schedule and carriers become paying customers. Delays could put pressure on the stock.
Management Stands by 2026 Revenue Target Despite Execution Focus
AST SpaceMobile reported its second-quarter fiscal 2026 earnings on Aug. 10. The company recognized revenue of $31.5 million in the quarter, primarily driven by commercial gateway deliveries and various US government service milestone achievements. Non-GAAP adjusted operating expenses for the quarter were $119.1 million versus $91.2 million in the first quarter. This quarter was a period of strong operational progress for the company, with BlueBird satellites 11 through 13 already in orbit and BlueBird 14 through 16 nearing shipment.
Looking forward, ASTS reaffirmed full-year 2026 revenue guidance of $150 million to $200 million. The company expects revenue’s main drivers to be gateway deliveries, U.S. government contract milestones, and mobile network operator consulting services. The company also guided Q3 adjusted operating expenses, excluding cost of revenues, to $105 million to $115 million. Moreover, capital spending is expected to remain elevated at $350 million to $425 million in the quarter.
What Do Analysts Expect for ASTS Stock?
B. Riley downgraded ASTS stock to “Neutral” from “Buy” with a price target of $65, down from $85. The firm noted growing competition, delays in satellite launches, and rising costs to build and operate AST’s satellite network. The firm is also concerned that consumers may not be willing to pay enough for satellite-based mobile connectivity, especially as cheaper alternatives from competitors such as Viasat (VSAT) become available. Similarly, William Blair maintained a “Hold” rating on ASTS.
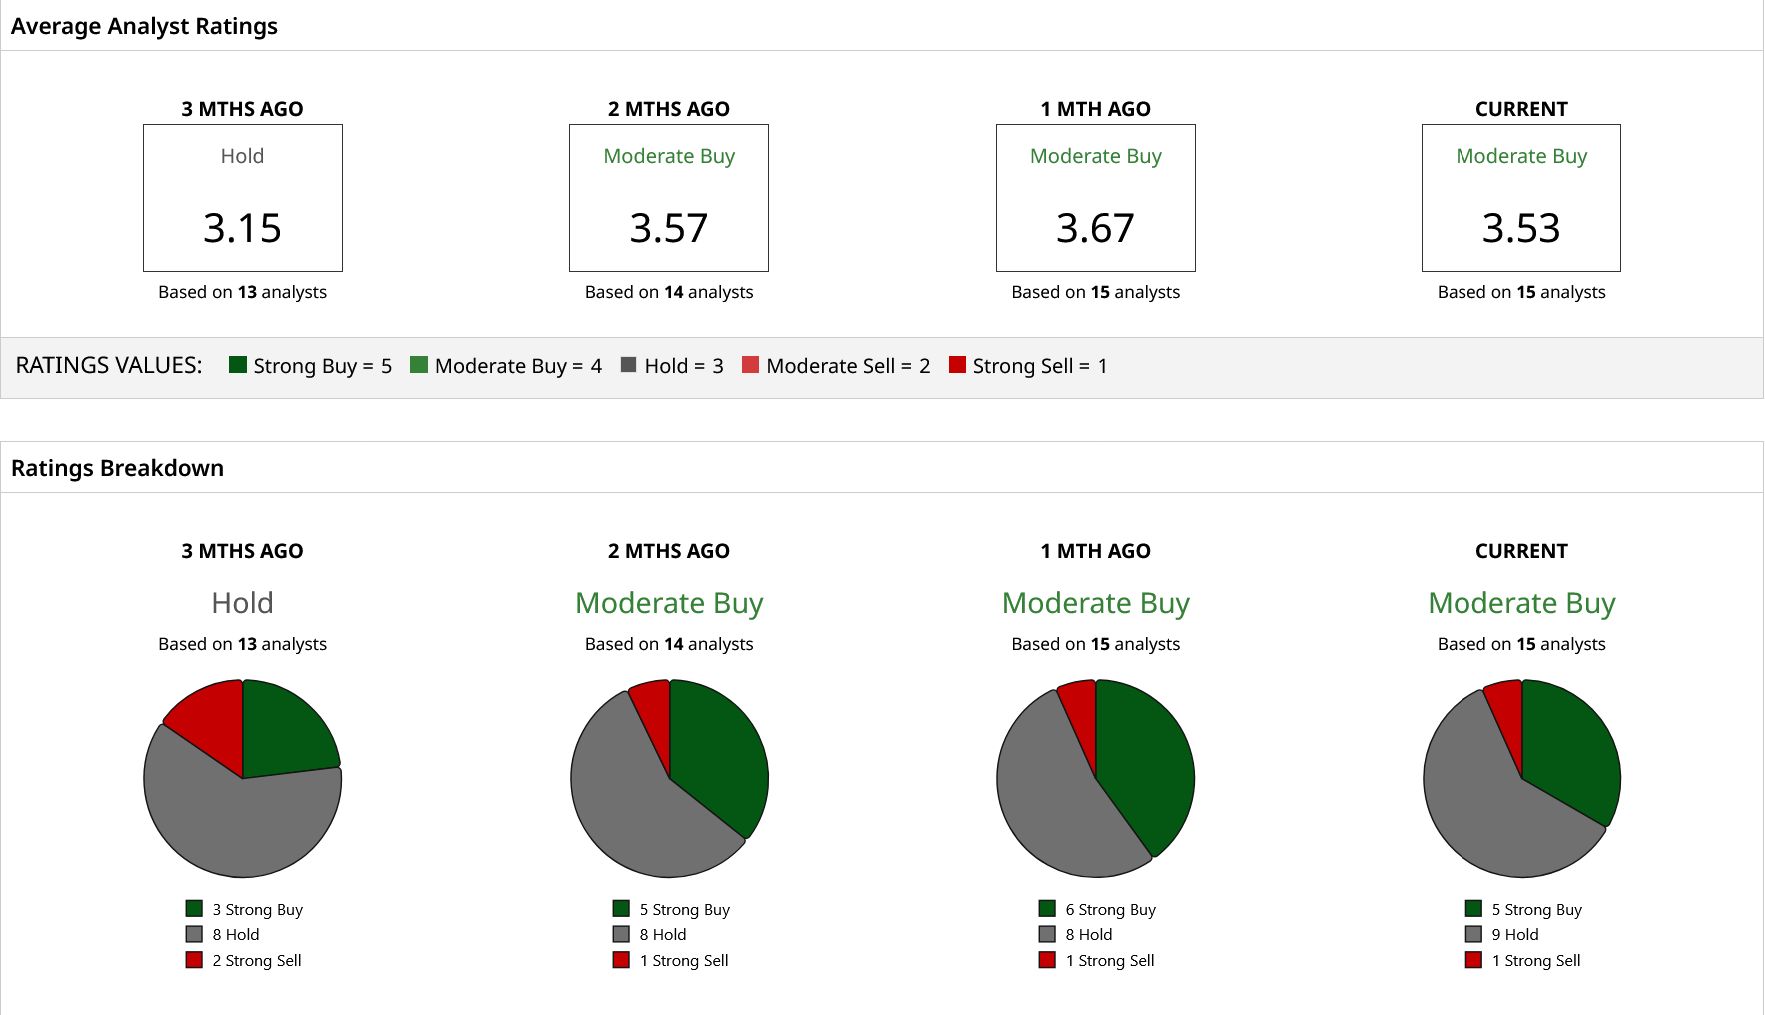
Based on 15 Wall Street analysts, ASTS holds a consensus “Moderate Buy” rating. Out of those, five have a “Strong Buy” rating, nine have a “Hold” rating, and one has a “Strong Sell” rating. The stock’s mean price target of $82.68 reflects a 39% upside from current levels.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
21.84% of AST SpaceMobile’s Float Is Betting Against It. Here’s What the Convoy Doesn’t Fix. Despite a 473% Rally Over the Past Year, This Analyst Says Micron Stock Is Still ‘Dirt Cheap’ You Likely Haven’t Heard of Arrow Electronics, But Its Stock Is Red Hot at New All-Time Highs Constellation Lands a 3,590 MW Power Deal With Google. AI’s Quietest Winner May Not Stay Quiet for Long.