

Ambient personal hardware is emerging as the next major battleground for generative technology, shifting artificial intelligence from desktop screens directly into everyday interactions. By using context-aware wearables and magnetic accessories to capture conversations, these compact devices seamlessly transform real-world dialogue into automated reminders, actionable insights, and structured notes.
Expanding this frontier of personal hardware, Amazon (AMZN) recently introduced its new "Bee" lineup featuring the Bee Frontier wearable and Bee Eclipse phone attachment.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About Amazon
Amazon is a global e-commerce, cloud-computing, digital-advertising, and artificial intelligence leader. Through Amazon Retail, Prime, AWS, Alexa, and its advertising business, the company serves consumers, sellers, enterprises, and developers worldwide, leveraging logistics scale, AI infrastructure, and cloud technology to drive growth across multiple high-margin segments.
Amazon Stock Outpaces Market
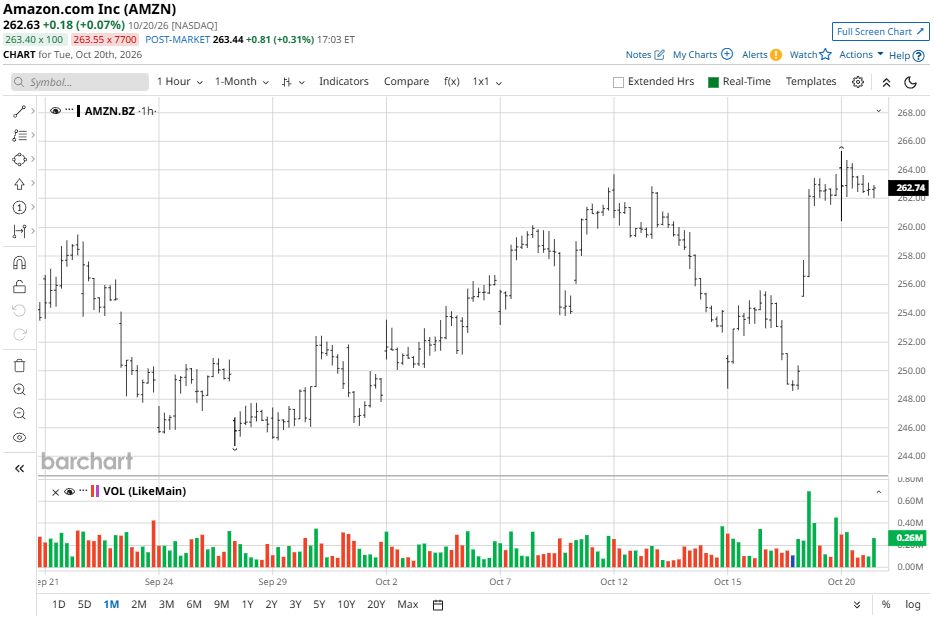
Amazon stock has delivered solid gains in 2026, supported by accelerating AWS growth and renewed investor enthusiasm for AI infrastructure. AMZN rose about 13.7% year to date and 23.2% over the past year. The shares jumped roughly 5% on Oct. 19 after Morgan Stanley named Amazon a “Top Pick”.and helped drive the Consumer Discretionary sector up 2.7%
Compared with the S&P 500 Consumer Discretionary sector ($SRCD), Amazon has been a leading contributor to sector gains. Its dual exposure to e-commerce and cloud computing gives it a growth profile that remains distinct from traditional consumer-discretionary peers.
 www.barchart.com
Amazon’s Strong Quarterly Report
In its latest second-quarter results, Amazon generated revenue of $200.61 billion, up 19.6% year over year and ahead of the consensus estimate of roughly $197 billion. GAAP EPS was $5.75, far exceeding the $1.83 forecast, although the result included a $53.4 billion pre-tax gain largely tied to its investment in Anthropic. On an adjusted basis, EPS was $1.88.
Amazon’s operating performance remained strong, with trailing-12-month revenue of $775.68 billion, up 14.7% year over year, a 50.8% gross margin, and a 17.5% net margin. AWS remains the key profit engine, while advertising, Prime, and AI-related cloud demand continue to support operating leverage. The company also reported Q2 earnings of $62.65 billion, reflecting the substantial non-operating investment gain.
Management guided third-quarter revenue to approximately $199.5 billion, representing 10.7% year-over-year growth, though slightly below prior analyst expectations. More importantly, Amazon guided Q3 operating income to $22.5 billion to $26.5 billion, sharply higher than $17.4 billion a year earlier, signaling confidence in AWS momentum, retail efficiency, and AI-driven cloud demand.
Amazon Unveils 2 New AI Devices
Amazon is expanding its personal-AI hardware ecosystem with two new Bee devices: the $74.99 Bee Frontier wearable, available now, and the $99.99 Bee Eclipse magnetic phone attachment, launching soon.
Designed to turn conversations into summaries, reminders, insights, and action items, the products deepen Amazon’s push into AI wearables and ambient computing. Bee Frontier offers dual microphones, IP67 water resistance, and up to seven days of battery life, while Bee Eclipse claims more than 21 days of battery life.
Both integrate with Bee’s mobile and desktop apps, Gmail, Google Calendar, Microsoft (MSFT) Outlook, Alexa+, and Amazon.com, creating potential shopping and advertising opportunities for Amazon. Basic users receive summaries and 14-day memory, while the $11.99-per-month Bee Pro plan unlocks expanded features and integrations.
For investors, the launch reinforces Amazon’s strategy to extend AI beyond AWS into consumer devices, recurring software revenue, and commerce engagement.
Should You Buy AMZN?
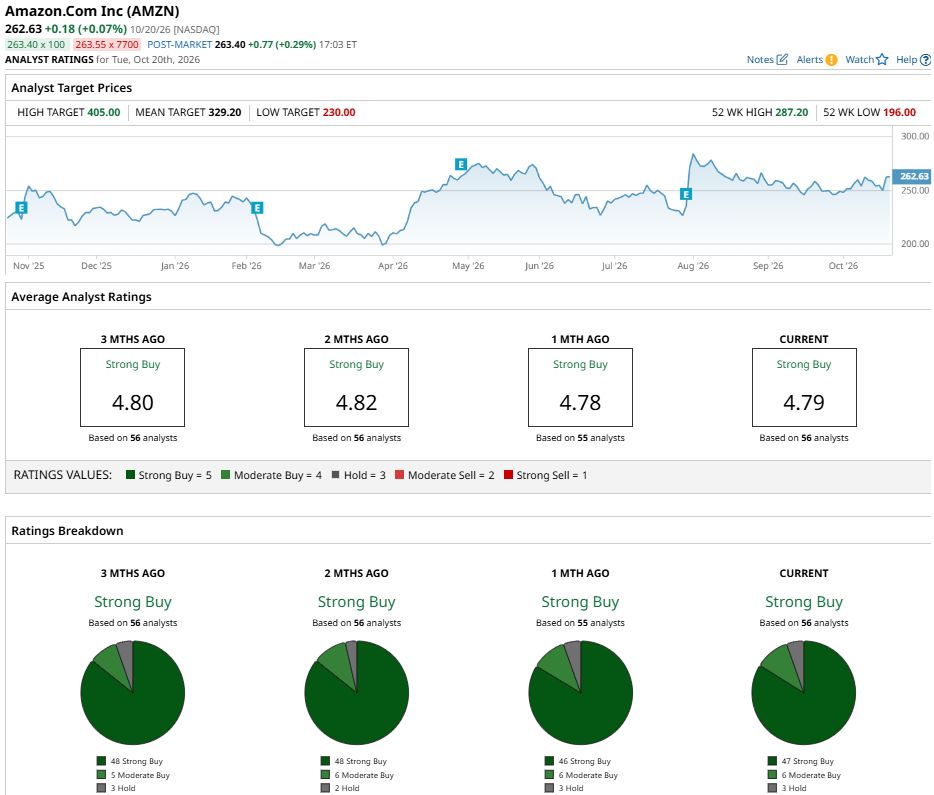
Amazon looks well positioned for long-term growth. Its “Strong Buy” consensus, $329.20 average price target, and implied 25% upside reflect confidence in AWS, AI infrastructure, advertising, and retail efficiency. The new Bee Frontier and Bee Eclipse devices further extend Amazon’s AI ecosystem into consumer hardware, subscriptions, and commerce. With 47 Strong Buy ratings among 56 analysts, AMZN remains a compelling buy for investors seeking exposure to e-commerce and artificial intelligence.
 www.barchart.com
On the date of publication, Ruchi Gupta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.