

Corpay, Inc. (CPAY) specializes in corporate payments and business spend management. Its operations span three core segments: Spend Management, which offers corporate and virtual card programs and automates procure-to-pay processes; Cross-Border, which helps businesses manage foreign exchange exposure and access multi-currency account solutions; and Vehicle Solutions, which manages expenses related to fuel, tolls, parking, and other vehicle-related costs.
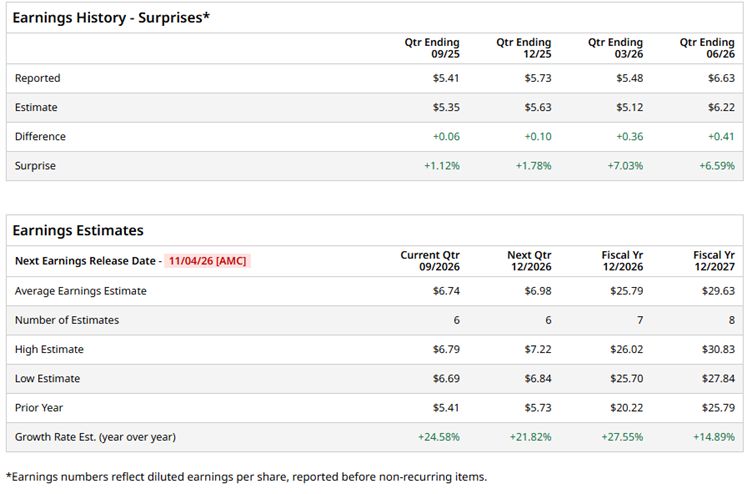
Through these services, Corpay helps businesses streamline payment processes, improve expense visibility, and manage operational spending more efficiently. With a market capitalization of roughly $26.19 billion, Corpay is gearing up to report its fiscal 2026 third-quarter results on Nov. 4, 2026, after the market closes. Wall Street expects EPS for the quarter to reach $6.74, representing a robust 24.6% increase from the year-ago quarter.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Adding to the optimism, Corpay has consistently outperformed expectations, beating analysts’ earnings estimates in each of the past four quarters. Looking ahead, the company’s earnings momentum is expected to continue, with fiscal 2026 EPS projected to climb 27.6% year over year to $25.79, followed by a further 14.9% increase to $29.63 in fiscal 2027.
 www.barchart.com
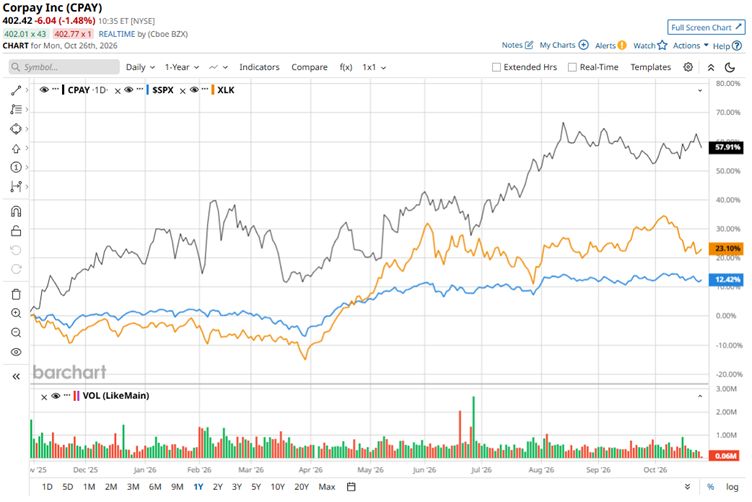
Corpay has delivered a strong performance over the past year, with its shares surging 40.1% and comfortably outpacing both the broader market and its technology-sector peers. In comparison, the S&P 500 Index ($SPX) gained 12.7%, while the State Street Technology Select Sector SPDR ETF (XLK) advanced 25.5% over the same period. Corpay’s impressive gains underscore its relative strength against both benchmarks.
 www.barchart.com
Corpay delivered a strong performance in the second quarter of fiscal 2026, reporting revenue of $1.34 billion, up 21% year over year and ahead of Wall Street’s expectations. Organic revenue growth reached 10%, marking the fifth consecutive quarter of double-digit expansion as the company continued to strengthen its corporate payments and spend management business. Adjusted net income per diluted share surged 36% to $7.00, compared with $5.13 in the year-ago quarter.
Corpay also strengthened its financial position by refinancing its debt facilities and increasing its revolving credit facility to $3.7 billion, ending the quarter with leverage of 2.55x. Meanwhile, the company continued returning capital to shareholders, repurchasing approximately 1 million shares for $321 million during the quarter.
Wall Street remains highly optimistic about Corpay, with analysts maintaining a consensus “Strong Buy” rating. Of the 18 analysts covering the stock, 12 recommend a “Strong Buy,” while the remaining six are evenly split between “Hold” and “Moderate Buy” ratings. The average price target of $455.53 suggests potential upside of 13.2% from current levels. Meanwhile, the Street-high target of $536 points to a more bullish scenario, implying a possible gain of 33.2% and leaving room for further appreciation.
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.