

Sometimes the market throws you a curveball. This is what just happened to Bloom Energy (BE) stock investors. Based in San Jose, California, the energy company recently delivered one of the best quarters in its history. Revenue more than doubled in the third quarter of fiscal 2026, while profits swung from negative to strongly positive. Management also raised its guidance for the third time this year.
However, BE stock fell after the Q3 report in a classic post-earnings selloff. This occurs when expectations exceed reality. People will bid a stock higher based on hope, then get rid of it when the numbers come out. A run-back can happen even after a very good performance if the bar was set too high.
Don’t Miss a Day: From crude oil to coffee, sign up free for Barchart’s best-in-class commodity analysis.
For Bloom Energy, the selloff raises a simple question: Is this a warning sign, or an opportunity? Let's dig into the details and see what the market might be missing.
A Wild Ride With Real Gains
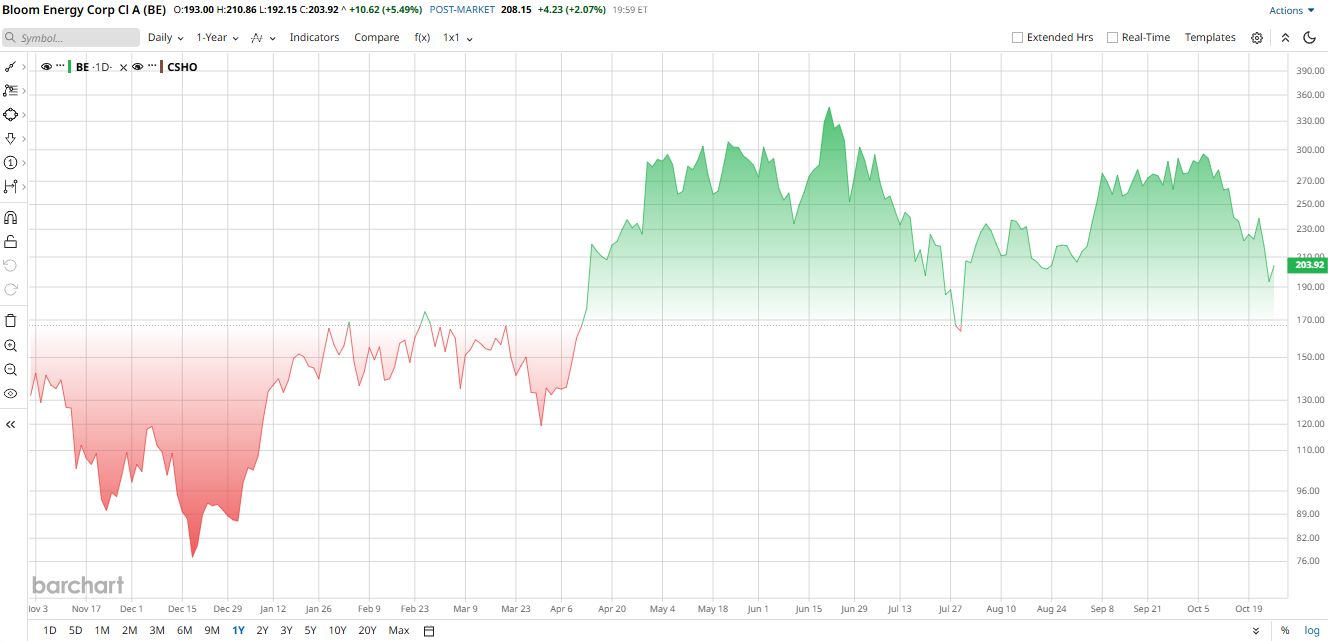
Bloom Energy stock is up 134% year-to-date (YTD) and up 59% over the past 52 weeks. The 52-week range tells the real story; BE stock has a low of $75.70 and a high of $351.28. That is the kind of volatility that tests an investor's stomach.
Demand for artificial intelligence (AI) data centers has been driving the rally. Big Tech is seeking power, and that's what Bloom provides. In September, the company also earned a spot in the S&P 500 ($SPX), causing the price of BE stock to rise as index funds purchased shares. Finally, management has continued to raise expectations.
However, BE stock plunged after Q3 earnings. The selling wasn't due to a faltering business, but rather cash flow problems. The catalysts have been very strong, but the stock is now cooling down from a big bull run.
Even with the haircut, Bloom Energy stock is still expensive. For example, the price-to-sales (P/S) ratio stands at 33 times. The market is paying up for growth, which means the company will have to continue to execute. Any stumble will be punished.
Is BE stock fairly valued? Not in a traditional sense. However, for a company with such a rapid growth rate, the premium does imply investors believe in Bloom so far.
 www.barchart.com
What the Selloff Really Means for BE Stock
Let's be clear about what exactly happened with the selloff. Bloom reported record results on Oct. 22. Revenue hit $1.24 billion, up 138% year-over-year (YOY), with product revenue crossing $1 billion for the first time. Net income landed at $250.3 million, a huge swing from a loss of $23 million a year earlier. Non-GAAP diluted EPS was $0.94, up from just $0.15 in the prior-year period.
Meanwhile, free cash flow was -$181 million for the quarter but remained positive at $42 million on a YTD basis. Bloom Energy ended the quarter with $2.5 billion in cash.
So, why did BE stock drop after earnings? Two reasons. First, investors focused on the negative free cash flow. Second, contract assets rose. Those are the real items to watch. But they are tied to growth, not weakness. Bloom is spending to build capacity, which is what a business does when demand runs ahead of supply.
“Electricity is the foundation of economic growth, human well-being and national competitiveness,” said CEO K.R. Sridhar. "Today, the world is moving from a century-old model of centralized power to a new architecture that includes firm, distributed onsite generation."
Bloom raised its full-year fiscal 2026 revenue guidance to $4.4 billion to $4.6 billion. That represents 122% YOY growth at the midpoint. Management also raised its non-GAAP EPS guidance to $3.10 to $3.40. Meanwhile, analysts expect $4.53 billion in revenue and EPS of $2.61 for the full year. Those are expectations that Bloom is generally guiding well above.
All told, the recent selloff seems like noise. The business is not broken.
What Is Bloom Energy Doing Right?
Bloom Energy has had some major developments recently. On Sept. 21, the company joined the S&P 500, which raised its profile with institutional investors. In June, the company also expanded its partnership with Brookfield Asset Management (BAM) from $5 billion to $25 billion. That is a fivefold increase in planned investment for AI power infrastructure.
Then there is the American Electric Power (AEP) and Alphabet (GOOGL) project. AEP is planning to spend about $4 billion on a 702-megawatt fuel-cell facility near Cheyenne, Wyoming that will be built with Bloom Energy technology and incorporate carbon capture. Google will be the 20-year offtaker for 100% capacity. The project will represent the first large-scale use of carbon capture with Bloom Energy's servers, while Bloom management believes carbon capture and sequestration (CCS) is a “potential trillion dollar market opportunity.”
That is not just hype, either. Large utilities and hyperscalers are taking big wagers on Bloom Energy for near-zero-carbon electricity, as utilities across the U.S. begin to see fuel cells as a viable alternative.
What Does Wall Street Think of BE Stock?
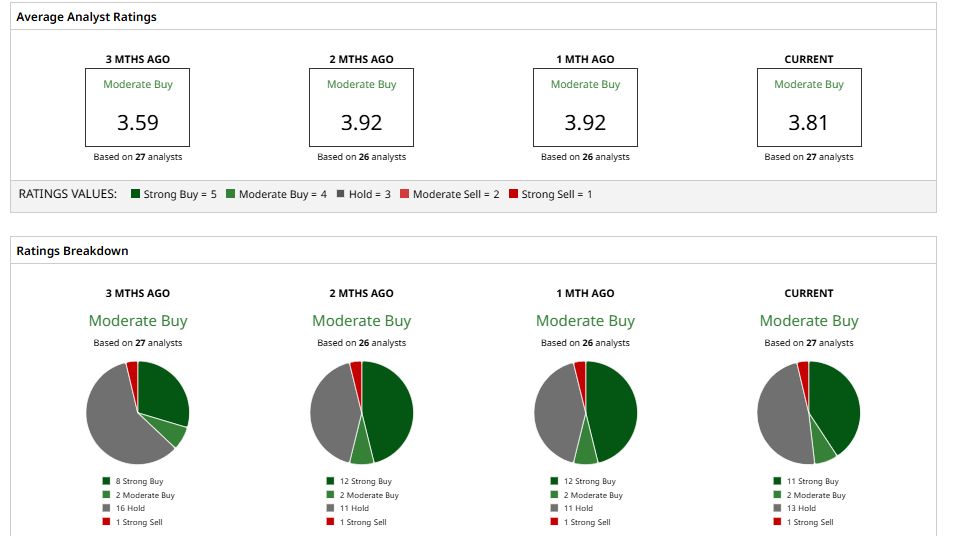
Wall Street is split on BE stock, but the bulls are loud. Morgan Stanley recently raised its price target to $335 from $310 and kept an “Overweight” rating. On the other hand, JPMorgan cut its target to $292 from $314 while keeping its “Overweight” rating. Roth also lowered its target to $230, while BTIG cut its target to $250 while keeping a “Buy” rating.
Overall, Bloom Energy stock has a consensus “Moderate Buy” rating. The average price target of $284.61 implies meaningful potential upside of 43% from current levels.
The market has not made up its mind just yet, but the selloff has not broken the bull case. Instead, the slide allowed the bears to speak up for a split second. That may be a good opportunity for investors with a longer time horizon.
 www.barchart.com
On the date of publication, Nauman Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Buying Bloom Energy Stock After Its Post-Earnings Selloff Could Be a Good Idea Why Constellation Energy Is Becoming a Bigger Part of the AI Trade This LNG Stock is Breaking Out. Here’s What I’m Watching on the Chart. What is on the Horizon for the 2026/2027 Natural Gas Withdrawal Season?