

Advanced Micro Devices (AMD) will announce its third-quarter earnings on Nov. 3. Strong demand for the company's server processors and Instinct artificial intelligence (AI) accelerators from hyperscale data centers and enterprise clients, along with an expanding addressable market, positions AMD well to deliver robust revenue and earnings growth in the quarter.
As demand for AI infrastructure and data-center computing continues to rise — and as AMD’s earnings growth accelerates — AMD stock is likely to sustain its growth trajectory even as it trades at a relatively high valuation.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
 www.barchart.com
AMD Could Crush Expectations in Q3
AMD appears well-positioned to deliver another strong quarter, supported by accelerating demand across its server CPUs, Instinct AI accelerators, and embedded products.
In Q2 2026, AMD’s top line rose 50% year-over-year (YOY) to $11.5 billion, reflecting broad-based demand across its product portfolio. The company's data-center segment was the key growth engine, increasing its share of total revenue to 58% from 42% in the same period last year.
Data-center revenue climbed 107% YOY to $6.7 billion, driven by robust demand for EPYC server processors and Instinct accelerators. The server CPU business is growing at a solid pace and is likely to sustain momentum in the coming quarters.
The data-center AI business is an important driver for AMD's growth outlook. Revenue from this business more than doubled YOY in Q2, supported by increased demand for Instinct accelerators. Adoption of the MI355X continued to broaden as major AI companies expanded deployments across training and inference workloads.
The expansion of AI workloads creates a substantial opportunity for AMD. As enterprises and cloud providers invest in AI infrastructure, demand is likely to extend beyond specialized training systems to inference applications that support the deployment of AI models at scale. A broader range of workloads could therefore expand AMD’s addressable market.
Management has indicated that, amid strong customer demand and improving supply conditions, server CPU revenue is expected to increase by more than 80% YOY in the second half of 2026. For full-year fiscal 2027, server CPU revenue is projected to grow by more than 70% YOY from a significantly higher base. The company also expects data-center segment revenue to more than double YOY in 2027.
For Q3 2026, AMD expects revenue to increase by 41% YOY to $13 billion at the midpoint. Management expects strong double-digit growth in the data-center segment to be the primary contributor, with the embedded business also expected to deliver strong growth.
The earnings outlook also appears favorable, supported by revenue expansion and improved product mix. Analysts expect earnings of $1.68 per share, reflecting a 73% YOY increase from $0.97 per share in the prior-year period.
Overall, AMD's upcoming Q3 report should reflect benefits from several favorable growth drivers, including expanding adoption of Instinct accelerators, strong demand for EPYC processors, and improving supply conditions.
Strong Earnings Justify the Elevated Valuation
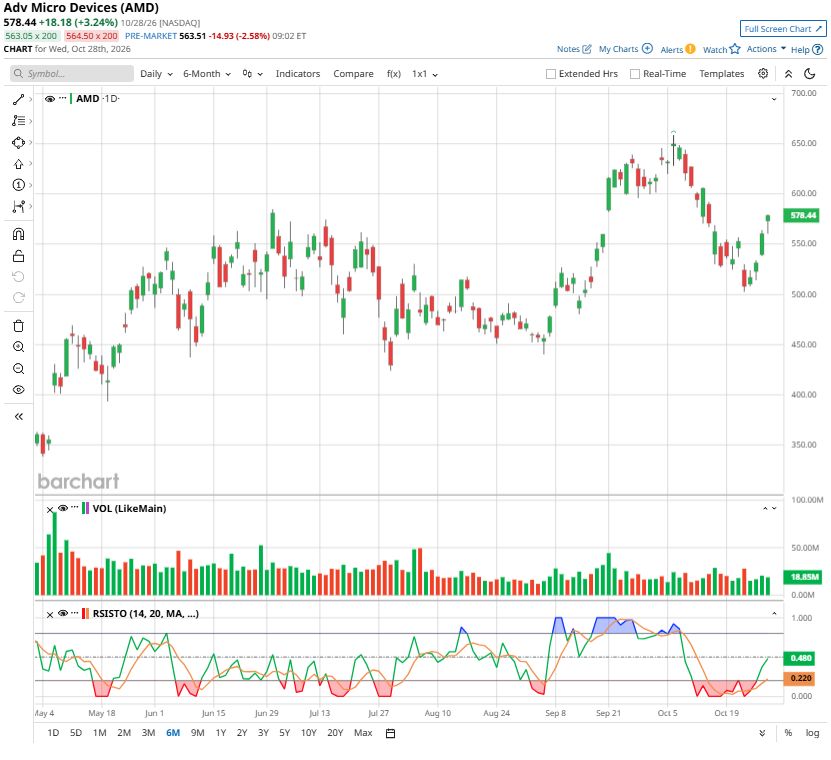
The rally in AMD stock this year has driven its valuation higher. However, AMD’s premium multiple is warranted, as it is likely to deliver solid earnings growth. AMD stock currently trades at a forward price-to-earnings (P/E) ratio of 89 times. Although this multiple is significantly higher than Nvidia's (NVDA) forward P/E ratio, it still appears justified given AMD's EPS growth forecast.
Analysts project EPS to grow by more than 117% in fiscal 2027. Beyond the near-term outlook, AMD stands to benefit from increasing investment in AI infrastructure, high-performance computing (HPC), and advanced data-center processors. These structural growth drivers could help the company outperform its previous growth outlook.
At its Financial Analyst Day last year, AMD outlined expectations for revenue to grow at a compound annual growth rate (CAGR) exceeding 35% over the next three to five years, along with a target of $20 in annual EPS. Stronger-than-anticipated adoption of its AI and computing products positions the company to surpass its projections and supports the stock's premium valuation.
Is AMD Stock a Buy?
The Q3 report will likely reflect strong growth momentum, supported by rising demand and expanding AI infrastructure spending. AMD's revenue and earnings outlook suggests solid potential upside, while long-term growth targets support its investment case.
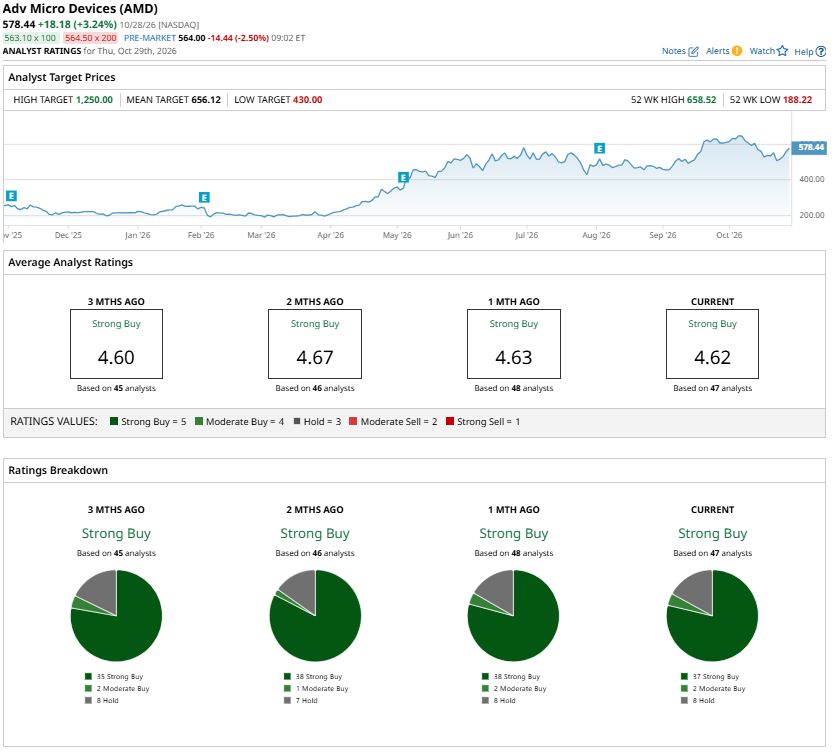
A strong earnings release and upbeat forward guidance could continue to support the rally. Overall, analysts maintain a consensus “Strong Buy” rating on Wall Street, reflecting optimism around AMD"s growth prospects.
 www.barchart.com
On the date of publication, Sneha Nahata did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
What to Expect From AMD’s Q3 Earnings How Investors Should View the Launch of Alphabet's Gemini 4 Carbon ASML vs. Applied Materials: One Is Growing Twice as Fast, but I’d Buy The Other Instead Why Dumping Uber Stock Before Q3 Earnings May Not Be the Smartest Move