

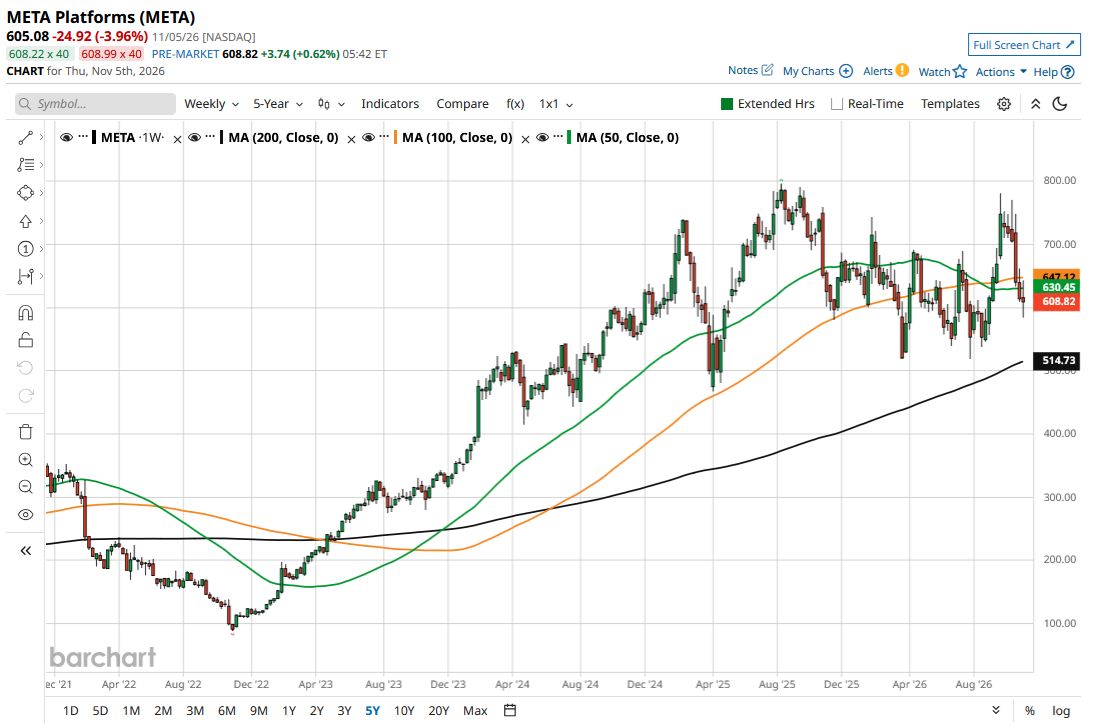
The tech rout that began during the Q3 earnings season has deepened following the midterm results. Specifically, Meta Platforms (META) has lost 18% over the last month and pared the gains it made in September, its best month since 2022.
Meta Stock Falls Towards $600 Amid Tech Sell-Off
Meta’s Q3 earnings were a dampener, much like its Magnificent 7 peers, which all fell after their respective earnings calls amid growing angst over artificial intelligence (AI) capex. It did not help that the Mark Zuckerberg-led company announced a $97.5 billion capital raise days after denying any immediate plans during the earnings call. As I noted in the company’s post-earnings analysis, a capital raise looked imminent after the company announced plans to issue a new class of shares, but the announcement came a lot sooner than I expected.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Meta’s sell-off gained pace as markets whipsawed after the midterm results. I previously noted that Meta was a “Hold” following the Q3 earnings. With the stock now dipping further towards $600 levels, let’s explore whether it is a “Buy” now or whether investors are better off staying on the sidelines.
 www.barchart.com
What’s Going Right for Meta?
To begin with, let’s examine what’s going right with Meta. Its core business is doing incredibly well, with its ads business reporting a 26% year-over-year increase in Q3 revenues, which, for context, was over twice that of Google Search. Digging deeper, Meta’s ad revenues totaled $63.06 billion in the quarter, which is only a tad short of the $63.5 billion Google Search generated. While Alphabet (GOOG) (GOOGL) also got over $11 billion in revenue from YouTube, Meta’s ad business has caught up with Google Search fast.
Meta’s topline has been growing the fastest among its Mag 7 peers, with the notable exception of Nvidia (NVDA), whose revenue growth has been on a trajectory of its own amid the AI infrastructure buildup.
Meta’s Muse is off to a strong start, and during the Q3 earnings call, the company said that over 10 million people in the U.S. and Canada have set up a personal assistant in just about one and a half months since its launch. Additionally, Meta said that its Reality Labs' losses have peaked and would come down going forward. These losses have been eating into the otherwise fat earnings that the company has been generating.
In terms of valuations also, Meta trades at a forward price-to-earnings (P/E) multiple of 21.4x, which I would say is reasonable, although not mouthwateringly cheap.
What Might Not Go in Meta’s Favor
Looking at the flip side, Meta’s business is the most concentrated among its Mag 7 peers, and it gets almost all of its revenues from the ad business. While the company has pivoted to subscriptions and the business should see healthy growth as it starts charging customers for AI models, for now it is heavily dependent on the ads business.
Another concerning aspect is Meta’s 2026 capex, which, as a percentage of the expected 2026 revenues, is the highest among its Mag 7 peers. While AI has been an enabler of Meta’s growth, markets are getting increasingly apprehensive of the burgeoning capex, which has turned tech companies' cash-rich operations to one that needs external funding.
Meta has reserved its 2027 capex guidance for the Q4 earnings call, but S&P Global expects it to soar to $225 billion, which would imply a 55% increase compared to the upper end of the company’s 2026 forecast.
Then there are legal woes. Despite agreeing to a $18 billion agreement with almost every U.S. state, Meta’s legal worries over youth-related issues aren’t over yet, and several such trials are scheduled to begin in the U.S. in the coming months. Scrutiny over data privacy and youth-related issues could only increase in the coming months as Democrats assert more authority after flipping both the House and the Senate.
All said, I believe Meta seems to offer reasonable value near $600 price levels. While I am wary of loading up on tech names and am keeping some powder dry for any further weakness, I believe Meta can be nibbled at these levels.
On the date of publication, Mohit Oberoi had a position in: META , NVDA , GOOG . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Oracle Just Walked Away From a $7 Billion Tencent Deal. Here’s What It Means for ORCL Stock. Nvidia Is Now Down for the Year After a Sharp Selloff. You Can Buy NVDA Stock Gradually, but Don’t Rush In. Meta Stock Dips Towards $600 But Don’t Load Up Just Yet Airbnb Soars Over 11% After Strong FCF Results - What's the Best ABNB Play Now?