

Akamai Technologies, Inc. (AKAM), headquartered in Cambridge, Massachusetts, provides security, delivery, and cloud computing solutions. Valued at $12.1 billion by market cap, the company provides services for accelerating and improving the delivery of content and applications over the internet, ranging from live and on-demand streaming video capabilities to conventional content on websites, to tools that help people transact business and reach out to new and existing customers.
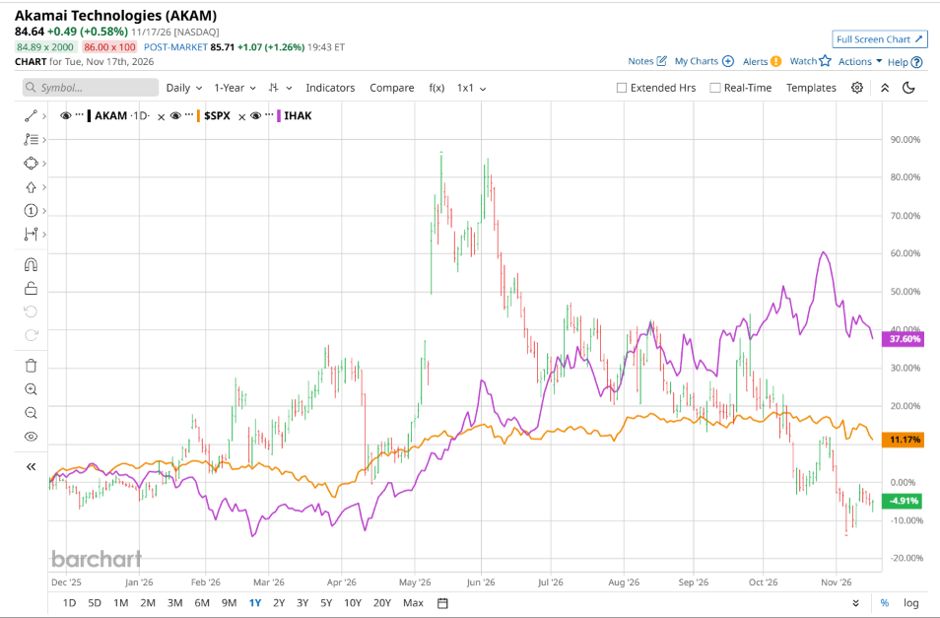
Shares of this cybersecurity and cloud computing company have underperformed the broader market over the past year. AKAM has declined 3.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10%. In 2026, AKAM stock is down 3%, compared to SPX’s 7.2% rise on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Narrowing the focus, AKAM’s underperformance is also apparent compared to the iShares Cybersecurity and Tech ETF (IHAK). The exchange-traded fund has gained about 34.2% over the past year. Moreover, the ETF’s 37.5% returns on a YTD basis outshine the stock’s single-digit losses over the same time frame.
 www.barchart.com
AKAM’s underperformance has been driven by heavy front-loaded capital expenditures to build out data center space, power, and hardware for multi-year Cloud Infrastructure Services (CIS) agreements like its $11.6 billion contract with Anthropic, which temporarily compressed operating margins and free cash flow before revenues fully ramp up. At the same time, this transition was compounded by structural declines in legacy delivery services, alongside minor supply chain and data center rollout delays that shifted expected CIS revenue capture into future periods and prompted conservative near-term guidance revisions.
On Nov. 5, AKAM shares tumbled 9.4% after reporting its Q3 results. Its adjusted EPS of $1.77 exceeded Wall Street expectations of $1.67. The company’s revenue was $1.1 billion, meeting Wall Street forecasts. AKAM expects full-year adjusted EPS in the range of $6.47 to $6.68, and revenue ranging from $4.4 billion to $4.5 billion.
For the current fiscal year, ending in December, analysts expect AKAM’s EPS to fall 19.5% to $3.55 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimates in two of the last four quarters while missing the forecast on two other occasions.
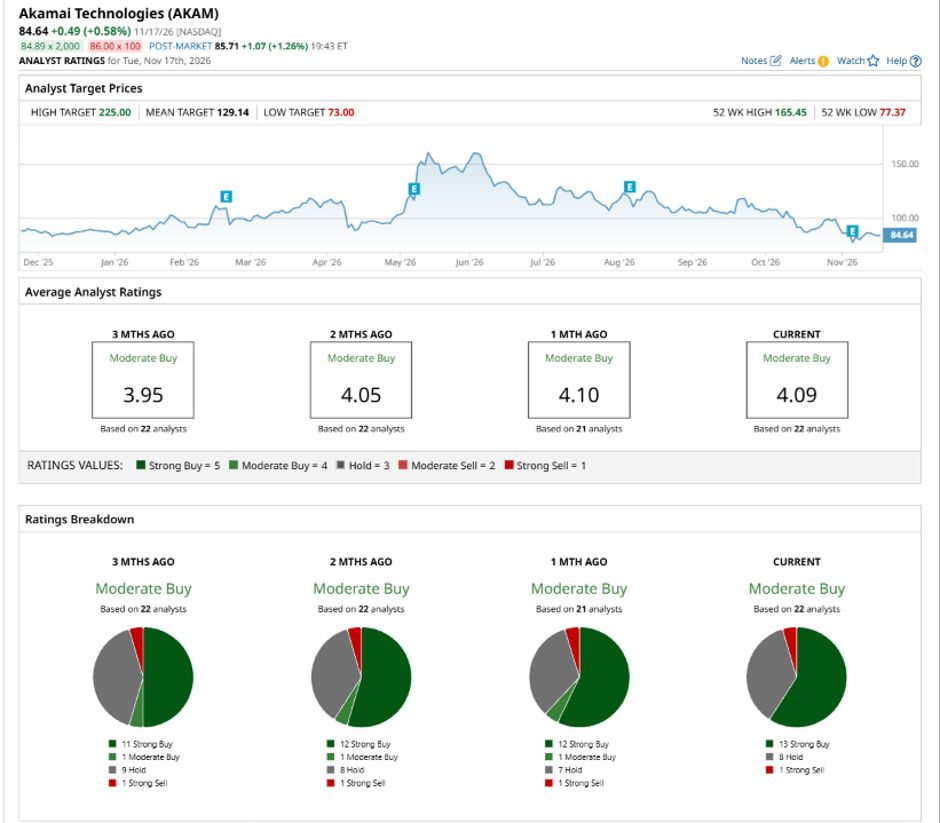
Among the 22 analysts covering AKAM stock, the consensus is a “Moderate Buy.” That’s based on 13 “Strong Buy” ratings, eight “Holds,” and one “Strong Sell.”
 www.barchart.com
This configuration is more bullish than a month ago, with 12 analysts suggesting a “Strong Buy,” and one advising a “Moderate Buy.”
On Nov. 11, Evercore Inc. (EVR) downgraded AKAM to an “In Line” rating with a price target of $90, implying a potential upside of 6.3% from current levels.
The mean price target of $129.14 represents a 52.6% premium to AKAM’s current price levels. The Street-high price target of $225 suggests an ambitious upside potential of 165.8%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Turn Coca-Cola into an Income Machine with This Options Play Nasdaq Futures Rally as Upbeat Nvidia Earnings Revive AI Trade; FOMC Minutes on Tap Realty Income vs. Agree Realty: Which REIT Wins on Dividends and Growth? Bill Gates Has Earned $2.6 Billion in Dividends From a Landfill Stock the EPA Keeps Citing for Methane Leaks, and a Filing Shows He Just Bought 3.7M More Shares