

Berkshire Hathaway (BRK.A) saw a leadership transition earlier this year when Greg Abel took over as CEO, succeeding the legendary Warren Buffett. Days after Abel took over, Berkshire Hathaway registered to sell its entire 27.5% stake in Kraft Heinz (KHC).
The registration did not necessarily mean Berkshire would sell KHC shares, and so far, the conglomerate has stayed put. However, the registration did kickstart a formal process and signaled an intent to exit an investment that Buffett has counted among his mistakes. In fact, Buffett previously admitted to overpaying for Kraft during the merger with Heinz.
More Yield, Less Trap: Sign up free to get Barchart’s daily Dividend Investor newsletter straight to your inbox.
KHC Is Among the Highest-Yielding S&P 500 Stocks
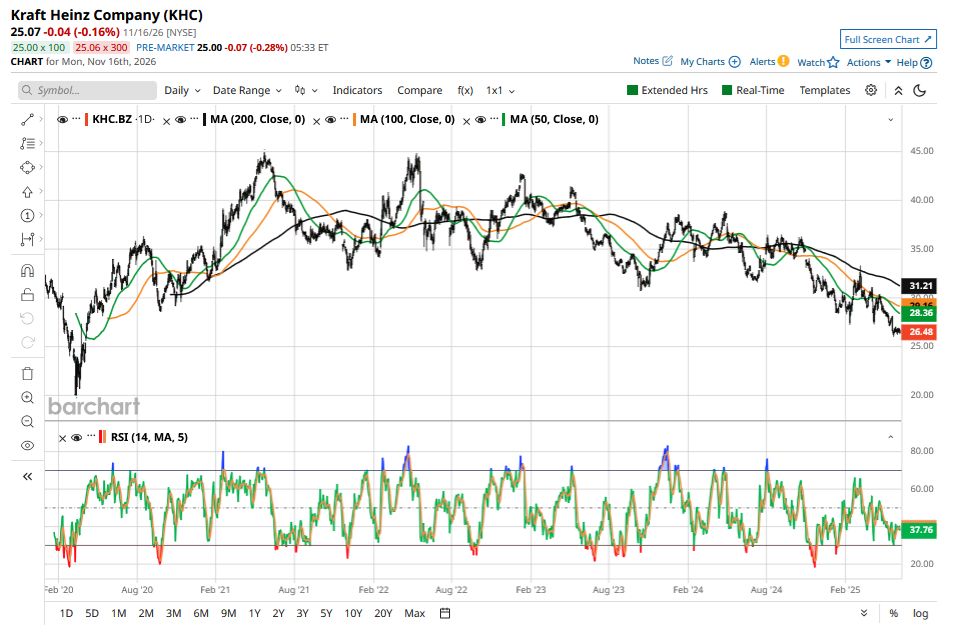
When the merged entity started trading in 2015, KHC stock opened at $71 per share. Shares peaked in 2017 and have since lost around 70% of value. Meanwhile, the stock also commands a dividend yield of nearly 6.4% and is among the highest-yielding stocks of the S&P 500 Index ($SPX).
 www.barchart.com
Last year, I noted that while KHC wasn’t a screaming buy, its valuations were undemanding and would put a floor under the stock. Kraft Heinz is now trading slightly below those levels. With that in mind, let's discuss whether it's time to buy KHC stock, or if investors are better off staying away from the underperforming shares.
Kraft Heinz Expects to Return to Growth Only in 2028
Kraft Heinz has been plagued by multiple issues and has slackened on innovation. The company has been losing U.S. market share amid intensifying competition from private labels as well as newer brands, including those backed by celebrities and influencers. Legacy brands like Kraft Heinz no longer enjoy the kind of moat and pricing power they once did and are now discovering it the hard way.
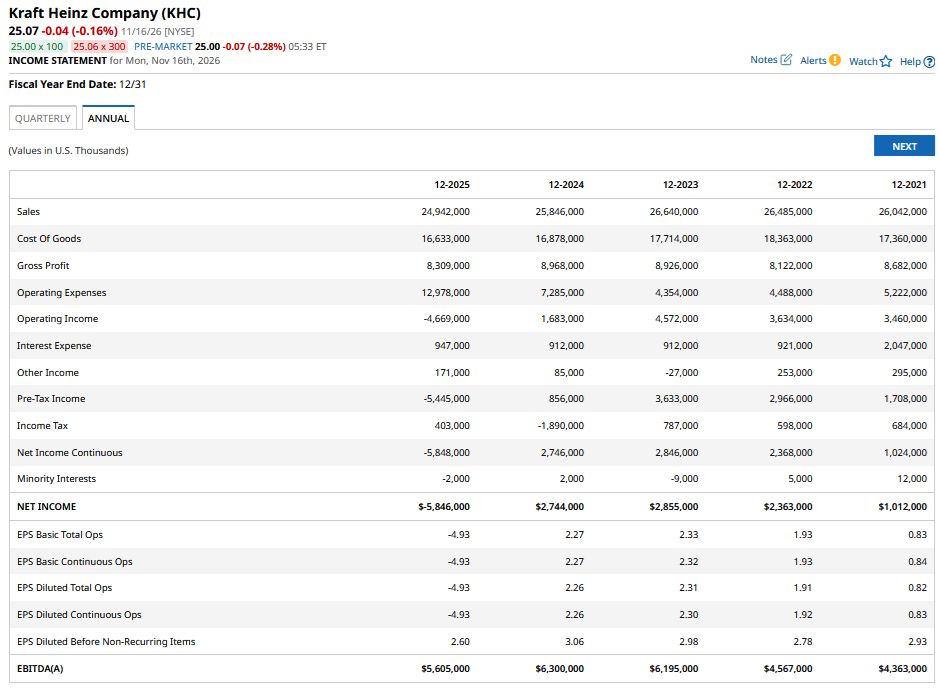
Kraft Heinz’s volumes have been falling, and despite the price hikes, revenue fell in both 2024 and 2025. Analysts are modeling sales to drop by low single digits this year as well.
At its Investor Day earlier this month, management said that it expects organic net sales to be “relatively flat” in 2027. The company expects the first half to be tough but is projecting growth in the back half of the year. However, the company also expects adjusted operating income to drop in the low single-digits next year. That said, Kraft Heinz forecast “consistent top-line growth and margin expansion” in 2028 and expects to deliver double-digit total returns to shareholders in 2029 “with a balanced contribution from earnings growth and capital returned.”
 www.barchart.com
Kraft Heinz Is Eyeing a Turnaround
As I often say, “turnaround” is a much-abused term in corporate America, but now even Kraft Heinz is attempting one. The company was previously eyeing a breakup but has since shelved those plans and is instead looking at portfolio realignment.
Earlier this month, the company announced a deal to divest its North American coffee business. Kraft Heinz will receive $500 million post-tax from the deal and maintain a 30% non-controlling interest in the business. According to CEO Steven Cahillane, who took over earlier this year, the company is open to more such transactions to make its portfolio “more growth oriented.”
Cahillane has admitted that Kraft Heinz made the mistake of resting on its past laurels. The CEO not only halted plans to split the company but went on the offensive, announcing a $700 million investment, with much of that focused on marketing.
Should You Buy Kraft Heinz Stock?
Analysts have appreciated Kraft Heinz’s turnaround actions but don’t foresee a quick fix. Overall, KHC stock has a consensus “Hold” rating. Out of 20 analysts with coverage, one has a “Strong Buy” rating, one has a “Moderate Buy,” 14 have a “Hold” rating, one analyst has a “Moderate Sell," and three have a “Strong Sell” rating. The mean target price of $24.39 is below current levels near $25 per share.
It is tough to make a compelling case for KHC stock even at its depressed forward price-to-earnings (P/E) multiple of 12 times and a dividend yield that’s nearly 6 times the average S&P 500 constituent. At best, Kraft Heinz stock looks like a “Hold” to me, and the same should go for investors looking at high-dividend stocks.
On the date of publication, Mohit Oberoi did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Berkshire Might Give Up on This High-Yielding Dividend Stock. You Maybe Should Too. This Company (10%+ Yield) Has a Giant Presence, But It Carries Giant Risks. Stay Away from the Value Trap. You Likely Haven’t Heard of This Hot Stock, But Its Roots Date Back to 1816 Realty Income vs. Agree Realty: Which REIT Wins on Dividends and Growth?