

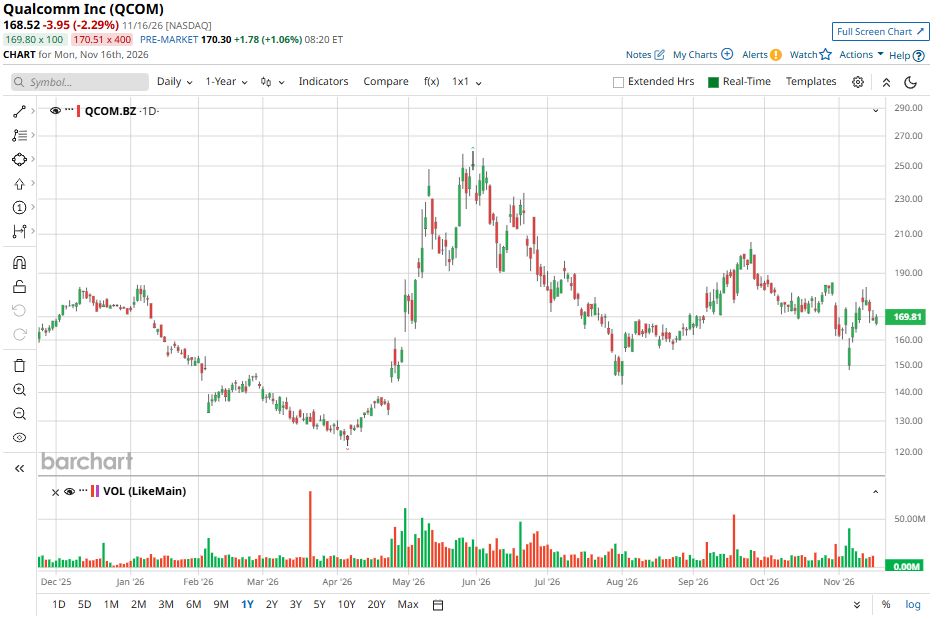
Qualcomm (QCOM) stock has been under pressure, declining more than 38% from its 52-week high. The loss of Apple (AAPL) revenue and the adverse impact of rising memory costs on its handset business have weighed on its revenue and profitability.
The impact is evident in the company's fiscal 2026 results. Qualcomm reported revenue of $43.1 billion, down 3% from $44.3 billion in fiscal 2025. The company's core Qualcomm CDMA Technologies (QCT) business also saw revenue decline 3% year-over-year (YOY), largely due to weaker handset sales. However, strength in the automotive and Internet of Things (IoT) businesses supported its top line, while revenue from its Qualcomm Technology Licensing (QTL) segment remained broadly flat.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Profitability also took a hit. Adjusted EPS fell 12% YOY to $12.03 in fiscal 2026, reflecting weaker handset performance and continued margin pressure.
Despite these near-term challenges, there are reasons to remain optimistic about Qualcomm’s prospects. Much of the negative news is already reflected in the price of QCOM stock. At the same time, its growing pipeline of opportunities across automotive, IoT, data center, and other markets provides a solid base for growth.
 www.barchart.com
Qualcomm Is Set for Stronger Growth
Qualcomm entered fiscal 2027 strong, supported by its strategic shift toward revenue diversification, a solid data-center revenue opportunity, and ongoing strength in automotive.
Qualcomm expects non-handset revenues within its QCT segment — which is comprised of automotive, IoT, and data center — to increase by more than 60% YOY. These businesses are also projected to contribute more than 50% of total QCT revenues during the fiscal year, highlighting Qualcomm's gradual transition away from its traditional dependence on the smartphone market.
The data-center business is expected to become a significant growth contributor as Qualcomm moves from customer engagements to commercial shipments. Management has reaffirmed its revenue targets of $5 billion for fiscal 2027 and $15 billion for fiscal 2029, with the business expected to exit fiscal 2027 at an annualized revenue run rate (ARR) of approximately $7 billion. Initial shipments to two hyperscaler customers are expected to help generate more than $650 million in data-center revenue in the December quarter.
Furthermore, Qualcomm's strategic agreement with Amazon's (AMZN) Amazon Web Services presents a revenue opportunity of up to $60 billion over the next decade, while additional engagements with hyperscalers could further strengthen its long-term growth pipeline.
Qualcomm's automotive business is also demonstrating strong momentum, achieving an $8 billion ARR by the end of fiscal 2026. At the same time, investments in agentic artificial intelligence (AI), AI accelerators, and CPU platforms are positioning the company to capitalize on emerging computing requirements and create new product opportunities.
In QTL, Qualcomm has completed long-term agreements with major customers, including Apple, Huawei, and Transsion. These renewals provide greater revenue visibility and reduce near-term licensing uncertainty, while management expects the long-term QTL revenue outlook to remain unchanged. Additionally, planned product price increases to offset higher semiconductor input costs are expected to support QCT gross margins, with the full benefits likely to materialize in the second half of fiscal 2027.
Overall, Qualcomm's prospects remain solid, driven by a structural shift toward a more diversified revenue base. Expanding data-center operations, resilient automotive demand, AI-related investments, and stable licensing revenues provide multiple growth drivers.
Qualcomm's Diversified Growth Story Makes the Pullback Worth Buying
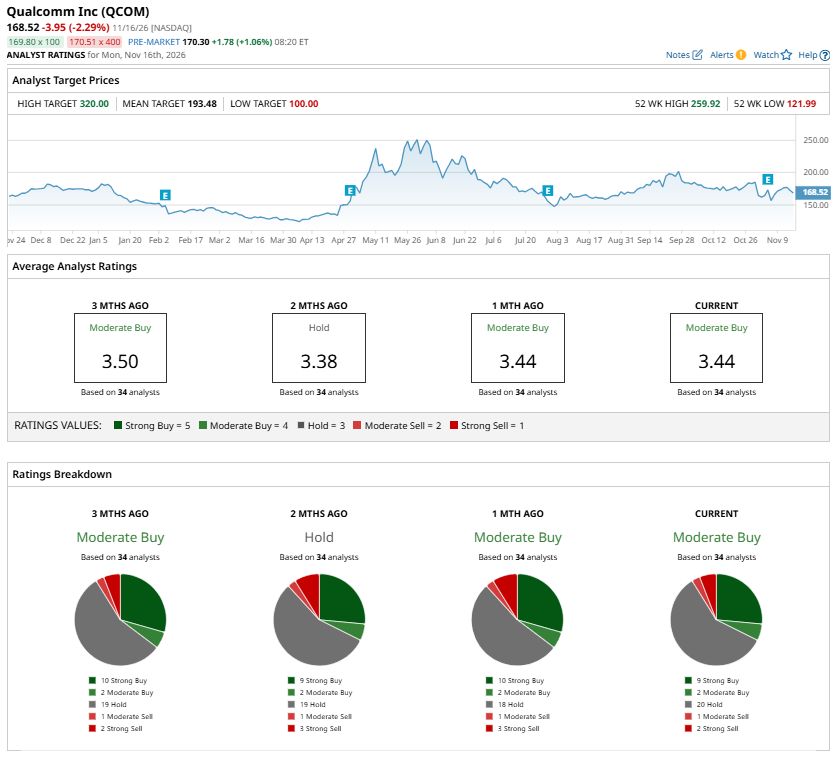
Wall Street analysts have a consensus “Moderate Buy” rating for QCOM stock. However, the pullback presents an attractive opportunity for long-term investors, as Qualcomm's growth prospects extend well beyond the challenged smartphone market. Although the loss of Apple-related revenue, weaker handset demand, and rising memory costs have weighed on its recent financial performance, the company’s expanding automotive, IoT, and data-center businesses offer meaningful growth opportunities.
Moreover, renewed licensing agreements and planned product price increases should provide additional support to revenue visibility and margins. While near-term volatility may persist, Qualcomm’s expanding growth pipeline and strategic positioning in AI infrastructure strengthen its investment case.
 www.barchart.com
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
How to Play SNDK Stock After Sandisk’s 8-for-1 Stock Split Why It’s Time to Buy the Pullback in Qualcomm Stock Ahead of Bending Spoons Earnings, Here's What Barchart Data Says Comes Next for BSP Stock Anthropic's $1.5 Trillion IPO Turns Ashton Kutcher's Fund Into a $7 Billion Winner — But Not Kutcher Himself