

Freeport-McMoRan Inc. FCX saw its earnings jump in the second quarter on significantly higher realized metal prices, but remains exposed to cost pressures. Its second-quarter unit net cash costs climbed 74% year over year to $1.97 per pound due to lower copper volumes.
Freeport expects unit net cash costs of $2 per pound for the third quarter, while projecting a full-year average of roughly $1.9 (compared with $1.65 in 2025). The projected third-quarter unit cost reflects a roughly 43% year-over-year increase.
The uptick in costs reflects higher costs of energy and other consumables due to the Middle East conflict and persistent pressure on volumes. Higher costs are expected to weigh on the company's margins.
FCX’s copper sales volumes tumbled approximately 30% year over year in the second quarter to 710 million pounds. The downside primarily resulted from lower operating rates during the phased ramp-up of the Grasberg Block Cave mine in Indonesia, following the mud rush incident in September 2025. The company’s third-quarter outlook for copper sales volumes of 750 million pounds indicates a sequential improvement but a 23% year-over-year decline.
Among FCX’s peers, Southern Copper Corporation SCCO reported lower unit costs in the second quarter. Southern Copper’s operating cash cost per pound of copper, net of by-product revenue credits, fell by roughly 17% from the prior-year quarter. SCCO attributed the decline to higher by-product revenue credits.
BHP Group Limited’s BHP Escondida operation reported a 10% year-over-year decline in unit costs to $1.07 per pound in fiscal 2026. Unit costs at BHP’s Spence operation rose 4% to $2.15 per pound. BHP also reported Copper South Australia’s unit cost of $0.32 per pound, down 73% year over year.
The Zacks Rundown for FCX
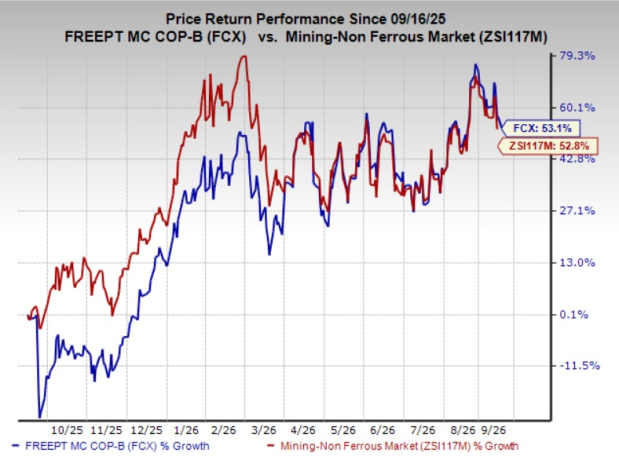
Shares of Freeport are up 53.1% in the past year against the Zacks Mining - Non Ferrous industry’s rise of 52.8%.
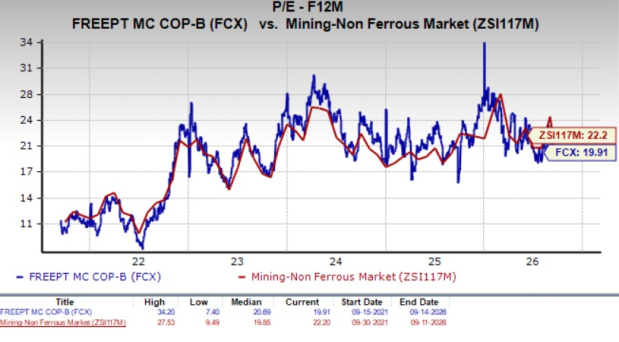
From a valuation standpoint, FCX is currently trading at a forward 12-month earnings multiple of 19.91, a 10.3% discount to the industry average of 22.2X. It carries a Value Score of C.
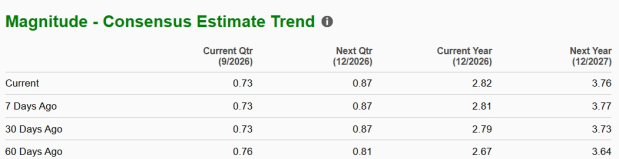
The Zacks Consensus Estimate for FCX’s 2026 and 2027 earnings implies a year-over-year rise of 59.3% and 33.2%, respectively. The EPS estimates for 2026 and 2027 have been trending higher over the past 60 days.
FCX stock currently carries a Zacks Rank #3 (Hold).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Freeport-McMoRan Inc. (FCX): Free Stock Analysis Report
BHP Group Limited Sponsored ADR (BHP): Free Stock Analysis Report
Southern Copper Corporation (SCCO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).