

Shares of Willis Towers Watson Public Limited Company WTW are trading at a discount compared with the industry. Its forward price-to-earnings multiple of 14.73X is lower than the industry average of 15.32X.
The leading global advisory, broking and solutions company has a market capitalization of $30.1 billion. The average volume of shares traded in the last three months was 0.6 million. The insurer’s earnings have a solid track record of beating estimates in each of the last four quarters, with an average of 3.9%.
Image Source: Zacks Investment Research
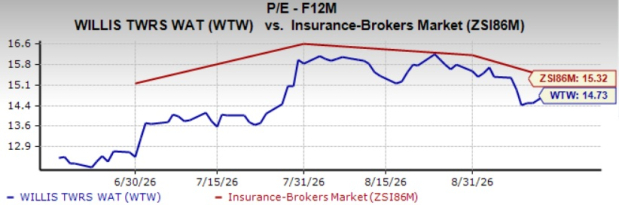
Shares of other insurance brokers like Aon plc AON, Arthur J. Gallagher & Co. AJG and Brown & Brown, Inc. BRO are also trading at a discount to the industry average.
WTW’s Price Performance
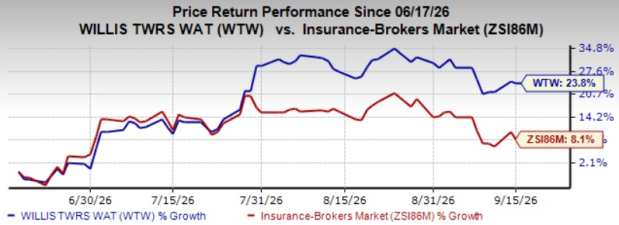
Willis Towers Watson's shares have rallied 23.8% in the past three months compared with the industry’s growth of 8.1%.
Continued margin expansion, AI-driven productivity initiatives, a strong specialty business pipeline and disciplined capital returns supported WTW’s performance.
Image Source: Zacks Investment Research
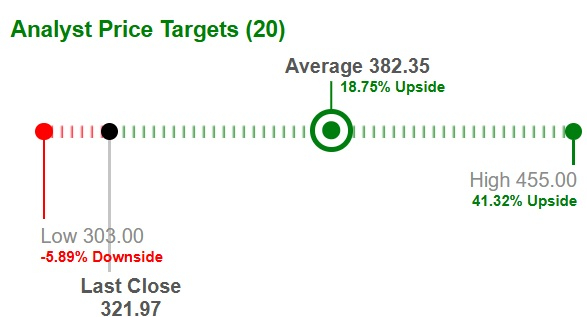
WTW's Average Target Price Suggests Upside
Based on short-term price targets offered by 20 analysts, the Zacks average price target is $382.25 per share. The average suggests a potential upside of 18.1% from the last closing price.
Image Source: Zacks Investment Research
WTW’s Growth Projection Encourages
The Zacks Consensus Estimate for Willis Towers Watson's 2026 earnings per share (EPS) indicates a year-over-year increase of 16%. The consensus estimate for 2026 revenues is pegged at $10.51 billion, implying a year-over-year improvement of 8.2%.
The consensus estimate for 2027 EPS and revenues indicates an increase of 14.4% and 4.9%, respectively, from the corresponding 2026 estimates.
Expected long-term earnings growth is pegged at 17.6%, above the industry average of 14.5%.
Optimistic Analyst Sentiment on WTW
The company has witnessed 11 upward earnings estimate revisions for 2026 over the past 60 days, while 2027 has observed 10 upward earnings estimates with no downward revisions. Thus, the Zacks Consensus Estimate for 2026 and 2027 moved 1.8% and 3.5% north, respectively, over the same period.
WTW's Efficient Use of Shareholder Funds
Willis Towers Watson’s return on equity of 22.2% for the trailing 12 months compared favorably with the industry’s 19.1%, reflecting the company’s efficiency in utilizing shareholders’ funds.
Factors That Benefit WTW
WTW continues to benefit from solid organic growth across its key businesses, driven by strong client retention, new business wins and demand for risk-management and advisory services. In the second quarter of 2026, organic revenues increased 5%, led by 7% growth in Risk & Broking and 6% growth in Insurance Consulting & Technology. A strong specialty business pipeline and growing demand for specialized risk solutions should further support organic growth.
WTW's AI strategy and margin expansion remain key long-term growth drivers. The company is extending its efficiency program through Propel, a two-year plan to embed AI and automation across its operations. Management expects AI-driven automation and analytics to improve productivity, strengthen client engagement and expand margins. These initiatives are expected to increasingly benefit margins from 2027, with the company targeting an adjusted operating margin of approximately 30% by 2028.
WTW continues to expand its capabilities and reach through acquisitions. The acquisition of Newfront strengthens its presence in the middle-market and adds technology and specialized expertise. Newfront is expected to contribute about $250 million in post-close revenues in 2026, with an adjusted EBITDA margin of nearly 26%. Its technology has also been integrated into WTW’s Neuron platform, while cost synergies are tracking ahead of plan. Cushon strengthens WTW’s U.K. retirement business, while SMB Scala & Mansutti expands its broking capabilities in Italy. These acquisitions broaden WTW’s client base and create new growth opportunities.
Rising healthcare costs and increasing benefit complexity are driving demand for WTW's health consulting. During the second quarter of 2026, the health segment revenue grew 8%. Management expects high-single-digit growth for 2026.
Willis Towers Watson's solid balance sheet and steady cash flow are expected to support capital deployment through buybacks, dividend payouts, debt repayments and acquisitions. Free cash flow increased 65.9% year over year to $360 million, primarily driven by operating margin expansion. WTW repurchased about 1.7 million shares for $450 million during the second quarter and expects share repurchases of $1 billion or more in 2026.
Risks for WTW
WTW faces intense competition and softer insurance rates, which could pressure commission growth and increase client acquisition costs.
Unfavorable exchange-rate movements could negatively impact earnings and operating results despite the company's hedging programs. Management expects foreign currency to provide an additional 5-cent tailwind in the second half of 2026, bringing the full-year benefit to approximately 35 cents.
Conclusion
WTW boasts growth through organic growth, AI initiatives, specialty insurance expansion, the Newfront acquisition, strong liquidity, effective capital deployment and continued margin improvement. However, intense competition, softer insurance pricing and foreign exchange volatility remain key risks.
Given its solid growth projections, optimistic analyst sentiment, cheap valuations and favorable ROE, it is wise to retain this Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Willis Towers Watson Public Limited Company (WTW): Free Stock Analysis Report
Aon plc (AON): Free Stock Analysis Report
Arthur J. Gallagher & Co. (AJG): Free Stock Analysis Report
Brown & Brown, Inc. (BRO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).