

Huntsman Corporation’s HUN improving margins, downstream portfolio expansion, cost savings and potential merger synergies provide support for earnings recovery.
However, weak construction demand, tariff uncertainty and input-cost volatility remain key risks, suggesting a balanced outlook as investors monitor execution and end-market recovery.
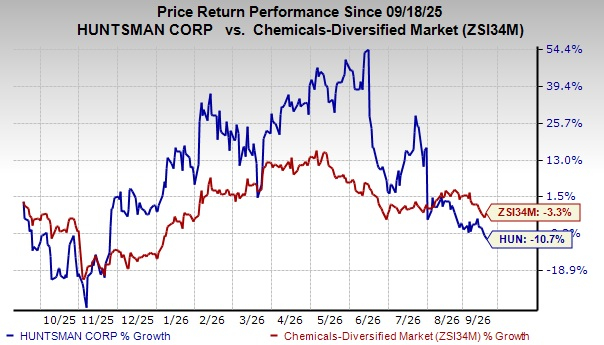
The company’s shares have lost 10.7% over a year compared with the industry’s 3.3% fall.
Let’s find out why HUN stock is worth retaining at the moment.
Huntsman Expands Higher-Margin Polyurethanes With Demilec
Huntsman continues shifting its Polyurethanes portfolio toward differentiated downstream systems, which generally offer higher margins and lower earnings volatility, while prioritizing value over upstream volume. In the second quarter of 2026, Polyurethanes revenue increased 16% year over year, while adjusted EBITDA more than doubled to $66 million, driven by higher MDI (methylene diphenyl diisocyanate) pricing across all three regions and stronger volumes in the Americas and Europe. Management expects third-quarter adjusted EBITDA of $60-$75 million, supported by stable demand, improving industrial activity and cost savings, partly offset by weak construction. Long-term growth remains linked to insulation, energy efficiency and material substitution.
The Demilec acquisition expanded Huntsman’s North American spray polyurethane foam insulation platform and increased the conversion of upstream polymeric MDI into specialized downstream systems. Huntsman expects the integration to improve margin consistency, with the combined business targeted to generate EBITDA margins above 25% and double-digit growth. This supports the broader strategy of increasing differentiated Polyurethanes exposure and reducing sensitivity to commodity MDI cycles.
Huntsman Expands Downstream Portfolio and Cuts Costs
Acquisitions of Icynene-Lapolla, CVC Thermoset Specialties and Gabriel Performance Products have expanded Huntsman’s downstream Polyurethanes and Advanced Materials businesses. These deals added formulation capabilities and specialty products across insulation and advanced polymer applications. In the second quarter, Advanced Materials revenue rose 19% year over year and adjusted EBITDA increased 42%, supported by stronger aerospace, power and automotive volumes and a more favorable sales mix.
Huntsman is reducing structural costs through site closures, shared services and workforce reductions. The program reached a $120 million annualized run rate in the second quarter, above its $100 million target. Management expects more than $50 million of 2026 in-year benefits, with cumulative savings exceeding $100 million in 2026 and $120 million in 2027. About 500 job reductions and multiple closures are planned, already helping profitability by lowering fixed costs and offsetting cyclical and input-cost volatility.
Olin-Huntsman Merger Clears Key Regulatory Hurdle
Olin Corporation OLN and Huntsman have cleared a key hurdle toward their proposed all-stock merger, as the U.S. Hart-Scott-Rodino waiting period has expired. The companies are still awaiting additional regulatory approvals.
The merger would create OlinHuntsman Corporation, a North American chemicals company with about $12.5 billion in 2025 revenues, combining Olin’s chlor-alkali and feedstock operations with Huntsman’s specialty chemicals, polyurethane systems and advanced materials businesses.
The deal is expected to deliver more than $400 million in cost and integration synergies, along with approximately $125 million in cash tax benefits. Closing remains targeted for the first half of 2027, subject to regulatory and customary conditions.
Huntsman Faces Demand, Tariff and Input-Cost Headwinds
Huntsman remains exposed to weak construction activity and uneven regional demand, particularly in Europe and China. Second-quarter 2026 industrial demand improved, but construction remained soft, and management’s third-quarter outlook still assumes weak construction end markets. European operations also face elevated input volatility, with global benzene and European natural-gas costs rising sharply after renewed Middle East hostilities. China adds another risk, as MDI pricing ended the second quarter materially below levels seen at the start of the period despite broader year-over-year pricing gains.
Changing tariff policies remain a risk to Huntsman’s cross-border shipments and global automotive exposure. The prior outlook cited tariff-related uncertainty as a constraint on industrial, construction, automotive and aerospace markets and noted cautious buying in automotive and construction. Although second-quarter 2026 Advanced Materials volumes increased in automotive, the company’s global footprint leaves demand and trade flows sensitive to further policy changes, which could limit the benefit from a broader industrial recovery.
Pricing actions offset higher raw-material costs in the second quarter of 2026, but management expects volatility to persist and has announced further price increases to counter higher benzene and European natural-gas costs. Third-quarter adjusted EBITDA is guided at $100-$130 million.
Huntsman Corporation Price and Consensus
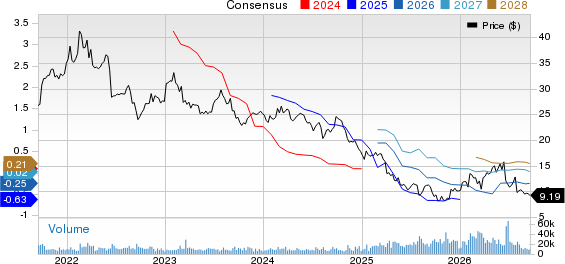
Huntsman Corporation price-consensus-chart | Huntsman Corporation Quote
HUN's Zacks Rank & Key Picks
HUN currently carries a Zacks Rank #3 (Hold).
Some better-ranked stocks in the Basic Materials space are Worthington Steel, Inc. WS and Innospec Inc. IOSP. WS currently sports a Zacks Rank #1 (Strong Buy), while IOSP carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for WS’ current-year earnings is $3.4 per share, implying a 52.5% year-over-year increase. Its earnings beat the Zacks Consensus Estimate in two of the trailing four quarters and missed twice, with the negative average surprise being 13.8%.
The Zacks Consensus Estimate for IOSP’s current-year earnings is pegged at $5.03 per share, implying a 4.55% year-over-year decrease. Its earnings beat the Zacks Consensus Estimate in each of the trailing four quarters, with the average surprise being 12.9%.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Huntsman Corporation (HUN): Free Stock Analysis Report
Olin Corporation (OLN): Free Stock Analysis Report
Innospec Inc. (IOSP): Free Stock Analysis Report
Worthington Steel, Inc. (WS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).