

Coursera, Inc. COUR is seeing strong momentum in its subscription business, with a sharp increase in paid subscribers providing a potentially important lever for improving profitability. However, sustaining this growth while managing pressure in transactional offerings remains key.
Coursera ended the second quarter of 2026 with more than 1.65 million paid subscribers, up 44% year over year. Consumer subscription revenues reached approximately $122 million, accounting for more than 75% of Consumer revenues. Management said core subscriptions remain the segment’s growth engine as the company shifts toward a subscription-first model. The improving subscription mix is also supporting margins. During the second quarter of 2026, consumer gross profit increased 37% year over year to $103.2 million, while segment gross margin expanded 380 basis points (bps) to 65.1%. Companywide adjusted gross margin climbed 620 bps to 62.2%, while adjusted EBITDA jumped 137% to $42.7 million, translating into a 14.3% margin.
COUR also raised its full-year 2026 adjusted EBITDA margin target to approximately 14%, up 100 bps from its June outlook. Fourth-quarter 2026 adjusted EBITDA margin is expected to exceed 16%, reflecting anticipated benefits from integration and synergy initiatives following the Udemy combination. Still, challenges remain. Consumer revenues declined 5% on a normalized basis, as subscription growth was offset by pressure in individual-program subscriptions and transactional offerings. Overall normalized revenues also declined 1%.
With recurring subscription streams now accounting for more than 85% of total revenues, Coursera's ability to sustain subscriber growth while converting its expanding recurring base into higher margins will be crucial to its profitability trajectory.
Coursera vs. Stride & Chegg: Who Has the Stronger User Base?
Coursera, alongside its market peers Stride, Inc. LRN and Chegg, Inc. CHGG, addresses different segments of the expanding online-learning market. Coursera offers courses, professional certificates, degrees and enterprise upskilling, and its combination with Udemy has created an ecosystem exceeding 300 million learners and 1.65 million paid subscribers. Paid subscribers rose 44% year over year in the second quarter of 2026, highlighting strong subscription traffic.
Meanwhile, Stride focuses on K-12 and career learning through virtual schools, curriculum, technology and support services. Its fiscal 2026 enrollments rose 4.2% to 243,900, with Career Learning enrollments increasing 13.9%. Chegg remains more concentrated in student learning and workforce skilling. However, the second quarter of 2026 revenues fell 51%, while Skilling revenues increased 2%, reflecting the ongoing shift toward employability-focused offerings.
COUR has a distinct scale and platform-breadth advantage, particularly following the Udemy combination, while its AI investments and growing subscription base align with rising demand for continuous skills development. However, its enterprise net retention rate was 91%, showing that corporate learning demand remains mixed.
COUR Stock’s Price Performance & Valuation Trend
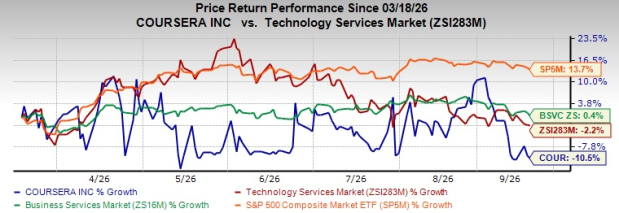
Shares of this California-based online learning platform provider have declined 10.5% over the past six months, underperforming the Zacks Technology Services industry, the Zacks Business Services sector and the S&P 500 Index, as the trendlines highlight below.
Image Source: Zacks Investment Research
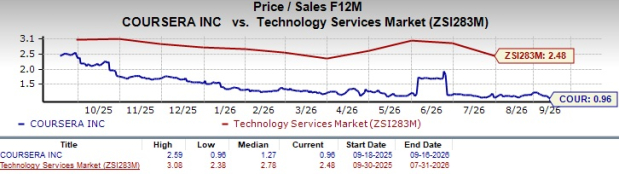
COUR stock is currently trading at a discount compared with its industry peers, with a forward 12-month price-to-sales (P/S) ratio of 0.96, as the trend lines suggest below.
Image Source: Zacks Investment Research
Earnings Estimate Revision of COUR
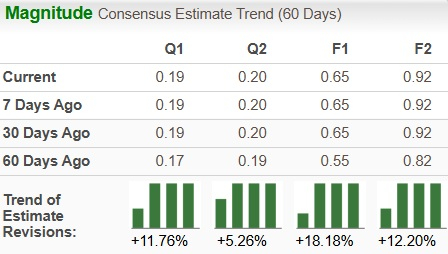
COUR’s earnings estimates for 2026 and 2027 have moved north to 65 cents and 92 cents per share, respectively, over the past 60 days. The revised estimated figures for 2026 and 2027 imply year-over-year growth of 66.7% and 40.3%, respectively.
Image Source: Zacks Investment Research
Coursera currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Coursera, Inc. (COUR): Free Stock Analysis Report
Stride, Inc. (LRN): Free Stock Analysis Report
Chegg, Inc. (CHGG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).